Published: April 20, 2020
Last Updated: October 27, 2026
Overview: Crystallizing the Lifetime Capital Gains Exemption Now Carries a Cash Cost
Crystallization is the deliberate triggering of a capital gain on qualifying shares, at a time when the shares still satisfy the conditions for the lifetime capital gains exemption, in order to claim the exemption against that gain and step up the adjusted cost base of the shares. The business is not sold. Nothing is received. The point is to use an entitlement that may not survive to the date of an eventual sale.
For most of the period in which this planning has been standard, the cost of doing it was professional fees and the loss of future flexibility. Since the 2024 taxation year, that is no longer true. The crystallizing transaction is itself an alternative minimum tax event, and it is the worst kind, because it generates a tax liability in a year in which the taxpayer receives no proceeds from which to pay it. On a crystallized gain of $1,275,000, the combined federal and Ontario minimum tax is in the order of $50,100, payable in April of the following year, out of funds that the transaction did not produce.
That does not make crystallization wrong. It makes it a transaction that has to be sized and timed rather than simply executed. This article sets out when crystallization still makes sense, what it now costs, the threshold below which it can be done without triggering minimum tax at all, and the traps that catch taxpayers who crystallize without planning the surrounding years.
Background: What Crystallization Does and Why It Is Done
An individual who owns shares of a qualified small business corporation has an entitlement under section 110.6 of the Income Tax Act to shelter up to $1,275,000 of capital gains in 2026. The entitlement is tested at the moment of disposition, not at the moment the owner forms an intention to sell. Qualification can be lost, and frequently is.
A corporation that accumulates cash, investments or other passive assets will fail the requirement that 90% or more of the fair market value of its assets be used in an active business. A corporation that goes public ceases to be a Canadian-controlled private corporation and cannot produce qualifying shares at all. A business that is eventually sold as assets rather than shares puts the transaction outside section 110.6 entirely. In each case an exemption that was available in year one has evaporated by year five, without the owner doing anything wrong.
Crystallization answers that risk by using the entitlement while it exists. The owner triggers a disposition at fair market value, claims the exemption against the resulting gain, and emerges holding shares whose adjusted cost base has been increased by the amount sheltered. Future appreciation is taxed normally, but the sheltered amount is locked in and is no longer hostage to the corporation’s asset mix or the structure of a future sale.
How the Transaction Is Usually Done
The common mechanics are an exchange of shares within the existing corporation, or a transfer of the shares to a holding corporation, with a joint election under subsection 85(1) filed on Form T2057 at an elected amount equal to fair market value rather than adjusted cost base. Electing at fair market value is what makes the transaction produce a gain; electing at cost would produce the ordinary rollover and no crystallization at all.
The choice between an internal exchange and a transfer to a holding corporation is not merely mechanical. A transfer of shares to a non-arm’s length holding corporation engages section 84.1, which can convert the intended capital gain into a deemed dividend and deny the exemption altogether. That provision catches taxpayers who are not surplus stripping and have no intention of doing so. For details, see Canadian Tax Planning via the Lifetime Capital Gains Exemption: Beware the Section 84.1 Tax Trap.
Purification normally precedes crystallization, since a corporation holding surplus passive assets will not satisfy the 90% test on the day the gain is triggered. The 24-month tests cannot be remedied at all within a two-year window, which is why crystallization is planning that has to begin years before it is needed. For the qualification conditions and the holding period in detail, see the lifetime capital gains exemption pillar and How to Master the 24-Month Holding Period Requirement for QSBC Shares.
Key Issues and Findings
The Crystallizing Transaction Is Now the Minimum Tax Event
This is the change that most published commentary on crystallization has not absorbed, including commentary written since 2024.
Since the 2024 taxation year, the alternative minimum tax applies a 20.5% rate to adjusted taxable income, with a basic exemption equal to the start of the fourth federal tax bracket, being $181,440 for 2026. A capital gain enters adjusted taxable income at 100%, while subparagraph 127.52(1)(h)(ii) recognizes only 7/5 of the capital gains deduction claimed under section 110.6. Because that deduction is claimed against the taxable half of the gain, 7/5 of one half offsets 70% of the whole gain, leaving 30% of it in the minimum tax base.
Consider an owner who crystallizes a gain of $1,275,000 in 2026 with no other income, deductions or credits. Regular federal tax is nil, because the exemption shelters the gain in full. For minimum tax purposes, the full $1,275,000 enters adjusted taxable income and the $637,500 deduction is recognized at 7/5, being $892,500, leaving adjusted taxable income of $382,500. Subtracting the basic exemption of $181,440 leaves $201,060, which at 20.5% produces a gross minimum tax of approximately $41,200.
The basic minimum tax credit, being one half of the credit for the base basic personal amount rather than the enhanced amount, which is ground down at this income level, reduces that by roughly $1,000, leaving federal minimum tax of about $40,200. Ontario’s additional tax for minimum tax purposes, at 24.63% of the federal amount, adds approximately $9,900 before surtax. That provincial amount does not ride on the federal seven-year credit, because Ontario operates its own minimum tax carryover and the two are recovered separately. The combined liability is in the order of $50,100.
The distinction that matters is what the taxpayer has in hand. An owner who claims the exemption on a genuine sale has received proceeds and can pay the minimum tax out of them. An owner who crystallizes has received nothing. The transaction produced a stepped-up adjusted cost base and a tax instalment obligation, and the second of those has to be funded from somewhere else.
“Crystallization used to be close to a free option. You paid your advisors, you locked in the exemption, and the only real question was whether you were giving up flexibility you might want later,” says David J. Rotfleisch, founding tax lawyer and CPA at Rotfleisch & Samulovitch, and a Law Society of Ontario Certified Specialist in Taxation. “Since 2024 it is not free, and what surprises clients is not the amount so much as the timing. There is a real tax bill in a year with no sale and no cash. I have seen owners crystallize on an accountant’s recommendation in the autumn and discover the following April that the planning they did to save tax has produced a tax payment they have to borrow to make.”
There Is a Threshold Below Which Crystallization Costs Nothing
The arithmetic above also produces the most useful planning number in this area, and it is not one the published commentary states.
Minimum tax applies only to the extent adjusted taxable income exceeds the basic exemption. Since a sheltered gain contributes 30% of itself to adjusted taxable income, a gain of $604,800 contributes exactly $181,440, which is the 2026 exemption. An individual with no other income can therefore crystallize up to roughly $604,800 of gain in a single taxation year and pay no minimum tax at all.
That figure is deliberately the conservative one. Because non-refundable credits are allowed at 50% in computing minimum tax, the basic minimum tax credit absorbs a small amount of tax above the threshold, so the true point at which minimum tax first becomes payable is nearer $621,700 on these assumptions. The difference is not worth planning into, because the credit amount depends on the taxpayer’s own circumstances, but it means $604,800 is a safe sizing figure rather than a cliff edge.
That figure is sensitive to the taxpayer’s other income, because the basic exemption is a single amount applied to the whole of adjusted taxable income rather than to each item within it. An owner drawing a salary or dividends has already consumed part of the exemption and the headroom is correspondingly smaller. The figure also moves each year with indexation of the fourth bracket.
The planning consequence is that a crystallization of $1,275,000 does not have to happen in one year. Staged across three taxation years, the same total can often be crystallized with little or no minimum tax, as the infographic below sets out, at the cost of three sets of professional fees and three years of exposure to the risk that qualification is lost in the interim.

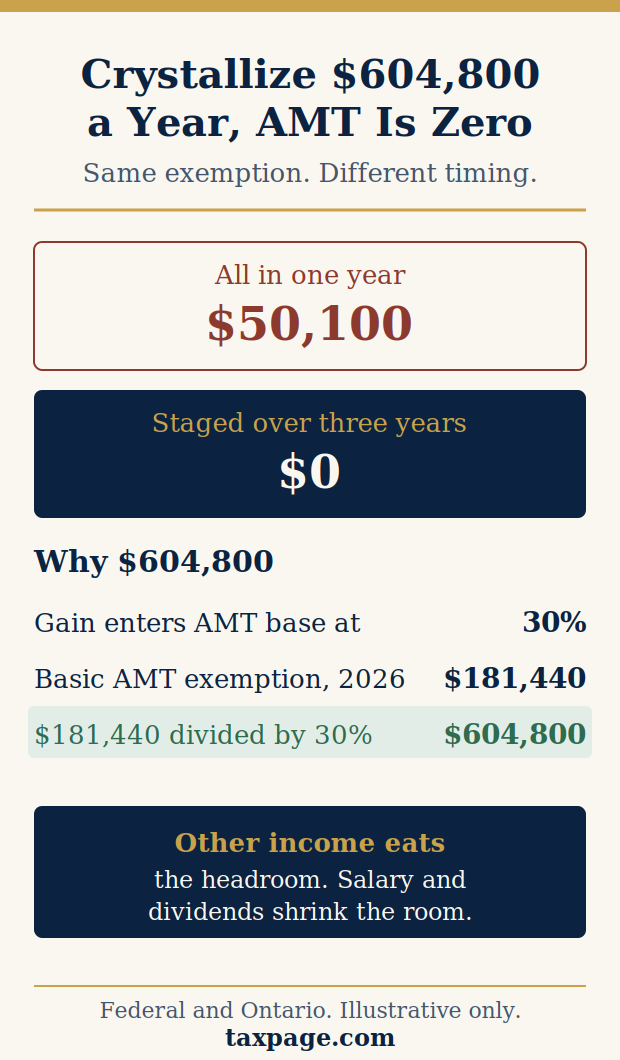
That is a genuine trade-off rather than an obvious answer, and the right balance depends on how fragile the corporation’s qualifying status actually is.
Partial Crystallization Is the Mechanism That Makes Staging Possible
Staging is only available because a crystallization is not an all-or-nothing transaction. The point is worth setting out, because the published commentary describes crystallization as though the whole accrued gain must be triggered.
Under subsection 85(1) the transferor and the corporation jointly elect an amount, and that elected amount becomes the transferor’s proceeds of disposition and the corporation’s cost. Electing at adjusted cost base produces a complete rollover and no gain at all. Electing at fair market value triggers the entire accrued gain. Electing anywhere between the two triggers exactly the gain chosen. That middle option is partial crystallization, and it allows an owner to size the triggered gain to a number rather than accept whatever the shares happen to have accrued. For the mechanics of the election generally, see Section 85 Rollovers: A Canadian Tax Lawyer’s Guide.
Applied to the threshold described above, an owner with $1,275,000 of accrued gain does not choose between triggering all of it and triggering none. The elected amount is set to produce a gain at or below the available headroom, the exemption is claimed against that gain, the adjusted cost base is stepped up by that amount, and the balance of the entitlement is preserved for a later year. The minimum tax cost of the first tranche is nil, and the exercise is repeated until the exemption is used.
The elected amount is not unconstrained. Paragraph 85(1)(c) prevents electing above the fair market value of the property, and an attempt to do so is deemed to be an election at fair market value. Paragraph 85(1)(b) prevents electing below the fair market value of any non-share consideration received, so a promissory note or assumed liability taken out of the transaction sets a floor that can defeat the sizing entirely: boot exceeding the adjusted cost base will force a gain larger than the one intended. For non-depreciable capital property, paragraph 85(1)(c.1) sets a further floor at the lesser of the adjusted cost base and the fair market value. The practical consequence is that a partial crystallization aimed at a particular number should generally be structured with share consideration only, because boot removes the precision the planning depends on.
Three further constraints distinguish a staged crystallization from a single one. Each tranche requires its own Form T2057, filed by its own deadline, supported by a valuation contemporaneous with that election; a valuation prepared for the first tranche does not support the third. Qualification must be satisfied at each election date rather than once, so three crystallizations expose the owner to the corporation failing the active business asset tests on any of three dates across three years. And the sizing must be done net of any cumulative net investment loss balance, because a gain sized precisely to the minimum tax headroom can still produce regular tax if the balance reduces the deduction below the gain triggered.
The trade-off is therefore not between paying tax and not paying tax. It is between a known minimum tax cost and an increased exposure to losing qualification partway through the exercise. Partial crystallization is the right default where qualifying status is stable and the owner is acting out of prudence. A single full crystallization is the better answer where qualification is genuinely fragile, because a quantified $50,100 is preferable to a real prospect of losing an entitlement worth several times that.
The Seven-Year Credit Is a Poor Answer for a Crystallizer
Minimum tax paid in excess of regular tax becomes a credit applicable against regular federal tax in the following seven taxation years. Commentary routinely treats this as making the minimum tax a timing matter rather than a cost. For a crystallizer that reassurance is weaker than it sounds, for two reasons.
The first is that crystallization is typically undertaken by an owner who is not selling. The regular federal tax needed to absorb the credit must come from somewhere, and an owner who continues to draw modest remuneration from the corporation may generate little of it. The second, and more serious, is that crystallization is undertaken precisely because the sale is distant or uncertain. An owner who crystallizes in 2026 and sells in 2035 has watched the credit expire unused in 2033. The further away the eventual sale, which is the usual reason for crystallizing, the less likely the credit is ever recovered.
The honest way to put it is that minimum tax on a crystallization should be modelled as a cost unless the taxpayer can identify the regular tax that will absorb it within the window. It is recoverable in principle and frequently not in practice.
Crystallization Interacts With Other Provisions, Mostly Adversely
Several consequences follow from the fact that the crystallized gain increases net income even though it does not increase taxable income.
Income-tested benefits and credits are calculated on net income. A crystallization can therefore reduce or eliminate Old Age Security, the age credit, and other amounts in the year it is triggered, and for an owner near the Old Age Security recovery threshold that cost can exceed the minimum tax.
A claim under section 110.6 reduces the amount available for an allowable business investment loss, because subsection 39(9) requires a business investment loss to be reduced by gains in respect of which the exemption has been claimed. An owner who crystallizes and later suffers a genuine loss on another venture may find the loss blocked.
A cumulative net investment loss balance reduces the deduction that can be claimed, so an owner who crystallizes without first checking the balance on Form T936 may shelter less than expected and face regular tax on the difference as well as minimum tax.
Finally, crystallization is irreversible. The exemption, once claimed, is gone, and the indexed limit will be higher in later years. An owner who crystallizes the full amount in 2026 and sells in 2031 has used an exemption measured by the 2026 limit against a gain that would have attracted a larger one.
When Crystallization Still Makes Sense
None of the above means the planning is obsolete. It means the case for it has to be made rather than assumed.
Crystallization remains clearly worthwhile where qualification is genuinely at risk and the risk is near-term: a corporation steadily accumulating passive assets that purification cannot keep ahead of, a business on a path toward an initial public offering, or a vendor who expects that any realistic purchaser will insist on buying assets rather than shares.
It also remains worthwhile as part of an estate freeze, where the owner is exchanging common shares for fixed-value preferred shares and transferring future growth to the next generation or to a family trust. The crystallization is incidental to a reorganization that is happening anyway, and the stepped-up adjusted cost base on the preferred shares has value on a later redemption or on death.
Where qualification is stable, the sale is distant, and the only argument for acting is that the rules might change, the calculation is now considerably less attractive than it was before 2024, because the minimum tax is certain and the legislative risk is speculative.
Practical Implications for Canadian Taxpayers
A crystallization proposal should be accompanied by a projection on Form T691 showing the minimum tax consequence on a combined federal and provincial basis, an assessment of whether the resulting credit will be absorbed within seven taxation years, and an identification of the cash that will fund the liability. A proposal that does not address all three is incomplete.
The staging question should be asked expressly in every case. If the exposure can be eliminated by spreading the crystallization across enough taxation years that each tranche falls within the annual headroom, and qualification is not at immediate risk, the minimum tax cost of acting in a single year is a cost incurred for no reason.
The planning should also be run against the alternatives rather than in isolation. An owner contemplating an eventual sale to a child should consider whether the intergenerational transfer provisions produce a better outcome than a crystallization now, and the minimum tax dimension of that comparison is set out in Tax Planning for Intergenerational Business Transfers and Alternative Minimum Tax.
An owner who is elderly should weigh crystallization against the exemption being claimed on the deemed disposition at death, where minimum tax does not apply at all in the year of death. An owner contemplating leaving Canada should model the departure tax consequences together with the exemption, since an emigrant has the least prospect of recovering a minimum tax credit.
Crystallization transactions attract CRA attention, both because the valuation underpinning the elected amount is a matter of judgment and because section 84.1 and the general anti-avoidance rule are live in this area. Contemporaneous valuation evidence, a properly completed Form T2057 filed on time, and corporate records establishing qualification throughout the relevant periods are what defend the position. Where the CRA reassesses, the ordinary rights apply: a notice of objection under section 165 of the Income Tax Act and, if that does not resolve matters, an appeal to the Tax Court of Canada.
Takeaway: Size and Stage the Crystallization Rather Than Simply Executing It
Crystallization locks in an entitlement that may not survive to the date of sale, and that remains a real benefit for owners whose qualifying status is fragile. What has changed since 2024 is that the transaction now generates a cash tax liability in a year with no cash, and that the credit which is supposed to make that liability temporary is least likely to be recovered by exactly the taxpayers who crystallize.
The practical answer is rarely to abandon the planning and rarely to execute it in a single year. It is to establish how much exemption can be crystallized within the minimum tax headroom, to stage the balance across taxation years where qualification permits, and to proceed in one year only where the risk of losing qualification outweighs a known and quantified tax cost.
Pro Tax Tips
Before any crystallization is implemented, a projection should be prepared showing the regular tax calculation and the minimum tax calculation side by side, on a combined federal and provincial basis, for each of the single-year and staged alternatives. That projection should identify the headroom available in the current year after the taxpayer’s other income is taken into account, because the basic exemption is applied once against the whole of adjusted taxable income and salary or dividends drawn in the same year reduce the amount of gain that can be crystallized without cost. The projection should then state plainly where the cash to pay any resulting liability will come from, since the transaction itself produces none, and whether a dividend or bonus drawn to fund it will itself consume headroom and increase the exposure.
Alongside that, the cumulative net investment loss balance should be retrieved and any prior allowable business investment loss identified, because both reduce the deduction actually available and a crystallization sized against the headline limit may produce regular tax as well as minimum tax. Where the corporation requires purification, that should be completed and documented before the crystallization rather than contemporaneously with it, and where shares are to be transferred to a holding corporation the section 84.1 analysis should be settled in advance rather than discovered on a later tax audit. A valuation prepared at the time of the transaction, by someone qualified to defend it, is worth considerably more than a reconstruction prepared after a CRA query.
FAQs
What does it mean to crystallize the lifetime capital gains exemption?
Crystallizing means deliberately triggering a capital gain on qualifying shares while the shares still satisfy the conditions for the exemption, claiming the exemption against that gain, and thereby stepping up the adjusted cost base of the shares. The business is not sold and no proceeds are received. The purpose is to use an entitlement that might not be available later if the corporation ceases to qualify or the eventual transaction is structured as an asset sale.
Does crystallizing trigger alternative minimum tax?
Yes, in most cases above a threshold. A gain sheltered by the exemption enters adjusted taxable income at an effective 30%, because the gain is included at 100% while the section 110.6 deduction is recognized at 7/5 of the amount claimed. Minimum tax then applies to the extent adjusted taxable income exceeds the basic exemption of $181,440 for 2026.
How much can I crystallize without paying minimum tax?
For an individual with no other income in the year, roughly $604,800 of gain, because 30% of that amount equals the $181,440 basic exemption. The figure falls as other income rises, since the basic exemption is applied once against the whole of adjusted taxable income rather than against the crystallized gain alone, and it moves annually with indexation.
What would the minimum tax be on a full crystallization?
On a crystallized gain of $1,275,000 in 2026, with no other income, deductions or credits, and for an Ontario resident: adjusted taxable income of $382,500, less the $181,440 exemption, taxed at 20.5%, giving federal minimum tax of about $40,200 after the basic minimum tax credit, with Ontario adding approximately $9,900 before surtax, for a combined liability in the order of $50,100.
Can I pay the minimum tax out of the transaction?
No, and this is the practical difficulty that distinguishes crystallization from a sale. A crystallization produces a stepped-up adjusted cost base, not proceeds. The liability has to be funded from other resources, and if it is funded by drawing a dividend or bonus from the corporation, that remuneration increases adjusted taxable income in the same year and can increase the minimum tax it was drawn to pay.
Is the minimum tax recoverable?
In principle. Federal minimum tax paid in excess of regular federal tax becomes a credit applicable against regular federal tax in the following seven taxation years, and Ontario operates a separate provincial carryover. In practice a crystallizer is often the worst-placed taxpayer to recover it, because crystallization is usually undertaken when a sale is distant and by an owner whose ongoing regular tax is modest. If the sale occurs more than seven years later, the credit expires unused.
Can I crystallize only part of the accrued gain?
Yes. The joint election under subsection 85(1) fixes the proceeds of disposition at whatever amount the parties elect, within statutory limits, so the gain triggered is the gain chosen. Electing at adjusted cost base produces no gain, electing at fair market value triggers the whole accrued gain, and electing between the two triggers exactly the amount required. This is what allows a crystallization to be sized to the annual minimum tax headroom rather than to the full value of the shares.
What limits the elected amount on a partial crystallization?
Three rules. Paragraph 85(1)(c) prevents electing above fair market value. Paragraph 85(1)(b) prevents electing below the fair market value of any non-share consideration received, so taking back a promissory note or having the corporation assume a liability sets a floor. For non-depreciable capital property, paragraph 85(1)(c.1) imposes a further floor at the lesser of adjusted cost base and fair market value. A partial crystallization intended to hit a specific number should generally be structured with share consideration only, since boot can force a larger gain than intended.
Should I stage a crystallization across several years?
Often, yes, provided enough years are used. The test is whether each tranche falls within the annual headroom, not simply whether the total is spread. On an accrued gain of $1,275,000, two tranches of $637,500 each exceed the headroom and leave roughly $1,200 of combined minimum tax across the two years, while three tranches of $425,000 each sit comfortably inside it and produce nothing at all. Where qualification is stable, staging across sufficient years can therefore eliminate the minimum tax entirely, at the cost of additional professional fees and continued exposure to the risk that the corporation ceases to qualify in the interim. Where qualification is at near-term risk, acting in one year and accepting the tax is the better choice.
How is a crystallization actually implemented?
Usually by an exchange of shares within the existing corporation, or a transfer of the shares to a holding corporation, with a joint election under subsection 85(1) filed on Form T2057 at an elected amount equal to fair market value rather than adjusted cost base. Electing at fair market value is what produces the gain; electing at cost produces an ordinary rollover and no crystallization.
What is the section 84.1 risk?
Section 84.1 applies where an individual transfers shares to a non-arm’s length corporation and can convert the intended capital gain into a deemed dividend, denying the exemption. It catches taxpayers who have no surplus-stripping intention, and it is the most common technical failure in crystallization planning. The analysis should be settled before the transaction, not after.
Does crystallizing affect my Old Age Security?
It can. The crystallized gain increases net income even though the exemption removes it from taxable income, and income-tested amounts including Old Age Security and the age credit are calculated on net income. For a recipient near the recovery threshold, the clawback in the year of crystallization can exceed the minimum tax.
Can crystallizing reduce a future business investment loss claim?
Yes. Subsection 39(9) requires a business investment loss to be reduced by capital gains in respect of which a deduction under section 110.6 has been claimed. An owner who crystallizes and later suffers a genuine loss on a different venture may find the allowable business investment loss blocked to that extent.
Is crystallization reversible if I change my mind?
No. The exemption, once claimed, is used. Because the limit is indexed, an owner who crystallizes in full in one year and sells several years later will have sheltered the gain using a smaller limit than would have been available at the time of sale.
When does crystallization still clearly make sense?
Where qualifying status is at genuine near-term risk, because the corporation is accumulating passive assets faster than purification can address, because an initial public offering is contemplated, or because any realistic purchaser will want to buy assets rather than shares. It also remains sensible as part of an estate freeze, where the reorganization is happening in any event.
Should I crystallize rather than rely on the exemption at death?
Not automatically. Minimum tax does not apply in the year an individual dies, so the exemption claimed against the deemed disposition on death carries no minimum tax consequence at all. For an elderly owner whose corporation is likely to remain qualified, waiting may be materially cheaper than crystallizing, and the two should be modelled against each other.
When should I involve a Canadian tax lawyer?
Before the transaction is implemented. Crystallization engages the qualification tests, section 84.1, the valuation of the shares, the minimum tax projection, and the general anti-avoidance rule, and most of what determines the outcome is fixed by decisions made before the election is filed. An experienced Canadian tax lawyer can structure the transaction, size and stage it, and defend the position on a subsequent CRA tax audit or tax reassessment.
DISCLAIMER: This article provides broad information. It is only accurate as of the posting date. It has not been updated and may be out-of-date. It does not give legal advice and should not be relied on as tax advice. Every tax scenario is unique to its circumstances and will differ from the instances described in the article. If you have specific legal questions, you should seek the advice of a Canadian tax lawyer.
About the Author