Case Overview – A Win Without a Court Hearing
After the Canada Revenue Agency (CRA) denied the Taxpayer’s Canada Recovery Benefit (CRB) eligibility twice, our client faced a substantial repayment demand. He wanted another opportunity to have his evidence considered fairly, without the additional legal expense of a Federal Court hearing.
TaxPage secured exactly that result: a 3rd CRA review by officers who had not previously been involved in his application. We achieved our client’s objective through settlement, avoiding the further legal fees of arguing the case at a hearing. The CRA charges no fee to conduct the review.
The Problem – 2 Denials, a Disputed Income Calculation and a Repayment Demand
Jack (name withheld due to solicitor-client confidentiality) was a self-employed professional whose business suffered during the COVID-19 pandemic. His clients faced serious financial difficulties, and his usual work and earnings declined. To preserve those relationships and keep his business going, he reduced his fees and sometimes continued providing services without payment.
Like many self-employed Canadians affected by the pandemic, Jack applied for CRB. The CRA subsequently reviewed his eligibility and concluded that he had not established the minimum qualifying income. CRA then demanded repayment of the benefits he had received.
Jack requested a 2nd review and explained why he believed the CRA’s conclusion was wrong. The CRA again denied eligibility. This time, it also relied on a concern about whether he met the COVID-19-related income reduction requirement.
Two adverse decisions had left Jack facing the same problem. TaxPage’s task was to secure a fresh assessment of his claim through a process that made financial sense for him.
Why Jack’s Canada Recovery Benefit Denial Deserved a Closer Look
A disputed expense classification affected the $5,000 income threshold
Jack’s originally reported net self-employment income fell just below the CRB’s $5,000 qualifying income threshold. When reviewing his records, Jack identified personal expenses that he said had mistakenly been deducted as business expenses. Correcting that classification, he maintained, would put his net income above the threshold.
For CRB purposes, the distinction between gross revenue and net self-employment income matters. The legislation defines self-employment income by deducting expenses incurred to earn the revenue. Whether a particular expense properly belongs in that calculation can therefore affect eligibility.
The CRA’s internal notes acknowledged Jack’s proposed correction but questioned whether the supporting documents established it. Canadian tax lawyers at TaxPage examined how the reviewing officer had dealt with his explanation and the evidence. We challenged whether the resulting decision was adequately justified.
The pandemic’s effect on his business needed proper consideration
Jack had reduced his fees because his clients were struggling during the pandemic. Our position was that those reductions had to be understood in their commercial context: preserving client relationships was part of trying to sustain his business through COVID-19 disruption.
We also challenged the fairness of the review process. Jack’s position was that the CRA had focused its requests on the minimum threshold without giving him a meaningful opportunity to answer the separate concern about his income reduction.
These issues gave our lawyers at TaxPage specific grounds on which to challenge the 2nd review decision and pursue a fresh review.
Our Approach – Use Judicial Review to Secure a Practical Result
Set the objective before choosing the strategy
Our objective was clear from the outset: obtain a 3rd review. We wanted Jack’s claim reconsidered by officers who had not previously handled it, without incurring the additional legal fees of taking the application through a court hearing.
An application for judicial review can provide a route to challenge an adverse CRA 2nd review decision. The Federal Court can examine the lawfulness of the decision and the fairness of the process and can set a decision aside and return the matter for reconsideration.
For Jack, that made judicial review a means of pursuing the 3rd review he needed. Settlement could achieve that objective before a hearing became necessary.
Built the case for reconsideration
Our Canadian tax litigation lawyers filed the judicial review application, obtained the CRA’s decision making record, and examined the reasons behind the denial. We prepared Jack’s affidavit and supporting materials and served written cross examination questions concerning the reviewing officer’s evidence.
This work allowed us to access the decision against the actual record. We could identify the disputed evidence, explain our concerns about the reviewing process, and present a concrete basis for asking that the matter be reconsidered.
Maintain pressure while pursuing settlement
The proceeding encountered delays. Our lawyers continued advancing the file, preparing the required court materials and pursuing hearing arrangements while maintaining settlement discussions with Department of Justice lawyer acting for the CRA.
Taking those procedural steps supported our effort to resolve the matter. Though, the desired outcome remained the same: a 3rd review without the additional expense of a hearing.
The Result – TaxPage Secured the 3rd CRA Review
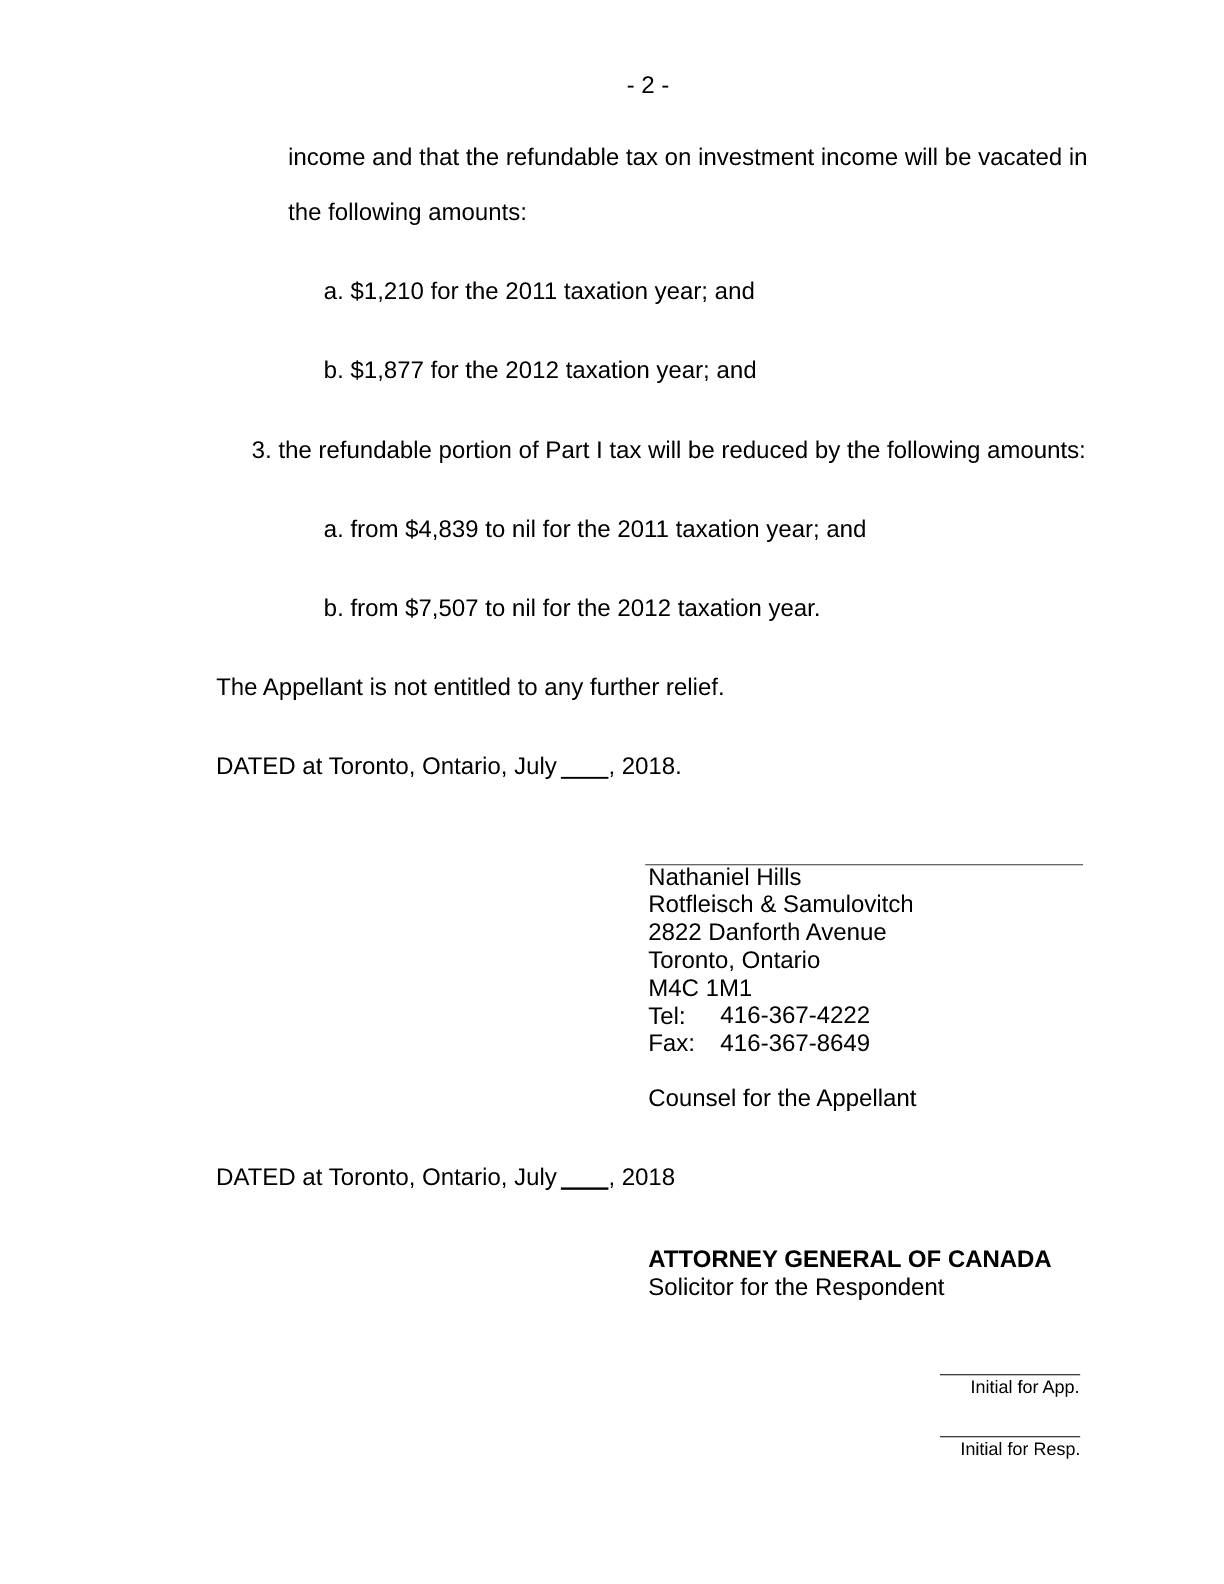
We achieved our objective. The settlement provided for the challenged 2nd review decision to be set aside and Jack’s CRB application to be reconsidered by CRA officers who had not previously been involved. The Federal Court application was then discontinued in accordance with the settlement.
For Jack, the benefits were concrete:
- A 3rd CRA Review: another opportunity to have his eligibility assessed after 2 denials;
- Different reviewing officers: reconsideration by officers who had not previously handled his CRB application;
- No court hearing: avoiding the additional legal fees required to argue the judicial review application at a hearing.
Why a cost-conscious litigation strategy matters
A benefits dispute can put a taxpayer under financial pressure before legal proceedings even begin. The cost of the next step matters alongside the strength of the legal argument.
In Jack’s case, our strategy connected the work we undertook to the outcome he wanted. We used the judicial review process to challenge the denial, developed the record, and persisted with settlement discussions until we secured an agreement for a 3rd review.
The distinction between the costs is straightforward. Jack incurred legal fees for our work in obtaining the settlement. The CRA’s 3rd review carried no review fee, and the settlement avoided further legal expense of a Federal Court hearing.
For taxpayers considering whether to challenge a CRB denial, this is a useful question to ask a lawyer: what result would solve the immediate problem, and what is the most effective way to pursue it?
Pro Tax Tips – What to do after a CRB 2nd Review Denial
Have the decision reviewed promptly. The usual deadline for judicial review is 30 days after the decision is first communicated. A Federal Court of Canada Judge may allow additional time, but taxpayers should not assume that an extension will be granted.
Preserve the evidence behind your explanations. Keep invoices, expense receipts, bank records, correspondence and copies of your submissions to the CRA. If an expense was misclassified, explain the correction and provide the documents to support it.
Show how COVID-19 affected the relevant benefit periods. Explain the relationship between the pandemic, your work and your earnings. A decline in annual income alone may not answer the CRA’s questions about particular CRB periods.
Discuss the desired result and its cost with your lawyer. A settlement for reconsideration may achieve your objective without a hearing. Jack’s case illustrates why that possibility should be considered as part of a focused litigation strategy.
Frequently Asked Questions (FAQs)
Can I obtain a 3rd CRA review after my CRB claim has been denied twice?
It may be possible. In Jack’s case, TaxPage challenged the 2nd review decision through applying for judicial review at Federal Court of Canada and secured a 3rd review through settlement. A 3rd review is not automatic; the decision, the record and the available grounds for challenge need to be assessed.
Does obtaining a 3rd review require a court hearing?
Not necessarily. Jack’s case settled before a hearing. TaxPage obtained the reconsideration we had sought through negotiations supported by the judicial review proceeding.
Does the CRA charge for a 3rd review?
The CRA does not charge a fee to conduct the reconsideration. Legal fees for obtaining that review or retaining a lawyer to assist with it are separate. In Jack’s case, settlement avoided the additional legal fees of proceeding to a Federal Court hearing.
What is judicial review?
Judicial review is the process where the Federal Court examines whether a CRA decision was reasonable and fair. It is not an appeal, and the Court does not re-decide the underlying eligibility question.
What is the deadline to file a judicial review application?
An application for judicial review must generally be filed within 30 days of the CRA decision being communicated, though the Federal Court can grant an extension in appropriate circumstances.
What is the difference between the Tax Court of Canada and the Federal Court?
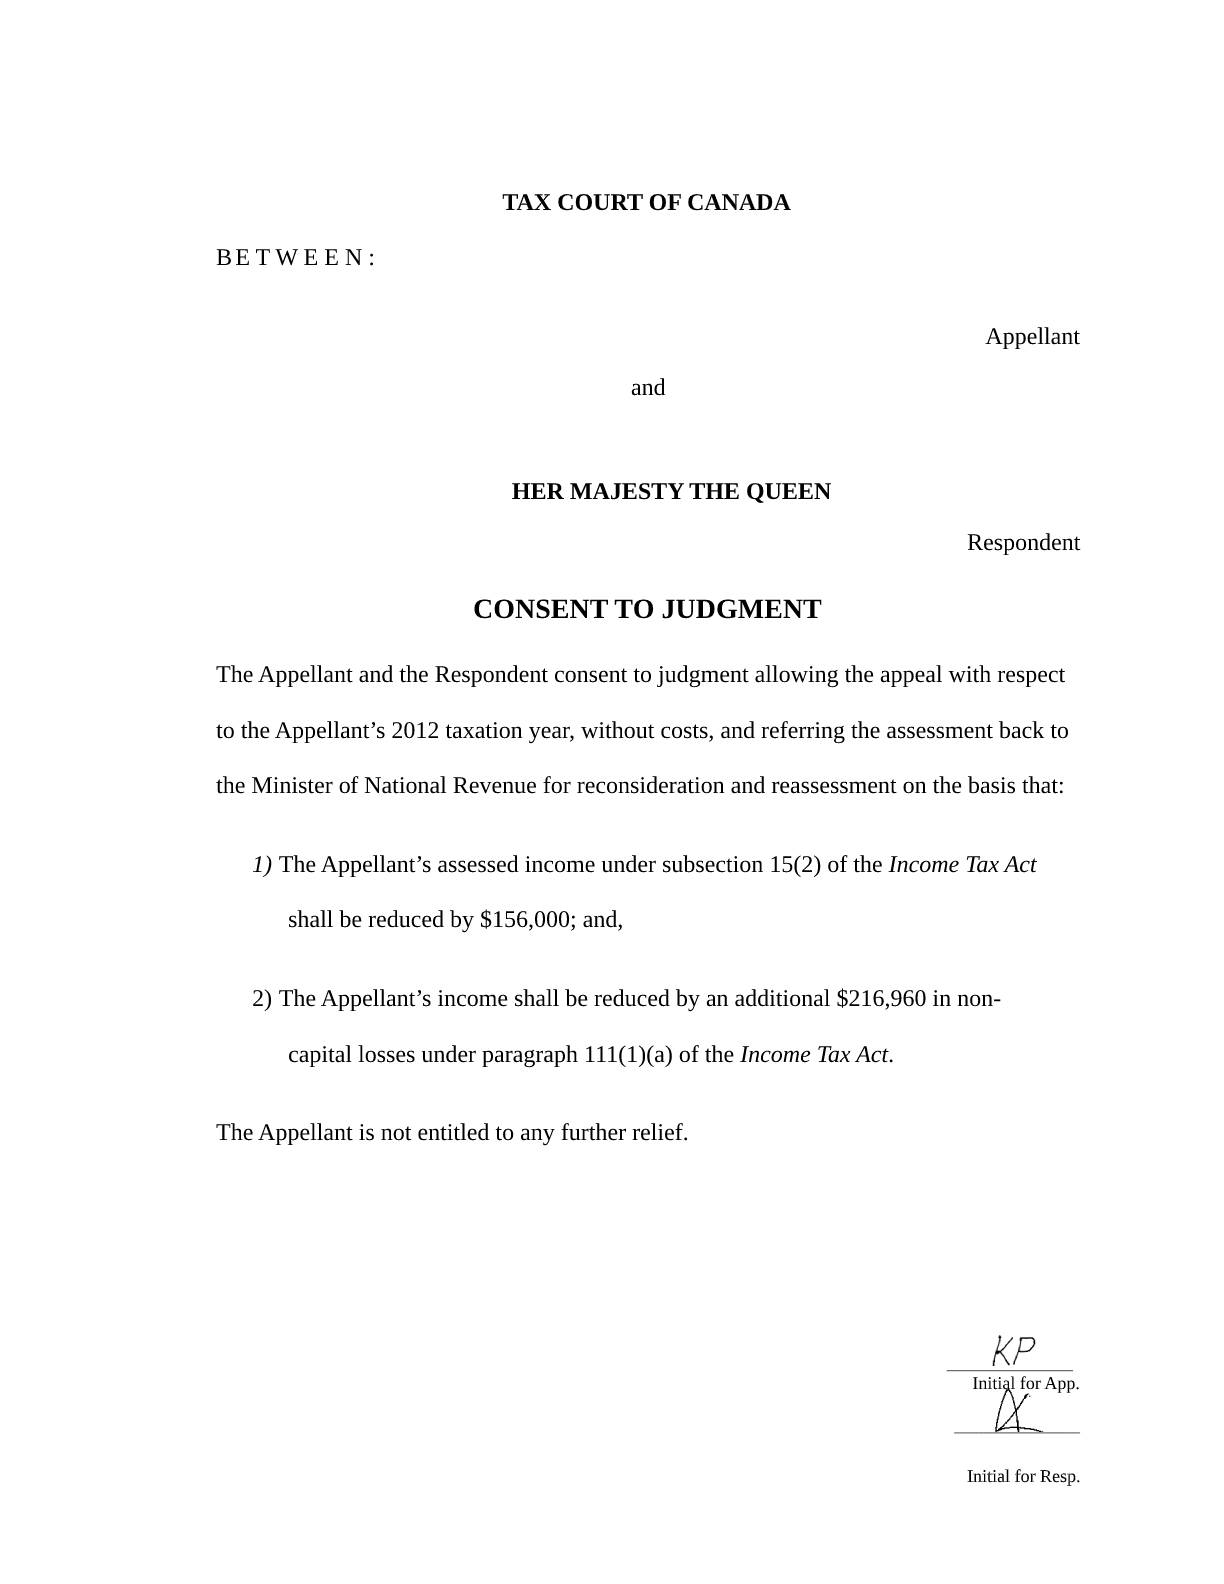
The Tax Court of Canada hears appeals of tax assessments and reassessments. The Federal Court reviews discretionary CRA decisions, such as CRB eligibility determinations, that fall outside the Tax Court’s jurisdiction.
Can I appeal a CRB denial to the Tax Court of Canada instead?
No. CRB eligibility decisions are discretionary decisions of the CRA, so they are reviewed by the Federal Court through a judicial review application, not appealed to the Tax Court.
What evidence should I gather if I plan to challenge a CRB denial?
Keep records that support your reported income and any expense classifications, such as invoices, receipts, bank records, and correspondence with the CRA. These form the record that a reviewing officer or the Federal Court will consider.
Is it possible to settle a judicial review application before a hearing?
Yes. As in Jack’s case, a judicial review application can be resolved through settlement discussions with the CRA before a hearing is required, which can reduce both the cost and the time involved.
Does filing a judicial review application guarantee a different result?
No. A judicial review only requires the CRA to reconsider the decision. It does not guarantee that a new review will result in a different outcome.
Are settlement discussions with the CRA confidential?
Settlement discussions are generally conducted on a without-prejudice basis, meaning the substance of the discussions generally cannot be used against either party if the matter proceeds to a hearing.
How long does the judicial review and reconsideration process typically take?
Timelines vary by case complexity and CRA workload, but the process generally involves several months from filing the application to a reconsideration decision being issued.
CRB Denied? Contact TaxPage
If the CRA has rejected your CRB claim on 2nd review, have TaxPage assess the decision before the judicial review deadline passes. Our expert Canadian tax lawyers at TaxPage can examine your evidence, identifying potential grounds for challenge, and discuss a strategy that considers both your objective and the costs.
Disclaimer: This case study provides information of a general nature only. It is only accurate as of the posting date. It has not been updated and may be out-of-date. It does not give legal advice and should not be relied on as tax advice. Every tax scenario is unique to its circumstances and will differ from the instances described in this case study. If you have specific legal questions, you should seek the advice of a Canadian tax lawyer.
Overview: An Old CRA Tax Debt Still Showing as a Judgment
Our tax law firm recently closed a matter in which a client came to us after discovering that a CRA tax debt believed to be long settled was still showing up as an active court judgment on the client’s credit report. The judgment was standing in the way of a financing transaction, and the client needed documented proof, quickly, that the underlying tax debt had actually been paid. This case illustrates a problem we see recur: the CRA’s collection remedies can create a public court record that outlives the debt itself, and clearing that record takes more than confirming a zero balance with the CRA.
Background: How a CRA Certificate Becomes a Federal Court Judgment
Years earlier, the CRA had certified an amount of unpaid tax against the client under subsection 223(2) of the Income Tax Act and registered that certificate with the Federal Court under subsection 223(3), as it is entitled to do without advance notice to the taxpayer. Once registered, a certificate of this kind is deemed to be a judgment of the Federal Court, and it can surface on a credit report the same way any other civil judgment would.
The CRA can also use a registered certificate to support a lien or similar remedy against a taxpayer’s property, a topic covered in more detail in our overview of CRA tax debts and liens.
By the time the client retained us, the CRA account showed no outstanding balance and the matter was believed to be closed. The judgment nonetheless remained visible to the lender reviewing the file, because paying the CRA does not, on its own, update the Federal Court record or notify credit bureaus that a certified debt has been satisfied.
For more on the CRA’s collection powers generally, including how certificates and related remedies fit into the CRA’s broader toolkit, see our article on CRA collections and limitation periods.
Key Issues and Findings: Proving a CRA Judgment Has Been Paid
Once retained, we put a CRA authorization in place, both online and by offline authorization form, since the CRA will not discuss the specifics of an account with a representative until that authorization is on file. With authorization confirmed, we reviewed the client’s CRA account and verified that it showed no outstanding balance for the certified amount.
A CRA account balance on its own is informal evidence, however, and not a formal discharge of a certificate that has already been registered as a Federal Court judgment. Because the CRA’s regular collections line, the same line the CRA also uses for other enforcement tools such as a requirement to pay, could not provide timely written confirmation, and because the certificate itself lived in the Federal Court record rather than in a CRA file, we went to the source: we obtained the details of the original certificate and confirmed, from the court’s own records, that the certified judgment amount had been satisfied.
With the CRA account status and the Federal Court information both in hand, we prepared a reporting letter to the client setting out our findings and confirming that the debt underlying the judgment had been fully paid, giving the client documentation to put in front of the lender.
Practical Implications: Clearing a CRA Judgment From Your Credit Report
For taxpayers in a similar position, the sequence that resolved this matter reflects the practical path forward generally: confirm the CRA’s internal position on the account, put a valid CRA authorization in place so a representative can deal with the CRA directly, and, where the CRA cannot provide timely written confirmation on its own, go directly to the Federal Court record for the certificate and any confirmation of its satisfaction.
Court records confirming satisfaction of the debt can often be provided directly to a lender or financing company on their own. Where that documentation still falls short of what a particular lender requires, a lawyer’s reporting letter summarizing the findings, as in this matter, can serve the same purpose.
It is also worth noting that resolving the debt and obtaining proof of payment does not automatically update a credit bureau file. Taxpayers should expect to take a further step, often through their lender or broker, or by filing a dispute directly with Equifax and TransUnion, to have the judgment entry corrected once proof of satisfaction is in hand. A dispute submitted with the CRA account confirmation and the Federal Court record attached gives the bureau documentation to investigate against, since an entry that still shows the judgment as outstanding once it has actually been satisfied is a legitimate basis for correction. The entry itself will typically still remain on file for its full retention period, but corrected to show the debt as paid.
Takeaway: Removing an Old CRA Judgment From Your Credit File
This matter closed within about six weeks of the client first contacting us, but the timeline turned on how quickly a valid CRA authorization could be put in place and how quickly the Federal Court record could be retrieved. The larger lesson holds for any taxpayer in a similar position: paying a CRA debt and clearing the court record it left behind are two different steps, and an old CRA certificate can keep showing up as a judgment on a credit report long after the underlying tax debt is gone.
“Paying off a CRA debt and clearing it from your record are two different things. Once the CRA registers a certificate with the Federal Court, that court record has a life of its own, and it can keep showing up on a credit report long after the underlying tax debt is gone. The fix usually isn’t more back and forth with CRA collections; it’s going straight to the Federal Court file for the paper trail that actually proves the debt was paid.”
— David J. Rotfleisch, Certified Specialist in Taxation Law (Law Society of Ontario).
Pro Tax Tips: Dealing With an Old CRA Judgment on Your Credit Report
Taxpayers who are in the process of financing a home, vehicle, or other major purchase should check their credit report well before signing any agreements, since an old CRA certificate or judgment can take real time to resolve and lenders are often unwilling to proceed until it is cleared up. Taxpayers who suspect an old CRA debt may still be attached to their name should put a CRA authorization in place as early as possible, since a representative cannot make any inquiries or request records until that authorization has been processed. Where a financing deadline is tight, it is worth asking directly whether the CRA’s emergency collections channel is available, since the standard collections line may not be positioned to provide timely written confirmation.
Taxpayers should also keep in mind that a Federal Court record of a certificate and its satisfaction is often stronger, more independent evidence than anything the CRA itself can provide, and pursuing that record directly can resolve the issue faster than waiting on CRA correspondence. Finally, once proof of payment is obtained, taxpayers should follow up with their lender, broker, or the relevant credit bureau to make sure the judgment entry on their credit file is actually corrected, since obtaining proof and having the record updated are two separate steps.
FAQs: CRA Judgments and Credit Reports
Why would a CRA tax debt that I already paid still show up on my credit report?
The CRA can register an unpaid tax amount as a certificate with the Federal Court, which is deemed to be a court judgment. Paying the underlying tax debt does not automatically update that court record or notify credit bureaus, so the judgment entry can remain visible even after the debt is fully satisfied.
What is a section 223 certificate under the Income Tax Act?
Under subsection 223(2) of the Income Tax Act, the CRA can certify an amount of unpaid tax and register that certificate with the Federal Court under subsection 223(3). Once registered, the certificate has the same effect as a judgment obtained against the taxpayer in that court.
Does the CRA notify credit bureaus once a certified tax debt is paid?
Not automatically. Resolving the debt with the CRA does not by itself trigger an update to the Federal Court record or to a taxpayer’s credit file, which is why taxpayers often need to take further steps on their own.
Is a CRA online account balance of zero enough to prove my tax debt is paid?
It can be useful supporting evidence, but a CRA My Account balance is an informal internal snapshot rather than a formal discharge of a registered certificate, and a lender or credit bureau may require more formal documentation before treating the matter as resolved.
What is the CRA Collections Emergency Line and when should I use it?
It is an escalation channel within CRA Collections intended for time-sensitive matters. Taxpayers facing an urgent financing deadline who cannot get timely written confirmation through the regular collections line may need to use this channel to get faster attention.
How can I get official proof that a CRA certificate and judgment have been satisfied?
The most reliable source is often the Federal Court itself. Taxpayers or their representatives can request the original certificate registering the debt, along with any Federal Court record confirming that the certified debt was satisfied, which together provide independent, court-issued proof of payment.
Do I need to authorize someone before they can deal with the CRA on my behalf?
Yes. The CRA requires a valid representative authorization, arranged online or through an offline authorization form, before a lawyer or other representative can access account details or make inquiries about a specific tax debt.
What if the CRA cannot or will not confirm in writing that my debt has been paid?
When the CRA is unable or unwilling to issue its own written confirmation, a lawyer can review the available CRA and Federal Court records and prepare a letter setting out findings that confirm, based on that evidence, that the debt has been fully paid.
Will resolving the debt automatically remove the judgment from my credit report?
No, and it is worth being precise about what actually happens next. Obtaining proof that the debt is satisfied is a separate step from having a credit bureau update the entry on a credit file, and accurate judgment information generally stays on file for its full retention period regardless of payment status. What resolving the debt allows a taxpayer to do is file a dispute directly with Equifax or TransUnion, attaching the CRA confirmation and Federal Court documentation, so the bureau investigates and corrects the entry to show the debt as paid rather than outstanding.
How long does a CRA judgment stay on my credit report?
Retention periods are set by the credit bureaus and vary by province. TransUnion generally retains judgment information for six years in Alberta, British Columbia, Manitoba, the Northwest Territories, Nova Scotia, Nunavut, Saskatchewan, and Yukon, seven years in New Brunswick, Newfoundland and Labrador, Ontario, and Quebec, and ten years in Prince Edward Island. Equifax generally retains judgment information for six years. Paying the underlying debt does not shorten this retention period on its own, though it should ensure the entry is reflected as satisfied for as long as it remains on file.
How long does it take to resolve an old CRA judgment appearing on a credit report?
Timelines vary depending on how quickly the CRA responds and whether the matter needs to be escalated as urgent. Retrieving Federal Court records can also take time, so taxpayers facing a financing deadline should begin the process as early as possible.
Can this type of CRA judgment affect financing for a home, vehicle, or other major purchase?
Yes. Lenders and financing companies often review credit reports as part of their approval process, and an unresolved judgment, even one arising from a fully paid tax debt, can delay or complicate approval until documented proof of satisfaction is provided.
Should I hire a Canadian tax lawyer to deal with an old CRA judgment on my credit report?
An experienced Canadian tax lawyer can put the necessary CRA authorization in place, communicate directly with the CRA and its collections officers, retrieve the relevant Federal Court records, and prepare a confirmation letter if needed, which can resolve the matter more efficiently than navigating CRA and court channels alone.
DISCLAIMER:
This article provides broad information. It is only accurate as of the posting date. It has not been updated and may be out-of-date. It does not give legal advice and should not be relied on as tax advice. Every tax scenario is unique to its circumstances and will differ from the instances described in the article. If you have specific legal questions, you should seek the advice of a Canadian tax lawyer.
How a Canadian Tax Lawyer Secured $908,000 in GST/HST Relief and Full Penalty Elimination at the Tax Court of Canada
GST/HST Tax Court Appeal: Case Overview and Result
A disciplined, multi-year litigation strategy resulted in the complete elimination of gross-negligence penalties and a reduction of approximately $908,000 in disputed GST/HST amounts for a corporate taxpayer in the vehicle export business.
Spanning approximately five years — from initial retainer in January 2021 through settlement in April 2026, eight months before a scheduled Tax Court trial date in December — the result required correcting procedural deficiencies, rebuilding the evidentiary record, and maintaining persistent follow-up with the Canadian tax litigation lawyer acting for the CRA.
“Tax litigation success is rarely immediate. It requires persistence, disciplined execution, and a clear understanding of both the legal burden and the facts.”
— David J. Rotfleisch, Founding Tax Lawyer and CPA, Rotfleisch & Samulovitch P.C.
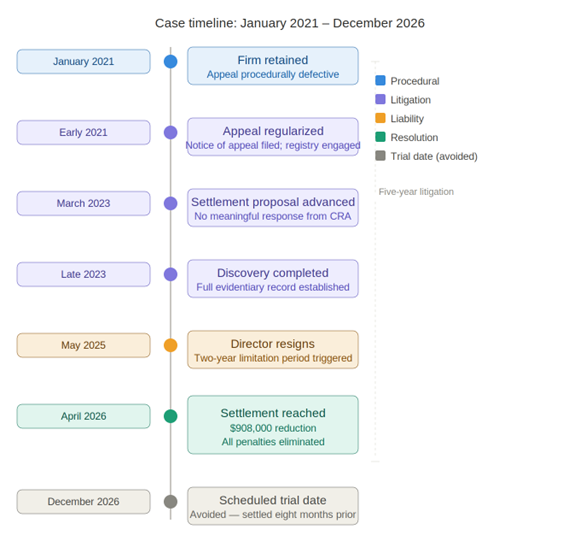
Figure 1: Key milestones from initial retainer (January 2021) through settlement (April 2026) and avoided trial date (December 2026)
CRA GST/HST Audit and Defective Tax Court Appeal: Background
The taxpayer, a corporation in the business of purchasing and exporting vehicles, became the subject of a CRA GST/HST tax audit that resulted in denied input tax credits and alleged unreported sales based primarily on a bank-deposit analysis. When Rotfleisch & Samulovitch P.C. was first retained in January 2021, the file was procedurally defective. Although an appeal had been initiated, it had not been properly perfected, and as a result the matter had not progressed to discovery or any meaningful stage of litigation. This was not a case of missed litigation deadlines; rather, the matter had never entered the litigation stream in a procedurally valid way.
The firm immediately took steps to regularize the appeal by filing a compliant notice of appeal, engaging with the Tax Court registry to ensure the appeal was properly accepted, addressing filing deficiencies and procedural gaps, and reconstructing the evidentiary foundation of the case. Only after these corrective steps could the matter proceed through document disclosure and discovery, which were completed by late 2023.
Taxpayers and advisors facing similar procedural issues should be aware that an improperly perfected appeal can jeopardize the entire case before substantive arguments are ever advanced. For a discussion of how the Tax Court appeal process works and what constitutes a properly perfected appeal, see our overview of Tax Court of Canada appeals for GST/HST disputes.
Core Legal Issues: Input Tax Credits, Bank-Deposit Analysis, and Gross-Negligence Penalties
CRA Bank-Deposit Analysis and Denied Input Tax Credits: How the Assessment Was Built
The CRA relied heavily on a bank-deposit analysis that treated various deposits as unreported revenue. The firm’s review demonstrated that many deposits were not taxable — including GST refunds and inter-account transfers. Correcting these assumptions materially reduced the CRA’s reassessment.
However, certain amounts the taxpayer claimed were loans lacked supporting documentation. There were no agreements, no repayment schedules, and no corroborating records. The strategic decision was made to concede those amounts.
“Strong advocacy requires judgment. Conceding positions that cannot be proven strengthens credibility and allows us to focus on achieving the greatest possible tax savings.”
— David J. Rotfleisch
For a broader discussion of how deposit-based assessments frequently overstate income and how taxpayers can respond, see our article on CRA tax audits and income reconstruction.
Gross-Negligence Penalties Under the Excise Tax Act: The Legal Test and CRA’s Burden of Proof
The CRA justified gross-negligence penalties by pointing to discrepancies identified in its audit, denied input tax credits, and gaps in documentation. Canadian tax law, however, sets a high bar. In Venne v. The Queen, the Federal Court held that gross negligence involves greater neglect than simply a failure to use reasonable care — it must amount to an indifference as to whether the law is complied with or not. This standard, affirmed consistently in subsequent jurisprudence, is far more demanding than ordinary negligence. Critically, the CRA bears the burden of proving that this elevated threshold has been met.
“The gross-negligence test from Venne v. The Queen requires more than careless errors or poor recordkeeping. The CRA must show conduct amounting to an indifference as to whether the law is complied with — a standard most taxpayers facing audit discrepancies will not meet when their conduct is properly examined.”
— David J. Rotfleisch, Canadian Tax Lawyer and Certified Specialist in Taxation (Law Society of Ontario)
For a discussion of gross-negligence penalties and the burden of proof in the Tax Court context, see our article on voluntary disclosures and penalty exposure.
Tax Court Litigation Strategy: How Persistent Follow-Up Eliminated GST/HST Penalties
The most decisive factor in this case was not the strength of any single legal argument but the structured, persistent follow-up that the firm maintained over several years. After the evidentiary record was substantially complete and document disclosure and discovery were finished by late 2023, the firm advanced a formal settlement proposal to the Canadian tax litigation lawyer acting for the CRA in March 2023. What followed was not a negotiation — it was silence.
The Canadian tax litigation lawyer acting for the CRA did not meaningfully respond to the settlement proposal. Weeks became months. Rather than treating the absence of a response as a closed door, the firm treated it as an open one. A disciplined follow-up protocol was implemented: each communication was timed, documented, and purpose-built to keep the file visible and to place the Canadian tax litigation lawyer acting for the CRA in the position of having to either engage or explain the failure to do so.
Each follow-up served a specific function in the litigation strategy. It kept the file active and prevented it from drifting into administrative dormancy. It required the Canadian tax litigation lawyer acting for the CRA to revisit the file and reassess the Crown’s position in light of the improved evidentiary record. It isolated gross-negligence penalties as a discrete issue — separating them from the underlying tax dispute so that the CRA’s burden on the penalty question could be examined on its own terms. And as the underlying tax amount was progressively reduced through negotiation, each follow-up highlighted the growing disconnect between a shrinking tax liability and the continued assertion of penalties that required proof of conduct amounting to indifference toward legal compliance.
As the scheduled December 2026 trial date drew closer, the pressure of each follow-up compounded. A trial date is not an abstraction — it is a deadline that forces the Canadian tax litigation lawyer acting for the CRA to make a binary choice: settle or go to court and defend a penalty position that had become increasingly difficult to justify. The evidentiary record had improved. The underlying tax had been reduced. The burden remained on the CRA. And every follow-up had required a principled explanation for why penalties should survive in those circumstances.
After multiple rounds of persistent follow-up, the Canadian tax litigation lawyer acting for the CRA ultimately agreed to eliminate the gross-negligence penalties entirely. The settlement was reached in April 2026, eight months before the December trial date.
“This result was not achieved in a single step. It required sustained follow-up and disciplined pressure over time until the position became untenable.”
— David J. Rotfleisch
Implications for Canadian Taxpayers Facing CRA GST/HST Reassessments
This case has several implications for taxpayers and advisors dealing with CRA GST/HST reassessments and Tax Court litigation.
The first is procedural: an appeal that has not been properly perfected provides no protection. Taxpayers who receive a notice of reassessment and wish to challenge it must file a compliant notice of objection, and — if the objection is unsuccessful — a properly structured notice of appeal with the Tax Court of Canada. Procedural deficiencies at the appeal stage can cause years of delay and may jeopardize the taxpayer’s substantive rights entirely.
The second is evidentiary: CRA bank-deposit analyses are routinely used in GST/HST audits and frequently overstate taxable revenue by including non-taxable receipts such as refunds, inter-account transfers, and genuine loan proceeds. A careful forensic review of the deposit analysis is essential, but that review must be supported by documentation. Where records are absent, strategic concessions may be necessary to maintain credibility on the issues that can be defended.
The third is the penalty burden: gross-negligence penalties under the Excise Tax Act represent an additional financial exposure that can reach 25 percent of the net tax owing. The CRA cannot impose these penalties simply because a reassessment reveals discrepancies. Under Venne v. The Queen, the CRA must prove conduct amounting to an indifference as to whether the law is complied with — a standard that most audit discrepancies, even serious ones, will not satisfy. A well-prepared penalty defence is often the most consequential aspect of the litigation.
Finally, director liability adds a personal dimension to corporate GST/HST disputes. Resigned directors benefit from a two-year limitation period under the Excise Tax Act. Timing a resignation strategically — while the underlying corporate dispute remains active — can significantly reduce personal exposure. For more on this topic, see our article on director liability for corporate tax debts.
Key Takeaways: How to Defend Against CRA GST/HST Reassessments and Gross-Negligence Penalty Appeals
The outcome of this case — a $908,000 reduction in disputed GST/HST amounts and the complete elimination of gross-negligence penalties — reflects several principles that should inform how taxpayers approach CRA reassessments and Tax Court litigation.
Properly perfecting an appeal from the outset is not optional; it is a prerequisite to meaningful advocacy. Input tax credit claims must be supported by documentation, and where they are not, targeted concessions protect credibility on the issues that matter. Bank-deposit analyses should be subjected to rigorous forensic review, with particular attention to non-taxable receipts that inflate the CRA’s position.
On the penalty question, the law is clear: the CRA must prove conduct amounting to indifference as to whether the law is complied with under Venne v. The Queen, and most audit discrepancies do not satisfy that standard. Sustained, structured follow-up over the life of the file — including disciplined persistence in the face of prolonged non-response from the Canadian tax litigation lawyer acting for the CRA — played a decisive role in driving the concession of the penalty issue entirely, eight months before the scheduled trial date.
“A taxpayer’s result is not determined at the audit stage. It is determined by how effectively the case is advanced afterward.”
— David J. Rotfleisch

Figure 2: CRA’s original position versus final settlement — $908,000 tax reduction and full elimination of gross-negligence penalties
Pro Tax Tips: GST/HST Audit Defence and Tax Court Appeals in Canada
Taxpayers facing a CRA GST/HST tax reassessment should ensure that any appeal is filed in proper form and perfected without delay, as procedural deficiencies can foreclose substantive arguments entirely. Input tax credit claims should be supported by clear documentation at the time of filing, and bank-deposit analyses received from the CRA should be reviewed carefully for non-taxable amounts. Where certain positions cannot be substantiated, a targeted strategic concession is preferable to overextending the case.
On the penalty question, taxpayers should understand that gross-negligence penalties require the CRA to prove conduct amounting to an indifference as to whether the law is complied with — the standard from Venne v. The Queen — a threshold the CRA frequently cannot meet when the underlying facts are properly analyzed and presented. Persistent, structured follow-up in the face of extended non-response from the Canadian tax litigation lawyer acting for the CRA can be the single most important factor in achieving a favourable settlement well before a scheduled trial date.
Director-shareholders should assess their potential personal liability for corporate GST/HST debts and consider the timing of any resignation relative to the two-year limitation period under the Excise Tax Act.
Frequently Asked Questions: CRA GST/HST Audits, Tax Court Appeals, and Gross-Negligence Penalties
What was the central procedural problem when the firm was first retained?
When Rotfleisch & Samulovitch P.C. was retained in January 2021, the taxpayer had initiated an appeal but had not properly perfected it. This meant the matter had not entered the litigation stream in a procedurally valid way and had not progressed to disclosure or discovery. The firm’s first task was to regularize the appeal, file a compliant notice of appeal, and address the procedural gaps before any substantive work could proceed. Taxpayers should never assume that filing a notice of objection alone is sufficient; a properly structured Tax Court appeal is a separate and mandatory step.
Did prior counsel miss any Tax Court deadlines?
No. The issue was not that deadlines had passed but that the appeal had not been perfected in compliance with Tax Court procedural requirements. The matter simply had not reached the litigation stage. This is a distinction that matters: a missed deadline can be fatal to an appeal, whereas a procedural deficiency that has not yet caused prejudice can often be corrected if addressed promptly.
What is the legal test for gross-negligence penalties under the Excise Tax Act?
The leading authority is Venne v. The Queen, in which the Federal Court held that gross negligence involves greater neglect than simply a failure to use reasonable care — it must amount to an indifference as to whether the law is complied with or not. This is a significantly higher threshold than ordinary negligence or careless recordkeeping. Audit discrepancies, denied ITCs, and incomplete documentation do not automatically satisfy it. The conduct must reflect a degree of wilful blindness or indifference toward legal compliance that goes well beyond inadvertent error.
Who bears the burden of proving gross-negligence penalties?
The CRA bears the burden of proving on a balance of probabilities that the taxpayer’s conduct meets the gross-negligence threshold. This is significant because it reverses the usual dynamic in tax litigation, where the taxpayer must generally disprove the facts underlying a reassessment. On the penalty question, the CRA must bring forward the evidence and make the case; the taxpayer need only undermine it.
How much was the GST/HST liability reduced?
The disputed amounts were reduced by approximately $908,000. In addition, all gross-negligence penalties were eliminated. Because gross-negligence penalties under the Excise Tax Act can reach 25 percent of the net tax owing, their removal produced substantial additional savings on top of the underlying tax reduction.
Why did the firm concede certain amounts relating to alleged loans?
Several amounts that the taxpayer characterized as loans lacked any supporting documentation — no loan agreements, no repayment schedules, and no corroborating financial records. Advancing a position that cannot be substantiated at trial damages credibility on every other issue in the case. The strategic decision to concede those amounts allowed the firm to focus on the positions that were defensible and to present a credible overall record to the CRA and the Court.
How do CRA bank-deposit analyses work, and why are they often inaccurate?
In a bank-deposit audit, the CRA reconstructs income by treating all deposits into the taxpayer’s accounts as revenue, then subtracting amounts the taxpayer can prove are non-taxable. This method is inherently blunt. It routinely captures GST refunds, inter-account transfers, genuine loan proceeds, shareholder contributions, and other non-taxable receipts. Challenging a deposit analysis requires a forensic review of every transaction, supported by bank records and corroborating documentation, to identify and isolate non-taxable items. In this case, that review materially reduced the CRA’s position.
What role did the Canadian tax litigation lawyer acting for the CRA’s failure to respond play in the outcome?
After the firm advanced a settlement proposal in March 2023, the Canadian tax litigation lawyer acting for the CRA did not meaningfully respond for an extended period. Rather than treating this as a barrier, the firm implemented a structured follow-up strategy that kept the file active, required the Canadian tax litigation lawyer acting for the CRA to revisit the file repeatedly, and placed the penalty issue under sustained scrutiny. The prolonged non-response ultimately made the penalty position harder to maintain — each follow-up required a principled justification for penalties that the evidentiary record was making progressively more difficult to sustain. The settlement was ultimately reached in April 2026, eight months before the December trial date.
What role did the director’s resignation play in the outcome?
The director of the corporate taxpayer resigned in May 2025, triggering the two-year limitation period under section 323 of the Excise Tax Act. Under that provision, a director who has resigned more than two years before the CRA commences an assessment of the director personally cannot be held liable for the corporation’s unremitted net tax. Timing the resignation to align with the ongoing litigation significantly reduced potential personal exposure while settlement discussions continued. Directors of corporations facing GST/HST reassessments should assess this timing carefully with counsel.
How long do complex GST/HST disputes at the Tax Court typically take?
Complex GST/HST matters routinely take several years from initial reassessment to final resolution. This case spanned approximately five years from retainer to settlement. That timeline reflects the time required to correct procedural deficiencies, rebuild the evidentiary record, complete disclosure and discovery, advance a settlement proposal, and sustain the follow-up necessary to bring the Canadian tax litigation lawyer acting for the CRA to a final position. Taxpayers should approach Tax Court litigation with realistic expectations about duration and the sustained commitment it requires.
Can gross-negligence penalties be removed without going to trial?
Yes. In this case, the penalties were eliminated through negotiation and sustained advocacy rather than a judicial ruling. A well-developed evidentiary record and persistent follow-up that forced the Canadian tax litigation lawyer acting for the CRA to reassess the penalty position were central to achieving that result. As the underlying tax exposure diminished and the December trial date approached, the ability to justify the penalty position under the demanding standard in Venne v. The Queen became increasingly difficult to maintain. Settlement was reached in April 2026.
What is the most important practical lesson from this case?
The outcome illustrates that the result of a CRA tax audit is not fixed at the audit stage. Effective advocacy — including procedural correction, rigorous evidentiary development, strategic concessions, and above all sustained and structured follow-up in the face of non-response from the Canadian tax litigation lawyer acting for the CRA — can materially change the outcome even in a complex, multi-year dispute. Persistence, combined with a clear understanding of the legal standard the CRA must meet on the penalty question, can produce results that the audit outcome alone would not have suggested.
Disclaimer
This article provides broad information. It is only accurate as of the posting date. It has not been updated and may be out of date. It does not give legal advice and should not be relied on as tax advice. Every tax scenario is unique. If you have specific legal questions, you should seek advice from a Canadian tax lawyer.
How Rotfleisch & Samulovitch Professional Corporation Proactively Manages CRA Objections
This case study demonstrates how Rotfleisch & Samulovitch Professional Corporation proactively manages CRA objections from the outset to protect procedural fairness, preserve evidentiary integrity, and secure defensible outcomes in complex tax disputes. All identifying details have been anonymized.
Overview: Managing Process Risk in a CRA Objection
From the inception of the objection, our firm did not simply prepare submissions—we actively managed the process itself. Where communication breakdowns, procedural irregularities, and conduct concerns arose, we intervened decisively through structured escalation and disciplined file strategy. This ultimately resulted in the reassignment of the Appeals Officer and a reset of the objection under conditions that better respected fairness and due process.
“Process control is often the decisive factor in tax disputes. When the process begins to deteriorate, experienced counsel must step in early and assertively to correct it,” says David Rotfleisch, Certified Specialist in Taxation.
Managing a Complex Objection Involving Over 1,000 Pages of Evidence
From the outset, this was a document-intensive objection involving more than 1,000 pages of supporting evidence. Our firm maintained carriage of the file from inception, allowing us to build the evidentiary record strategically and with foresight.
The Appeals Officer imposed an unusually granular requirement: every document had to be reorganized and cross-referenced on a line-by-line basis to each individual expense claim. This effectively required reconstruction of the entire evidentiary record into a tightly indexed analytical framework.
While this level of detail is not typical, we complied fully. A comprehensive submission was delivered in late April 2026. A second, significantly refined submission followed in May 2026, incorporating additional documentation, improved alignment, and further analytical clarity.
Critically, the second submission was prepared in collaboration with the client’s accountant, who was formally retained through our firm. This was not incidental—it was a deliberate legal strategy designed to preserve solicitor-client privilege over the accountant’s work.
In Canadian tax matters, this distinction is essential. Without proper structuring, communications and working papers prepared by accountants are not privileged and may be subject to compulsory disclosure or seizure by the CRA. By retaining the accountant through legal counsel, we ensured that the accountant’s work formed part of the legal advisory process, thereby strengthening privilege protections and allowing controlled disclosure.
“Retaining accountants through legal counsel is not just a technical choice—it is a fundamental safeguard that protects the integrity of the client’s position,” says David Rotfleisch, Certified Specialist in Taxation.
For further discussion on this issue, see: When Is an Accountant’s Work Privileged in Canada?
Procedural Breakdown: Communication Failures and Risk of Evidentiary Disregard
Despite complete compliance with the Appeals Officer’s evidentiary requirements, serious concerns began to emerge.
Immediately following the May submission, the Appeals Officer indicated—without reviewing the newly submitted record—that any perceived lack of clarity would result in reverting to the earlier evidentiary set. This raised a fundamental procedural fairness issue: over 1,000 pages of relevant, structured, and responsive evidence were at risk of being disregarded without meaningful consideration.
This is not merely a practical issue—it is a legal one. Administrative decision-makers, including CRA Appeals Officers, are required to consider all relevant evidence before rendering a decision. Any indication that evidence may be ignored undermines the legitimacy of the process and increases the likelihood of an improper tax reassessment.
In parallel, the Appeals Officer raised concerns about the involvement of the accountant in preparing the submission. In a file of this scale and complexity, such collaboration is not only appropriate—it is often indispensable.
Resistance to this structure was both unreasonable and inconsistent with taxpayer protections, including rights recognized in the Taxpayer Bill of Rights such as the right to representation of choice and the right to professional and fair treatment.
For a detailed discussion of taxpayer rights in CRA disputes, see: Taxpayer Bill of Rights — Canada
For broader context on the objections process, see: CRA Objections Process — Canada
Strategic Escalation: Timeline, Resistance, and Outcome
Recognizing that the process itself was at risk, our firm implemented a controlled escalation strategy.
A formal service complaint was filed on May 23, 2026. This was not a reactive step but a strategic one, supported by detailed documentation of communication failures and procedural concerns.
Between June 4 and June 5, we undertook sustained escalation efforts. These included multiple attempts to reach supervisory personnel through CRA channels. Initial efforts were met with resistance, including refusal to provide escalation contacts and inconsistent responses across departments.
Rather than accept delay, we persisted.
By June 5, escalation had been formally initiated through CRA internal mechanisms. A supervisory callback request was recorded.
On June 9, a team leader returned the call, acknowledged the issues, and confirmed internal review. Crucially, later that same day, approval was granted to reassign the file to a new Appeals Officer.
By June 10, we were in direct contact with the newly assigned officer.
In practical terms, this meant that within approximately 17 days of initiating the complaint—and within approximately 5 days of focused escalation—the objection process was reset.
“Effective advocacy in CRA disputes requires not just raising concerns, but driving them to resolution quickly and persistently,” says David Rotfleisch, Certified Specialist in Taxation.
For further insights on escalation strategies, see: Resolving CRA Tax Disputes
Legal Framework: Procedural Fairness and the R v Jarvis Boundary
Although this matter did not involve criminal exposure, the principles articulated in R v Jarvis, 2002 SCC 73 remain relevant in defining the limits of CRA conduct.
The Supreme Court of Canada emphasized that the CRA must operate within defined boundaries and cannot blur the line between administrative review and enforcement powers. The foundational authority for the procedural fairness obligation on administrative decision-makers, however, is Baker v Canada (Minister of Citizenship and Immigration), [1999] 2 SCR 817, which confirmed that decision-makers exercising statutory powers must act fairly, consider all relevant evidence, and provide meaningful engagement with the materials before them — obligations that apply with full force to CRA Appeals Officers. More broadly, Jarvis reinforces the principle that fairness and procedural integrity are essential to the legitimacy of CRA actions.
For further discussion: CRA Audit Powers and the Jarvis Case | CRA Cryptocurrency Tax Audit
Why This Matters: Process Failures Can Override Strong Evidence
One of the most important takeaways from this case is that strong evidence alone is not sufficient.
In large-scale objections, particularly those involving extensive documentation, the risk is not simply that the CRA will disagree—it is that the process itself will fail. Evidence may be misunderstood, partially reviewed, or improperly disregarded.
Without proactive legal management, these risks can materially affect outcomes.
At Rotfleisch & Samulovitch Professional Corporation, we do not assume that the process will operate correctly—we actively ensure that it does.
Takeaway: Controlling the Process Is a Strategic Advantage
The reassignment achieved in this case was not incidental—it was the result of early issue identification, disciplined documentation, and persistent escalation.
“Where the evidentiary record is strong, success depends on ensuring the decision-maker actually engages with that record. That requires proactive and strategic intervention,” says David Rotfleisch, Certified Specialist in Taxation.
Pro Tax Tips for Complex CRA Objections
Large and document-intensive CRA objections require more than technical compliance — they require continuous oversight of how the CRA engages with the file. Taxpayers should ensure that evidence is not only complete and well-organized but also presented in a way that compels review. Retaining accountants through legal counsel protects sensitive analysis and ensures that the legal team maintains control over disclosure. Where communication or procedural issues arise, escalation should be immediate, structured, and persistent. An experienced Canadian tax litigation lawyer will recognize early warning signs and act decisively to protect process integrity before it affects the outcome.
Frequently Asked Questions: CRA Objections, Procedural Fairness, and Escalation
What is the advantage of retaining an accountant through legal counsel?
Retaining an accountant through legal counsel allows the accountant to function as an agent assisting in the provision of legal advice, which can extend solicitor-client privilege to their communications and work product. This structure allows complex financial analysis to be conducted within a protected legal framework. Failure to adopt this structure carries significant risk: Canadian law does not recognize general accountant-client privilege, meaning the CRA can compel production or seize an accountant’s working papers during a tax audit or objection review. Once disclosed, those materials may be used by the CRA to reinterpret transactions, challenge positions, or expand the scope of its review. See: When Is an Accountant’s Work Privileged in Canada?
How quickly can a CRA service complaint lead to meaningful results?
Although CRA processes are often perceived as slow, properly executed escalation can produce results quickly. In this case, reassignment occurred within approximately 17 days. The key factor was not timing alone, but persistence, documentation, and strategic pressure.
What makes a large evidentiary record risky in a CRA objection?
A large evidentiary record increases the risk of incomplete or selective review. Without careful structuring and active oversight, important materials may be overlooked or misunderstood, particularly where the decision-maker is under time pressure. A knowledgeable Canadian tax litigation lawyer will structure and present the record in a way that compels thorough engagement.
Can the CRA impose detailed evidentiary formatting requirements?
Yes, the CRA can request structured presentation of evidence. However, such requests must remain reasonable. Where a taxpayer complies with detailed requirements, the CRA assumes a corresponding obligation to conduct a meaningful and complete review.
What should be done if an Appeals Officer suggests evidence may not be considered?
This is a clear procedural fairness concern. It should be documented immediately and escalated through both formal service complaints and supervisory engagement. Under Baker v Canada (Minister of Citizenship and Immigration), [1999] 2 SCR 817, administrative decision-makers are required to meaningfully engage with the evidence before them. Any indication to the contrary should be treated as a serious procedural deficiency.
Do taxpayers have the right to coordinate legal and accounting professionals?
Yes. Taxpayers have the right to retain advisors of their choice. In complex disputes, coordination between legal and accounting professionals is essential and should not be resisted by the CRA.
What are the risks of not protecting accountant communications?
Without privilege protection, accountant working papers may be compelled or seized. This can expose internal strategy, draft analyses, and assumptions never intended to form part of the evidentiary record, significantly weakening the taxpayer’s position.
What are early warning signs of a problematic CRA objections process?
Key indicators include communication breakdowns, shifting evidentiary demands, resistance to professional collaboration, and any suggestion that evidence may not be fully reviewed. An experienced Canadian tax lawyer will identify these signs early and act before they cause irreversible harm to the file.
Why is proactive legal oversight critical in a CRA objection?
CRA disputes are not only about law — they are about process. Process failures often determine outcomes. Active management ensures that fairness is preserved and that strong evidence is actually considered by the decision-maker.
Additional Resources to Strengthen Your Position
CRA Objections Process — Canada
Taxpayer Bill of Rights — Canada
CRA Audit Powers and the Jarvis Case
Short-Term Rental Tax Deductions
How to Survive a CRA Tax Audit
| If You Are Facing a CRA Objection
If you are involved in a CRA objection involving significant documentation, complex accounting issues, or procedural concerns, early intervention can materially change the outcome. Ensuring that your evidence is properly structured and that the process itself remains fair is critical. FREE 10-minute consultation with a student (Canada only) |
Disclaimer: This article provides broad information. It is only accurate as of the posting date. It has not been updated and may be out of date. It does not give legal advice and should not be relied on as tax advice. Every tax scenario is unique to its circumstances and will differ from the instances described in this article. If you have specific legal questions, you should seek the advice of a Canadian tax lawyer.
CRA Tax Audit, CRA Net Worth Assessment, and Tax Court of Canada Appeal Overview
A CRA tax audit can be stressful under any circumstances. The situation becomes even more challenging when a taxpayer has suffered a serious injury, faces a substantial tax reassessment based on a CRA net worth audit, and discovers that important procedural opportunities were missed during the early stages of a tax dispute.
This was the situation facing Mr. Pat Pizza (name withheld due to solicitor-client confidentiality). Before retaining TaxPage, Mr. Pizza had engaged another Canadian tax lawyer and accountant to deal with a CRA tax audit and subsequent Tax Court of Canada appeal involving his corporation. By the time TaxPage became involved, significant challenges had already arisen, including deficiencies in the pleadings, unanswered Requests to Admit that resulted in deemed admissions, and the failure to conduct discoveries relating to the CRA’s evidence.
TaxPage’s experienced Canadian tax lawyers were subsequently retained to address both the substantive tax issues and the procedural deficiencies that had arisen during the earlier stages of the dispute.
Despite these challenges, TaxPage successfully developed and implemented a strategy that ultimately reduced the corporation’s reassessed income from approximately $727,000 to approximately $310,000, eliminated more than $66,000 in gross negligence penalties, and generated overall tax and interest savings estimated at approximately $330,000. The matter was resolved without proceeding to a full Tax Court trial.
This case demonstrates the importance of retaining an experienced Canadian tax litigation lawyer when dealing with a CRA tax audit, CRA net worth assessment, gross negligence penalties, or a Tax Court of Canada appeal.
TaxPage’s approach in this matter reflects established Canadian tax litigation principles routinely applied in complex CRA tax audit and Tax Court of Canada appeal disputes, particularly where CRA net worth audit methodologies are challenged using contemporaneous transactional records and forensic accounting reconstruction.
CRA Net Worth Audit Lawyer Canada – TaxPage Representation in Complex CRA Tax Audit Disputes
TaxPage provides representation for taxpayers facing CRA net worth audits, CRA tax reassessments, and Tax Court of Canada appeals across Canada. These disputes often involve indirect income reconstruction, gross negligence penalties, and complex evidentiary challenges requiring experienced Canadian tax litigation counsel.
Our experience includes defending cash-intensive businesses such as restaurants, franchises, and owner-operated corporations where CRA audit methodologies rely heavily on assumptions rather than direct transactional verification.
What Does a CRA Net Worth Audit Lawyer in Canada Do?
A CRA net worth audit lawyer in Canada assists taxpayers in challenging CRA reassessments that are based on indirect income estimation methods rather than direct accounting records. These cases typically involve reviewing CRA assumptions, reconstructing financial data, challenging gross negligence penalties, and representing taxpayers in Tax Court of Canada appeals. Effective defence strategies often rely on forensic review of banking records, accounting systems, and point-of-sale data to demonstrate inconsistencies in the CRA’s reconstruction methodology.
CRA Tax Audit and CRA Tax Reassessment Background Facts
Mr. Pat Pizza owned and operated a pizza franchise through a corporation (“Pizza Corp”).
Following a CRA tax audit of Pizza Corp’s operations for the 2013 through 2015 taxation years, the CRA reassessed the corporation using a CRA net worth audit methodology. The CRA concluded that Pizza Corp had substantially underreported income and increased the corporation’s taxable income by approximately $727,000.
CRA tax audit determinations frequently rely on indirect assumptions rather than direct transactional verification, making contemporaneous financial records, POS data, and banking records critical in assessing the reliability of a CRA tax reassessment.
In addition to increasing income, the CRA disallowed various business expenses and assessed gross negligence penalties. The combined effect of the reassessments created significant financial exposure for both Pizza Corp and Mr. Pizza.
Unfortunately, the substantive tax issues were only part of the problem.
When TaxPage reviewed the file, it became apparent that several procedural opportunities had already been missed and that significant work would be required simply to place the taxpayer in the best possible position to challenge the reassessments.
CRA Tax Reassessment Based on a CRA Net Worth Audit
The CRA’s reassessment was based primarily on a net worth analysis that alleged substantial unreported income. Because net worth audits depend heavily upon assumptions regarding assets, liabilities, expenditures, and available sources of funds, a detailed review of the CRA’s methodology became essential to the taxpayer’s defence.
Procedural Challenges in the CRA Tax Audit and Tax Court of Canada Appeal Identified by TaxPage’s Experienced Canadian Tax Lawyers
One of the first steps undertaken by TaxPage was a comprehensive review of the existing litigation file.
That review revealed several significant procedural deficiencies requiring immediate attention. Before TaxPage became involved, key litigation steps had either not been completed or had been handled in a manner that exposed the taxpayer to unnecessary risk.
Deficiencies in the Notice of Appeal in the Tax Court of Canada Appeal
The original Notice of Appeal did not fully articulate the factual and legal basis upon which the reassessments were being challenged. TaxPage determined that amendments were necessary to ensure that the relevant facts, issues, and legal arguments were properly before the Tax Court of Canada.
Request to Admit Issues Affecting the CRA Tax Reassessment Appeal
A Request to Admit served by counsel representing the CRA had not been answered. As a result, certain facts became deemed admissions under the Tax Court of Canada Rules. Depending upon their nature, deemed admissions can significantly restrict a taxpayer’s ability to challenge aspects of the CRA’s position and may materially affect the outcome of a case.
Discovery Deficiencies in the CRA Tax Audit Litigation Process
Discoveries concerning the CRA’s assumptions, calculations, and supporting evidence had not previously been conducted. As a result, important assumptions underlying the reassessments had not yet been fully examined or challenged.
TaxPage immediately undertook a detailed review of the file, prepared an Amended Notice of Appeal, and developed a strategy designed both to challenge the CRA reassessments and to address the procedural issues inherited from earlier stages of the dispute.
This aspect of the case serves as an important reminder that retaining an experienced Canadian tax appeal lawyer at the earliest possible stage of a CRA tax audit or Tax Court appeal can often prevent costly procedural complications from arising in the first place.
Challenging the CRA Net Worth Audit Methodology and CRA Net Worth Assessment
A central issue in this appeal was the CRA’s reliance on a net worth audit.
CRA net worth audits frequently result in significant tax reassessments because the CRA reconstructs a taxpayer’s income using indirect methods rather than relying solely on the taxpayer’s books and records.
TaxPage has written extensively about CRA net worth audits and income tax gross negligence penalties. Readers interested in CRA tax audit defence strategies, CRA net worth audit methodology, and Tax Court of Canada appeal procedures may find these resources helpful in understanding how indirect income reconstruction is challenged in litigation.
This type of CRA tax audit determination often depends heavily on indirect assumptions rather than direct transactional evidence, making the quality and completeness of contemporaneous financial records critical in evaluating the accuracy of the CRA tax reassessment.
What Is a CRA Net Worth Audit?
A CRA net worth audit is an indirect audit method used when CRA auditors believe that a taxpayer’s books and records do not accurately reflect income. Instead of relying solely on reported revenues and expenses, the CRA attempts to estimate income by examining increases in assets and comparing those increases to reported income.
The CRA may also consider personal expenditures, liabilities, banking records, and information obtained from third parties.
Common Problems with CRA Net Worth Assessments
Although CRA net worth audits are commonly used by the CRA, they are often challenged because relatively small errors in opening balances, asset valuations, personal expenditures, shareholder loan accounts, or non-taxable sources of funds can produce significant distortions in the resulting calculations.
In many cases, taxpayers assume that the CRA’s calculations are based on direct evidence of unreported income. In reality, a net worth assessment often depends upon a chain of assumptions. If one or more assumptions are incorrect, the resulting reassessment may be significantly overstated.
Small errors in a net worth assessment can produce surprisingly large reassessments, particularly where the CRA’s assumptions are compounded over multiple taxation years. As a result, taxpayers should carefully review the assumptions underlying any CRA net worth audit and obtain advice from an experienced Canadian tax litigation lawyer as early as possible.
TaxPage’s Review of the CRA Net Worth Assessment
As part of its review, TaxPage carefully analyzed the assumptions underlying the CRA’s net worth assessment and identified several areas requiring further examination, including:
- The treatment of personal expenditures;
- The calculation of opening and closing net worth;
- The inclusion of certain assets and liabilities;
- The treatment of shareholder loan accounts;
- The treatment of non-taxable sources of funds; and
- The overall methodology used to estimate income.
TaxPage developed a counter-net-worth analysis to challenge the accuracy of the CRA’s assumptions and conclusions.
According to David J. Rotfleisch:
“Net worth audits remain one of the CRA’s most powerful audit tools, but they are far from infallible. Taxpayers should never assume that a net worth assessment is accurate simply because it was prepared by the CRA. Every assumption must be tested against the available evidence.”
As David J. Rotfleisch has also observed:
“A successful tax appeal often begins by identifying what the CRA assumed rather than what the CRA proved. In many reassessment cases, that distinction becomes critically important.”
The detailed review of the CRA’s assumptions provided the foundation for the litigation strategy that followed. The next stage of the appeal focused on gathering evidence, conducting discoveries, challenging the CRA’s calculations, and positioning the matter for a favourable resolution.
Evidence Gathering and Discovery in the CRA Tax Audit and Tax Court of Canada Appeal
Following the procedural remediation and initial review of the CRA tax reassessment, TaxPage focused on building a robust evidentiary foundation for the Tax Court of Canada appeal.
A successful challenge to a CRA net worth assessment depends heavily on documentary evidence capable of rebutting the assumptions used by the CRA. Unlike traditional audits, a CRA net worth audit relies on indirect reconstruction of income, meaning that the taxpayer must often reconstruct financial reality with precision and consistency to effectively challenge the CRA’s position.
TaxPage worked closely with Mr. Pat Pizza and supporting professionals to gather, reconcile, and organize the relevant financial records. This included corporate tax filings, banking records, point-of-sale reports, internal accounting records, and supporting documentation for both personal and corporate expenditures.
The objective was to establish a coherent evidentiary narrative that directly addressed the assumptions underlying the CRA tax reassessment and strengthened the taxpayer’s position in the Tax Court of Canada appeal.
Discovery Strategy in the CRA Tax Audit Litigation Process
Discovery played a central role in advancing the litigation strategy.
Given Mr. Pizza’s prior head injury and resulting cognitive limitations affecting memory recall, TaxPage adopted a tailored discovery approach to ensure accuracy, reliability, and fairness in the evidentiary record.
Instead of proceeding exclusively through oral examinations, TaxPage negotiated a structured written discovery process. This approach allowed the taxpayer to carefully review documentation before responding, reducing the risk of inconsistency while preserving procedural fairness.
At the same time, TaxPage conducted a comprehensive analysis of the CRA’s assumptions and evidentiary record. This included a detailed review of the calculations underpinning the CRA net worth assessment and identification of gaps in the evidentiary foundation relied upon by the CRA.
According to David J. Rotfleisch:
“Discovery in tax litigation is often where the true strength or weakness of a reassessment becomes visible. What is assumed during audit must withstand scrutiny when tested against the evidentiary record.”
TaxPage’s approach reflects established Canadian tax litigation standards applied in complex CRA tax audit and Tax Court of Canada appeal matters involving indirect income reconstruction.
CRA Tax Reassessment Settlement Negotiations Conducted by TaxPage’s Experienced Canadian Tax Lawyers
As the Tax Court of Canada appeal progressed, settlement discussions were initiated with counsel representing the CRA.
CRA Tax Audit Defence Strategy and Evidentiary Leverage in a CRA Net Worth Audit Appeal
Following review of the evidentiary record, the Canadian tax litigation lawyer acting for the CRA advanced an initial settlement proposal. While the proposal included partial concessions on income adjustments, it maintained the gross negligence penalties and did not adequately address key deficiencies identified in the CRA net worth assessment.
As the evidentiary record developed, the CRA’s settlement position evolved in response to increasing disclosure of franchisor-controlled POS data, banking reconciliation evidence, and consistent accounting records that materially reduced the reliability of the net worth reconstruction model.
Strategic Response to the CRA Tax Reassessment and Gross Negligence Penalties
TaxPage developed a structured counterproposal grounded in the evidentiary record and the legal standards governing CRA net worth audits and penalty assessments.
A key focus was the reliability of the assumptions underlying the CRA net worth assessment, particularly with respect to opening balances, personal expenditures, and classification of funds.
TaxPage also challenged the imposition of gross negligence penalties. As set out in TaxPage’s analysis of gross negligence penalties, the CRA must establish more than mere error or discrepancy; it must demonstrate the requisite level of carelessness or wilful conduct required by law.
Where certain documentation gaps existed, TaxPage adopted a targeted litigation strategy that prioritized the strongest evidentiary positions while maintaining credibility in settlement negotiations.
This approach significantly improved the taxpayer’s negotiating position and facilitated continued discussions with the CRA litigation counsel.
CRA Tax Reassessment, Gross Negligence Penalty, and Tax Liability Resolution
After sustained negotiations and continued advancement of the Tax Court of Canada appeal, the Canadian tax litigation lawyer acting for the CRA ultimately accepted the settlement terms advanced by TaxPage.
The resolution represented a substantial success for both Mr. Pizza and Pizza Corp.
The CRA agreed to reduce the reassessed income from approximately $727,000 to approximately $310,000.
The CRA further agreed to vacate gross negligence penalties exceeding $66,000 in their entirety.
Readers may also wish to review TaxPage’s detailed discussion of CRA objection procedures in relation to tax reassessments:
https://taxpage.com/articles-and-tips/notice-of-objection/
and Tax Court appeal processes:
https://taxpage.com/tax-appeals/
When interest savings were included, the total financial benefit was estimated at approximately $330,000.
Resolution of the CRA Tax Audit and Tax Court of Canada Appeal
By April 2026, the settlement was fully implemented and reflected in the taxpayer’s CRA account.
The Tax Court of Canada appeal concluded without the need for a full trial, demonstrating the effectiveness of early evidentiary reconstruction, targeted litigation strategy, and disciplined settlement negotiation.
According to David J. Rotfleisch:
“Effective tax litigation is rarely about a single argument. It is about building a consistent evidentiary and legal position that the CRA cannot sustain when fully tested.”
Reopening Personal CRA Tax Reassessments Through Strategic Tax Objection Planning
During the course of the corporate tax litigation, TaxPage identified additional personal tax reassessments issued against Mr. Pizza, exceeding $400,000.
These reassessments had become procedurally challenging due to missed objection deadlines arising prior to TaxPage’s involvement.
Strategic CRA Tax Objection Approach and T1 Adjustment Requests
After detailed review, TaxPage implemented a procedural strategy involving T1 adjustment requests designed to trigger fresh CRA reassessments.
This approach resulted in the issuance of new reassessments by the CRA.
Upon issuance, TaxPage immediately filed Notices of Objection challenging the reassessments in full, including associated gross negligence penalties.
Readers interested in the objection process may wish to review TaxPage’s article on the Notice of Objection process and Tax Appeals.
Preserving Taxpayer Rights in CRA Tax Reassessment Disputes
This portion of the case illustrates that procedural constraints do not always represent the end of a taxpayer’s rights.
In appropriate circumstances, procedural mechanisms may exist to reopen or reframe disputes, particularly where reassessments are reissued or materially altered by the CRA.
For Mr. Pizza, this strategy preserved the ability to challenge over $400,000 in personal tax exposure that might otherwise have remained unreviewable.
According to David J. Rotfleisch:
“Tax litigation is not only about substantive tax law. It is equally about procedural timing, strategy, and understanding how to lawfully reposition a file when conventional remedies appear closed.”
Lessons Learned from a CRA Tax Audit, CRA Net Worth Assessment, and Tax Court of Canada Appeal
This case provides several important lessons for taxpayers facing a CRA tax audit, CRA net worth assessment, gross negligence penalties, or a Tax Court of Canada appeal.
CRA Tax Audit Outcomes Depend on Evidence, Not Assumptions
A key takeaway from this matter is that CRA tax audit results are heavily dependent on the quality and structure of evidence presented. Where taxpayers can demonstrate consistent, verifiable financial records, the CRA’s ability to rely on indirect assumptions is significantly reduced.
This case illustrates that contemporaneous transactional records—particularly POS data, banking deposits, and accounting records—can materially alter the outcome of a CRA net worth assessment.
Procedural Issues in a Tax Court of Canada Appeal Can Materially Affect Risk
This matter also demonstrates that procedural missteps at the early stages of litigation can significantly increase risk exposure.
Issues such as deficient pleadings, unanswered Requests to Admit, and incomplete discoveries can constrain a taxpayer’s ability to fully challenge a CRA tax reassessment.
Retaining an experienced Canadian tax lawyer or Canadian tax appeal lawyer at an early stage can help ensure that procedural rights are preserved throughout the Tax Court of Canada appeal process.
CRA Net Worth Assessments Are Highly Sensitive to Assumptions
CRA net worth audits are inherently assumption-driven. As a result, they are particularly vulnerable to challenge where taxpayers can demonstrate inconsistencies in:
- opening balances
- asset valuations
- personal expenditure assumptions
- shareholder loan account treatment
- non-taxable source identification
Even relatively small adjustments to these assumptions can produce significant changes in assessed income.
Gross Negligence Penalties Require a High Legal Threshold
This case further confirms that gross negligence penalties are not automatic.
The CRA must establish a high evidentiary threshold before such penalties can be imposed. Where taxpayers can demonstrate reasonable reporting positions or evidentiary uncertainty, penalties may be reduced or eliminated.
For further discussion, see TaxPage’s article on gross negligence penalties:
https://taxpage.com/articles-and-tips/income-tax-gross-negligence-penalties/
Strategic Negotiation Can Resolve Tax Disputes Without Trial
Many taxpayers assume that a Tax Court of Canada appeal will proceed to trial. In practice, most matters are resolved through negotiation when properly prepared.
A well-developed evidentiary record, combined with disciplined legal positioning, often creates strong settlement leverage with counsel representing the CRA.
According to David J. Rotfleisch:
“In tax litigation, the best results are often achieved not at trial, but at the point where the evidentiary record forces a realistic reassessment of risk.”
CRA Tax Audit and Tax Reassessment Insights from an Experienced Canadian Tax Lawyer
Taxpayers facing a CRA tax audit, CRA tax reassessment, or Tax Court of Canada appeal should consider the following strategic principles.
Early Engagement of a Canadian Tax Lawyer Improves Outcomes
Early involvement of an experienced Canadian tax lawyer can materially improve outcomes by ensuring:
- proper issue identification
- timely procedural compliance
- preservation of evidentiary records
- strategic framing of disputes
Documentary Evidence Is Often Decisive in CRA Tax Disputes
The strength of a taxpayer’s case frequently depends on documentation rather than oral explanation. Banking records, POS data, accounting systems, and third-party confirmations can all play a critical role.
CRA Assumptions Must Be Actively Challenged
Taxpayers should not accept CRA assumptions at face value. Each assumption underlying a CRA net worth assessment should be tested against available evidence.
Objection Deadlines Must Be Carefully Managed
Missing objection deadlines can significantly restrict legal remedies.
For more information, see TaxPage’s article on Notices of Objection:
https://taxpage.com/articles-and-tips/notice-of-objection/
and Tax Appeals:
https://taxpage.com/tax-appeals/
What Does a CRA Net Worth Audit Lawyer in Canada Do?
A CRA net worth audit lawyer in Canada assists taxpayers in challenging CRA reassessments that are based on indirect income estimation methods rather than direct accounting records. These cases typically involve reviewing CRA assumptions, reconstructing financial data, challenging gross negligence penalties, and representing taxpayers in Tax Court of Canada appeals. Effective defence strategies often rely on forensic review of banking records, accounting systems, and point-of-sale data to demonstrate inconsistencies in the CRA’s reconstruction methodology.
CRA Net Worth Audit Defence Strategies Used in Tax Court of Canada Appeals, Frequently Asked Questions About CRA Net Worth Audits, Gross Negligence Penalties, and Tax Court Appeals
Similar evidentiary reconstruction principles apply in Canadian crypto tax audit disputes involving blockchain verification and exchange record analysis (see cryptotaxlawyer.com for related analysis).
What is a CRA net worth audit?
A CRA net worth audit is an indirect audit method used to estimate income based on changes in assets, liabilities, and expenditures rather than direct accounting records.
Why does the CRA use net worth assessments?
The CRA uses net worth assessments when it believes a taxpayer’s records are incomplete or unreliable.
Can CRA net worth assessments be challenged?
Yes. They are frequently challenged where assumptions regarding assets, liabilities, or expenditures are incorrect or unsupported.
Can a CRA net worth audit be successfully challenged in Canada?
CRA net worth audit can be successfully challenged in Canada where the CRA’s assumptions regarding income, assets, liabilities, or personal expenditures are inaccurate or unsupported by evidence. These audits are indirect and rely on reconstructing income based on changes in net worth rather than direct accounting records. As a result, they are highly sensitive to errors in opening balances, asset valuation, shareholder loans, and non-taxable sources of funds. In Tax Court of Canada appeals, taxpayers often succeed by providing banking records, accounting documents, and other objective financial evidence that contradicts the CRA’s assumptions and demonstrates a more accurate financial picture.
What evidence is most important in a CRA tax audit defence?
The most important evidence in a CRA tax audit defence is objective, contemporaneous financial documentation that independently verifies income and expenses. This typically includes banking records, corporate and personal tax returns, accounting ledgers, point-of-sale (POS) data, and third-party records such as franchisor or supplier reports. In CRA net worth audit cases, reconciliation between POS systems, bank deposits, and reported income is especially persuasive because it directly tests the CRA’s reconstructed income assumptions. The strongest defence evidence is consistent, verifiable, and capable of directly challenging the CRA’s indirect audit methodology.
Can gross negligence penalties be removed?
Yes. They may be reduced or eliminated depending on the facts and evidentiary record.
What is the role of a Canadian tax lawyer in a CRA audit?
A Canadian tax lawyer assists with evidence review, procedural strategy, dispute resolution, and Tax Court representation.
When should a taxpayer seek legal advice?
As early as possible, ideally at the start of a CRA tax audit or immediately upon receiving a reassessment.
CRA Tax Audit Take Away: Importance of an Experienced Canadian Tax Lawyer in CRA Net Worth Assessment Disputes
This case demonstrates that a CRA tax audit outcome is not predetermined.
TaxPage’s litigation strategy in this matter demonstrates how structured evidentiary development combined with procedural remediation can materially alter the outcome of CRA tax audit and Tax Court of Canada appeal proceedings.
Despite significant initial exposure, procedural deficiencies, and a substantial CRA net worth assessment, TaxPage was able to achieve a materially improved result through structured litigation strategy, evidentiary development, and targeted negotiation.
The final outcome included a reduction of taxable income from approximately $727,000 to approximately $310,000, elimination of gross negligence penalties exceeding $66,000, and total financial savings estimated at approximately $330,000.
This result underscores the importance of engaging an experienced Canadian tax lawyer or Canadian tax appeal lawyer early in the process to properly manage both evidentiary and procedural risks.
According to David J. Rotfleisch:
“A CRA tax reassessment is not the final word. With the right evidentiary foundation and legal strategy, many assessments can be significantly reduced or successfully challenged.”
Disclaimer: This article is provided for general informational purposes only and reflects the law as of the date of publication. It does not constitute legal advice and should not be relied upon as such. Tax situations are highly fact-specific and may vary significantly depending on individual circumstances. Readers facing a CRA tax audit, CRA net worth assessment, gross negligence penalties, or a Tax Court of Canada appeal should seek advice from an experienced Canadian tax lawyer.
Case Overview:
Jill (real name withheld due to solicitor – client confidentiality) is a resident of Ontario and owned one condo in downtown Toronto, and a bigger and more expensive home in the affluent community of Oakville, southwest of Toronto.
In 2022, Jill bought the condo and began actively splitting her time between the condo and her Oakville home. Jill, among various other reasons, used the condo to be closer to her friends and family, attend live entertainment including the ballet, watch local plays, and support her favourite hockey team at Scotiabank Arena.
The Problems & Our Approach:
1st Issue: Jill’s First Mistake
Jill filed the Vacant Home Tax Declaration (‘VHT Declaration’) in time and avoided having to pay the Vacant Home Tax (‘VHT’) for 2022. Inadvertently, she missed the deadline of February 29, 2024, to file her VHT Declaration for 2023. This was her first mistake.
In March of 2024, Jill sold the condo to Mr. and Mrs. Purchaser, who were both arm’s length purchasers from her. In the same month, the condo was deemed vacant by the City of Toronto (‘Toronto’) due to the failure of Jill to file a VHT Declaration for the 2023; and Toronto issued VHT assessment to Jill for a total amount of about $16,000.
In an effort to correct her omission, in April of, 2024, Jill filed a Notice of Complaint with Toronto (‘the complaint’) in order to have the Condo declared as occupied for the 2023 calendar year.
2nd Issue: Jill’s Second Mistake
Jill filed the complaint online through Toronto’s application portal. This complaint simply read as follows:
To whom it may concern
I recently filed in my vacancy tax form incorrectly. I lived there. I just have residences and go back and forth due to family issues.
Thank you,
Jill
Jill, in a hurry and thinking that this issue would be resolved quickly and easily, wrote and submitted this simple and short letter without providing proper details of her living situation and without any supporting documentation.
Worse, Jill decided against getting the help of skilled Canadian tax lawyers believing her problem was a trivial issue.
3rd Issue: Unconstitutional approach taken by the City of Toronto in handling this situation
In July 2024, Toronto Revenue Services Division, instead of issuing the letter to Jill who filed the complaint and who owned the condo in 2023, issued the decision letter addressed to Mr. and Mrs. Purchaser, current owners of the condo, notifying them that the complaint had been filed. The letter also asked Mr. and Mrs. Purchaser for additional supporting documents to confirm the occupancy status of the condo during the 2023 calendar year.
Further, the July letter also indicated that, as the condo had been purchased by Mr. and Mrs. Purchaser in 2024, that the new owners would not be eligible to file a notice of complaint themselves, but would be liable for the VHT assessed. This made Jill vulnerable to a potential civil lawsuit by Mr. and Mrs. Purchaser for the complete VHT.
4th Issue: Jill’s Third Mistake
When Jill received the July letter from Mr. and Mrs. Smith’s lawyer, Jill, once again wrote to the Toronto Revenue Services Division in August of 2024 stating that although the condo was not her ‘primary residence’, she lived there at least half of the year, if not longer.
Jill further stated that she has family in Toronto, her ex-partner, and friends and therefore, owned a second property. Finally, Jill stated that she did not rent the apartment nor was it vacant. To support her letter and her position, Jill attached her (1) property tax bill from Toronto and (2) Toronto hydro (electricity) bills for the condo for 2023.
Taxpage, after having a consultation with Jill, found out that when Jill wrote to the City of Toronto stating that the condo was not her ‘primary residence’, Jill was thinking in terms of her persoanfederal income tax exemption for her primary residence. Her obligations related to this new (VHT) municipal tax did not cross her mind.
Jill did not declare her condo as her principal residence in her income tax return for her principal residence exemption. She saved that for her Oakville house, which is much more valuable, but this did not negate the fact that she primarily stayed in the Toronto condo.
Furthermore, the property tax bills and electricity bills, although addressed to Jill, were delivered to Jill’s Oakville residence.
Lastly, in the eyes of the City of Toronto, Jill would have incurred property tax and bare minimum electricity bills even if she did not reside at her condo.
Because of lack of prima facie evidence, in September of 2024, Toronto rejected Jill’s second complaint and therefore decided that she was still liable for VHT. Once again, the City of Toronto provided no reasons to Jill and the decision letter was again delivered to Mr. and Mrs. Purchaser who had absolutely nothing to do with the filing of the complaint.
Jill Finally Seeks the Help of Canadian Tax Lawyers at Taxpage
In November of 2024, Jill hired Taxpage to help her out. Taxpage immediately filed a Freedom of Information request with the City of Toronto to obtain (1) all evidence and complaints submitted by Jill and; (2) internal notes of the city of Toronto, so that we could find out why Toronto was refusing to waive the VHT. No rationale was ever provided by the City of Toronto to Jill for their determination that she was liable for VHT.
By the beginning of December of 2024, we received the Freedom of Information package from the City of Toronto which provided Taxpage with some insight.
Now, because the deadline to file an administrative appeal was 90 days from the issuance of appeal and time was running out, the Canadian Tax Lawyers at Taxpage used the information package from the Toronto to immediately prepare and submit an appeal to Toronto and explained (1) why Jill stated that Condo is not her primary residence (2) and why the usage of Condo by Jill was enough in the eyes of the Toronto municipal law for it to consider the Condo as ‘ordinarily occupied’ in the eyes of the bylaw of Toronto.
Steps Taken by Taxpage to Resolve the Vacant Home Tax on Jill’s Condo
For supporting documents, Taxpage, in addition to electricity bills, attached:
- Home Internet and TV Bill
- Home Insurance Bill
- Email correspondence between Jill and her friends to coordinate gatherings at the condo
- Email correspondence between Jill and her property manager for general repair and upkeep of the condo
- Sales receipts for catering delivery to the condo
- Affidavits of Jill and her ex-partner attesting to Appellant’s use of the condo.
Despite submitting a detailed appeal and supporting documents, the City of Toronto still refused to waive the VHT. Furthermore, the City of Toronto, in all its wisdom, once again issued its decision letter in response to our appeal to the Real Estate Lawyer of Mr. and Mrs. Purchaser, which was forwarded to us after a month.
And to make matters worse, the City of Toronto once again provided no rationale for its determination and simply replied that Jill did not have enough evidence to prove her residence at the condo.
Taxpage Lawyers Talk to the City of Toronto’s Lawyers
Jill, on recommendation by Taxpage, decided to have us file a judicial review application of the City of Toronto’s decision with the Superior Court of Justice (Divisional Court) of Ontario (‘Div. Crt.’) as we had exhausted all administrative options to challenge the decision.
After filing the judicial review application, the Litigation Lawyer acting for the City of Toronto responded to our application and during the appeals process, Taxpage lawyersspoke directly to the City of Toronto’s lawyer, as is normal during litigation.
We explained our complete case to Toronto’s lawyer; that is, why Jill stated that condo is not her ‘primary residence’; provided valuation of Jill’s Oakville home to the lawyer (and to the Div. Crt. as well) and explained to him that because her Oakville home was way more expensive than the condo, it made sense for Jill to list her Oakville as her principal residence to claim her Personal Residence Exemption when filling her federal income tax.
We also explained to the City of Toronto Lawyer that their refusal to provide rationale for their decision made it hard for Jill (and for us at the Taxpage) to provide a proper submission to support her claim.
Result
Finally, the City of Toronto lawyer, well-versed in administrative law and constitutional law (unlike the Toronto Revenue Services Division), understood the complete issue (and foresaw the likely defeat of the City of Toronto at the judicial review hearing). He wisely decided to drop the $16,000 VHT levied against Jill’s condo just weeks before the application was scheduled to be heard in court.
Lessons Learned
Canadian taxpayers often make the wrong assumption that government officials on the other side, whether at the federal level (such as CRA) or provincial and municipal level, will be unbiased and well-versed in tax law. But the Canadian tax lawyers at Taxpage, often find that this is seldom the case.
Therefore, we always recommend that taxpayers get the experts involved to defend their rights from the very onset. As we see in this case, had Jill sought expert legal help in the beginning, the confusion of ‘primary residence’ would have never occurred. Moreover, Taxpage would have attached all important supporting documents from the very first submission.
Disclaimer: This case study provides information of a general nature only. It is only current at the posting date. It is not updated, and it may no longer be current. It does not provide legal advice, nor can it be relied upon. All tax situations are specific to their facts and will differ from the situations in the articles. If you have specific legal questions, you should consult an experienced Canadian Tax Lawyer.
Case Overview:
Taxpage has been tax counsel to clients, a married couple, whom we shall call Jack and Jill (names changed due to Solicitor – Client confidentiality) for the past 25 years. As part of our representation of Jack and Jill during all these years, we managed all their interactions with the Canada Revenue Agency (CRA). Please note that regardless of their marital status, Jack and Jill, like all Canadian taxpayers, are taxed individually and file separate tax returns in Canada.
In spring 2019, Jack and Jill were selected for a tax audit by the CRA’s Offshore Compliance Program. The CRA stated from the outset that this tax audit was to encompass only the years from 2010 through 2017.
Junior, the son of Jack and Jill, held a Swiss bank account through a trust. Junior and the trust are not Canadian tax residents. Over some years, Jack was a signing officer and potentially a Power of Attorney on the trust account.
The Problems & Our Approach:
1st Issue: CRA’s ‘Fishing Expedition’ and Taxpage’s tactics to stop it
In 2021, during the audit, Taxpage convened a conference tax audit interview with the CRA tax Auditor and her Team Leader. The attendees were (1) Mr. David Rotfleisch, Certified Tax Law Specialist and Chartered Professional Accountant (CPA) and Principal of Taxpage: (2) supporting tax lawyers, (3) the taxpayers being audited, and (4) officials from CRA.
During this meeting, the CRA Tax Auditor informally requested if there were any additional bank accounts held by Jack or Jill in the period from 2018 to present [2021]. Jill stated that she had an account briefly in 2019 at “Swiss Bank”. At the conclusion of the conference call, all participants, including Taxpage lawyers, agreed to forward, on an informal and voluntary basis (since the years being discussed were outside of the tax audit period) to the CRA on behalf of Jill, the statements from those accounts, which had already been closed. During the tax audit period as such, and up to the date of opening of Jill’s Swiss Bank account neither Jack nor Jill held any accounts at Swiss Bank.
As part of the tax audit, which became a fishing expedition at this point, the CRA sent a request to the Swiss Federal Tax Authority (Swiss FTA) requesting information and documents on any account held at the Swiss Bank for which Jack and Jill had a “Power of Attorney”.
Further, the CRA had made no such similar request related to powers of attorney to either Jack or Jill directly. This request from CRA did not name any specific 3rd parties. Moreover, this request by CRA to Swiss FTA was kept a secret from both Taxpage and Jack and Jill themselves. Taxpage was informed about CRA’s request to Swiss FTA via our trusted sources.
2nd Issue: CRA requested information that was improper and unlawful
During the tax audit or at any other time, the CRA has never requested from Taxpage any information related to any bank accounts or other property over which Jack and Jill have no beneficial interest, but merely a Power of Attorney or signatory power.
Had the CRA made such a request to us, we would have formally denied it, as in the opinion of Taxpage lawyers, it is clear from a Canadian income tax law perspective that such a request is improper and unlawful.
In fact, the Canadian tax lawyers at Taxpage had never seen such a request from CRA during their 40 years of practice.
Under Canadian tax law, a taxpayer is only required to report income and existence of any foreign property in accordance with the rules for reporting Specified Foreign Property (a defined term under the Canadian Income Tax Act) if the taxpayer is the beneficial owner of the same, regardless in which jurisdiction the property is situated. The 3rd party accounts on which a taxpayer merely holds a power of attorney or signatory power are taxwise irrelevant, and the respective bank information is thus not to be included in tax audit of the taxpayer.
As soon as Taxpage got to know that the request has been made by the CRA behind their backs to Swiss FTA, Taxpage immediately drafted a detailed letter to the Swiss Bank and informed them that any requests made to any party in relation to property in which Jack and Jill have no beneficial interest is improper and should be ignored or explicitly denied. In the letter, we further reiterated that no such request was made by the CRA to Jack and Jill directly.
In addition to notifying Swiss Bank about the rights of our clients, we also teamed up with a premier Swiss Law Firm expert in Swiss Tax Law in order to protect the interests of our clients. Taxpage provided the Swiss tax lawyers our Canadian legal analysis regarding the validity of the Request for Information (RFI) made by CRA to Swiss FTA.
Further, we at Taxpage informed the Swiss tax lawyers that if Swiss FTA proposes to release information about our clients Jack and Jill to CRA, Swiss tax lawyers would make a strong request to Swiss FTA to put the process on hold, pending resolution of an application (Writ of Mandamus) in the Federal Court of Canada to quash the entirety of the request on the basis of the patently false information set out therein.
Finally, the Swiss FTA, after the intervention of the Swiss tax law firm acting at the behest of Taxpage, refused to provide information about our clients Jack and Jill to CRA without Taxpage having to file the application to the Federal Court of Canada.
3rd Issue: CRA’S Offshore Compliance Program (OCP) kept the audit going for another 4 years
A reasonable person would think that 3 years would be more than enough time for Canada Revenue Agency to finish the audit. Various employees of the CRA working on the tax audit kept going on leaves of absence of more than 1 year, or retiring, while the file kept getting tossed from one auditor and team leader to another auditor and team leader.
Every time the CRA made a genuine request for more information and documents during the audit, we at Taxpage successfully provided the requested information and documents immediately in order to bring the audit to an end, but with every passing auditor, the CRA kept taking more and more time to respond to our emails and phone calls.
At this point, Taxpage and its clients, Jack and Jill, were unfortunately trapped in the bureaucracy. There is nothing that can be done to speed an audit along. Complaints and court applications will not achieve anything; , so we were going to waiting for this audit to end. But there was still one thing we could do.
Tax lawyers at Taxpage continued to follow up with the CRA to keep the pressure on them:
- we diarized follow-ups for the next few months;
- made phone calls from different phone lines because the CRA auditor stopped picking up our calls made from our usual phone lines;
- made irregular calls at odd times to catch the auditor off-guard.
The Result
Finally, in spring 2026, after 7 years, Taxpage received an audit completion letter from the CRA informing us that there was no problem in the tax filings of our clients. Because CRA’s ‘fishing expedition’ went nowhere, they decided to ‘cut bait.’ The Canadian tax lawyers at Taxpage got our clients, Jack and Jill, ‘off the hook’ completely.
Lessons Learned:
First, the CRA can and does chose Canadian Taxpayers for audit randomly. Therefore, Taxpage advises Canadian taxpayers to be very careful in filing their taxes; keep all bank records including in particular offshore bank accounts, sales records, receipts, invoices, and any other important paperwork in your possession for 10 years. It is better to get expert tax advice in the beginning when filing taxes so that in case the CRA audits you, your paperwork is complete. .
Second, CRA records every conversation during the tax audit, and the first conversation is the most important. A lot of Canadian taxpayers initiate the conversation with CRA officials and end up divulging potentially incriminating information and reach out to tax lawyers when it is too late. The best move is to always let an expert Canadian tax lawyer handle all communication with CRA officers from the beginning.
Third, the CRA can intrude on constitutional rights of Canadian taxpayers and has done so in the past. It is very important that Canadian tax lawyers are brought in to prevent the CRA from exceeding their executive authority.
Disclaimer: This case study provides information of a general nature only. It is only current at the posting date. It is not updated, and it may no longer be current. It does not provide legal advice, nor can it be relied on. All tax situations are specific to their facts and will differ from the situations in the articles. If you have specific legal questions, you should consult an experienced Canadian Tax Lawyer.
Case Overview:
The client was a self-employed musician who applied in good faith for a number of COVID-19 benefits released by the Federal Government of Canada, including the Canada Emergency Response Benefit (“CERB”) and Canada Recovery Benefit (“CRB”). The musician’s business was almost entirely halted due to COVID-19 lockdown restrictions on public performances.
The Canada Revenue Agency had initiated a review of the musician’s entitlement to those benefits. The musician’s benefits were denied at first review and second review because the musician purportedly failed to satisfy the minimum threshold of $5,000 in net income prior to the beginning of the COVID-19 pandemic.
However, the Canada Revenue Agency agents reviewing the musician’s case failed to provide a meaningful time to respond to requests and provided no reasons for rejecting the musician’s supporting documents showing at least $5,000 in net income during the relevant periods. The Canada Revenue Agency’s attempts to reach the musician were limited to a handful of phone calls.
The musician self-filed a Notice of Application for judicial review with the Federal Court, but mistakenly filed supporting evidence with those pleadings. The musician subsequently missed the deadline to serve supporting documents for that judicial review Application. Rotfleisch & Samulovitch was retained to bring the Application back on track, and to preserve the musician’s legal rights.
The Problem:
The Minister of National Revenue is granted the authority under law to verify an applicant’s eligibility for the CERB and CRB. If the Minister of National Revenue determines a person was not entitled to receive an income support payment, the Minister can choose to deny eligibility for those benefits. The Canada Revenue Agency exercises these powers on the Minister’s behalf.
Discretionary decisions of the Minister can be challenged by way of judicial review to Federal Court. With judicial review, the Federal Court is not responsible for reconsidering, reweighting, or reassessing information reviewed by a decision-maker. Rather, the Federal Court must evaluate if the decision made was reasonable after weighing the rationale provided by a decision-maker against available evidence. The Federal Court is also empowered to protect the procedural fairness of a review process. If a decision was unreasonable or a proceeding was procedurally unfair, the Federal Court can “quash” that decision, and send the case back for a redetermination. The Federal Court cannot make a decision for the Minister and can only require the Minister to reconsider the matter with additional guidance.
Judicial review is a fast process. Within 30 days of filing a Notice of Application, the Applicant must serve and file any affidavits and supporting evidence. Failing to meet any deadlines under the Federal Courts Rules can result in an Application being dismissed. And the right to extend deadlines is very limited.
Our Approach
Our Canadian tax litigation lawyers immediately contacted the Department of Justice Canadian tax lawyer assigned to our client’s file, and negotiated an extension of time to serve the client’s affidavit and supporting evidence.
We also undertook a thorough review of the client’s evidence, and filed a Rule 317 Request to obtain the full tribunal record reviewed by the Canada Revenue Agency agents who denied the client’s benefits. On reviewing those materials, it was discovered those agents had never actually contacted the client as suggested in their file notes. The client could produce phone records corroborating that phone calls purportedly made by the Canada Revenue Agency’s agents had never occurred, and that purported voicemails had never been left at the client’s phone number. While the evidentiary record at judicial review is usually constrained to what the decision-maker had available at the time, this evidence highlighted procedural defects not found in the tribunal record and was admissible.
We then immediately pushed for a settlement with the Department of Justice to have our client’s file sent back for a new review by an independent agent. We executed the Minutes of Settlement to obtain a new review, and filed a Notice of Discontinuance with the Federal Court shortly after, ending the Application.
The Result
The client’s file was sent back for a redetermination on its merits, with a new opportunity to submit supporting documents and to respond to further requests for information. In doing so, the musician was saved the full costs of a hearing before the Federal Court, while obtaining the exact remedy our client sought.
Lessons Learned
- Federal Court timelines for judicial review are unforgiving. Always make sure deadlines are met.
- The certified tribunal record is crucial for any judicial review case. The Federal Court rarely considers fresh evidence at a judicial review hearing. All supporting documents that can be submitted should be submitted on time during the initial review process to develop the tribunal record early.
- A hearing is not always required to win. Settlement can present a path to victory for a fraction of the cost.
- Do not undertake court proceedings without at a minimum advice from a tax lawyer and generally without fully retaining a lawyer to act on your behalf.
Case Overview:
A client retained Rotfleisch & Samulovitch to handle his TFSA related issue outstanding since 2016. The client had mistakenly overcontributed to his TFSA account and subsequently suffered significant losses in his TFSA investment account. As a result, the balance in his TFSA went down so much that the client had insufficient funds to withdraw the full excess contribution amount from his TFSA account. Further, the client has previously submitted a TFSA waiver request on his own, which was rejected by the Canada Revenue Agency. Due to the negative TFSA contribution room limit, the client continued to accrue interest and had no way to resolve the issue.
The Problem
The law A taxpayer’s TFSA contribution room is the maximum amount that a taxpayer can contribute to his or her TFSA account(s). Once the contribution room is used, withdrawals, excluding qualifying transfers and specified distributions, do not reverse the used contribution room. At any time in the year, if a taxpayer contributes more than his or her available TFSA contribution room, the taxpayer will have to pay a tax equal to 1% of the highest excess TFSA amount in the month, for each month that the excess amount stays in the taxpayer’s TFSA account(s).
A taxpayer is required to withdraw any excess contribution from his or her TFSA account(s) as soon as the taxpayer becomes aware of the issue, in order to qualify for relief via a TFSA waiver request. Other conditions must also be met for the relief to be granted by the CRA.
However, in the event that a taxpayer cannot withdraw the full amount of excess TFSA contribution due to investment loss, a taxpayer remains liable for the 1% tax of the highest excess TFSA amount in the month.
Normally, CRA takes the position that “only new TFSA contribution room that becomes available to the individual in future years will serve to reduce the excess TFSA amount.”
Our Approach:
We prepared and submitted a detailed second TFSA waiver request, including requesting a special one-time contribution room limit adjustment, asking the Canada Revenue Agency to allow an adjustment to the client’s TFSA contribution room limit, due to the client’s inability to remove the full amount of excess TFSA contribution. This is not an option set out or recognized by CRA. However, we made forceful arguments about the client being that it would be unfair to continue to penalize and charge the client a monthly tax indefinitely. As TFSA waiver request generally take several months to be processed, we actively followed up with the Canada Revenue Agency to have the client’s TFSA issue resolved as soon as possible.
The Result:
The client’s TFSA contribution room limit was adjusted to nil from -$125,561.91, once the TFSA waiver request has been accepted by the Canada Revenue Agency, saving the client over $4,000 in payable taxes and preventing any further monthly interest and penalties. The client also remained entitled to the annual increase of TFSA contribution room limit.
Case Issue
Our office was approached to represent an Ontario corporation (the “Corporation”) after its request for penalty and interest relief under the Canada Revenue Agency’s (“CRA”) Voluntary Disclosures Program was denied. The Corporation began operating in 2003, and earned significant income over the course of nearly two decades without filing any T2 corporate tax returns or GST/HST returns. The Corporation was involuntarily dissolved in 2007 for failure to file yearly information returns with the Ontario Ministry of Finance, but the Corporation’s proprietors continued to operate its business. The Corporation eventually filed a voluntary-disclosure application in 2020 under the CRA’s Voluntary Disclosures Program to correct its non-compliance issues.
The Corporation’s proprietors sought to administratively revive the Corporation after its voluntary-disclosure application was filed. These efforts were thwarted very quickly, however, because of errors on the part of the Ontario Ministry of Finance and the CRA. Specifically, the Corporation’s proprietors believed that the Corporation had a tax year-end that matched a calendar year-end of December 31. The proprietors prepared the Corporation’s tax returns on this basis. However, the Ontario Ministry of Finance and the CRA had each registered the Corporation with a different fiscal year-end. The Corporation therefore required the consent of the Ontario Ministry of Finance and the CRA to consolidate its three different tax year-ends, so that it could prepare and file its outstanding returns correctly for its voluntary-disclosure application.
The Corporation’s efforts were stonewalled by the CRA, who denied its initial request without any justification and subsequently took close to a year and a half to review and overturn its initial decision. The CRA subsequently ceased communicating with the Corporation and its representatives, while the Corporation’s proprietors and representatives continued to provide ongoing disclosure with respect to their efforts to revive the Corporation for its voluntary-disclosure application.
After nearly three years of silence from the CRA, it issued a letter concerning the Corporation’s voluntary-disclosure application. That letter requested the Corporation provide its articles of revival so that the CRA could continue to process its voluntary-disclosure application. That letter imposed a 15-day deadline to respond, and was sent exclusively by regular mail to the Corporation and its representatives. The CRA’s request was received late and was not replied to within the 15-day deadline imposed.
After receiving no response by the imposed deadline, the CRA quickly moved to deny the Corporation’s voluntary-disclosure application on the basis its application was incomplete. Curiously, that letter also stated the Corporation would not be entitled to apply for a second administrative review of the denial by an independent CRA decision-maker. And even more egregious, the decision letter stated that the Corporation’s right to judicial review of the CRA’s decision would be denied. As a result of CRA’s decision, the Corporation risked facing millions of dollars worth of penalties and interest, on top of the extensive tax debt it would owe after filing its outstanding returns.
Our office was engaged by the Corporation’s proprietors almost a month after the CRA’s decision to deny the Corporation relief under the Voluntary Disclosures Program, to determine if a solution could be found.
Approach
Our office immediately gathered all available evidence and filed an application for judicial review with the Federal Court of Canada. In that application, we argued that the CRA’s decision to deny the Corporation’s request for relief under the Voluntary Disclosures Program, and to deny the Corporation a second administrative review of that decision, should be set aside.
Our office argued that the CRA’s decision was unintelligible and that it deprived the Corporation of its rights to procedural fairness. The CRA’s decision regarding the Corporation was an administrative decision that affected the rights and privileges of the Corporation, and which attracted a duty of procedural fairness. Under the rules of procedural fairness, an adjudicator’s decision must be intelligible. Further, an applicant must have the right to make submissions and to present evidence.
Our office argued the CRA’s decision was a complete denial of natural justice and breached the Corporation’s right to procedural fairness in light of the principles above. First, the CRA’s letter imposed only a 15-day deadline to reply, and was issued by regular post. After nearly three years of silence from the CRA concerning the status of the Corporation’s voluntary-disclosure application, the Corporation was effectively ambushed with the CRA’s request, and which failed to provide the Corporation any meaningful opportunity to respond to its request for information. Second, the Corporation would have been unable to meet the CRA’s request for information in large part because of the inadvertence of the CRA itself. By denying the Corporation’s reasonable requests to have its tax year-end adjusted, the CRA itself had prevented the Corporation from being able to meet the CRA’s demands.
Third, and perhaps most egregious, was that the CRA’s decision explicitly denied the Corporation’s right to recourse. The decision letter denied the Corporation’s right not only to a second administrative review of CRA’s decision, but surreptitiously the Corporation’s right to file an application for judicial review. That right to file for judicial review is enumerated under section 18.1 of the Federal Courts Act, and the CRA had no right to deny the Corporation its statutory rights. The severe disconnect between the CRA’s reasoning and the outcome of its decision was untenable and rendered its decision wholly unreasonable.
Result
The CRA’s legal counsel at the Department of Justice engaged in settlement discussions with our office to resolve the Corporation’s judicial review prior to cross-examinations. The CRA consented to a settlement offer where the Corporation’s voluntary-disclosure application would be referred back for reconsideration, and the Corporation would be allowed to continue seeking its articles of revival. As a result, the avoided millions in penalties and interest owing for denial of relief under the Voluntary Disclosures Program, and its application was allowed to proceed on its merits.
Problem: Principal residence exemption denied
Rotfleisch & Samulovitch Professional Corporation represented a client who had been denied the principal residence exemption during a CRA income-tax audit.
The client had entered into an agreement to purchase the property in British Columbia a few years before the client was able to move in. Approximately six months after the property became available for possession, the property was sold after the client had resided at the property for four months. The client designated the property as the principal residence and filed a Principal Residence Exemption claim.
The CRA tax auditor initially intended to reject the client’s Principal Residence Exemption claim of $184,580 and added this amount to the client’s income in the original tax audit letter proposal.
However, as a result of the detailed tax submissions by our top Toronto tax lawyers the CRA tax auditor accepted the full Principal Residence Exemption claim.
Our Approach: Client was not a “house flipper”
Our experienced Canadian tax lawyers filed detailed submissions in response to the CRA tax audit to demonstrate that the property was intended to be the client’s principal residence and that the client was not in the business of “house flipping”.
Specifically, we argued that the relatively short period of time (i.e., four months) that the client resided in the property, prior to the sale of property, was due to unforeseen circumstances and health concerns.
The client’s intention to use the property as the principal residence should not be denied in consideration of the practical limitations. Therefore, the client should be entitled to claim the property as the principal residence.
Result: Complete tax victory over CRA
Our knowledgeable Canadian tax lawyers successfully defeated the tax audit without proceeding to the notice of objection stage. The CRA Audit Division adjusted its original proposal, reducing the client’s income by $184,580 (from $184,580 to nil) and allowing the full Principal Residence Exemption claim during the sale of the client’s property.
Client’s Situation:
Rotfleisch & Samulovitch PC, Canadian tax lawyers in Toronto, were retained by a property investor who intended to purchase a property that needed renovation. As a result of problems with the documentation, our client and her partners were assessed for HST in the amount of $459,286.
To raise funds, our client entered into a partnership agreement with four other individuals and purchased the property via a corporation created under the partnership’s ownership. Once the renovation was completed, the taxpayer decided to buy the property from the other four partners and made payments to each of them directly.
Challenges:
These partnership arrangements and documentation were all made without prior tax planning or consultation with a Canadian tax lawyer so the documentation of the transactions was inconsistent. The Agreement of Purchase and Sale between the taxpayer and her partners indicated the taxpayer
purchased the property from the corporation, while the Full and Final Release indicated the other four partners were the transferors. The CRA seized on these documentation inadequacies and then assessed the corporation for GST/HST on the sale of the property and reassessed the four other partners for the total amount of $459,286 under s.325 of the Excise Tax Act, which imposes joint and several liability for the unpaid GST/HST on the transferee where a person transfers property at less than fair market value on a non-arms length basis.
Our Approach:
Our experienced Canadian tax lawyers filed detailed notices of objection on behalf of the other four partners and made additional substantive and lengthy 52-page submissions in response to the appeals officer’s request to demonstrate that, despite the documentation inconsistency, the reality of the transaction was that the taxpayer only purchased the partnership and share interests from the other four individuals. Therefore, there was no taxable supply (sale in GST/HST language) hence no GST/HST should be owing.
The Result:
After three years and six months from the date we filed the notices of objection, the CRA finally allowed our objections in full and reversed the previous assessment for $459,286.
Case Issue
Our office was approached to represent a family trust (the “Trust”) following an incorrect audit undertaken by CRA’s Audit Division for the Trust’s 2013 to 2016 tax years. The Trust was a discretionary trust, and under the terms of the trust deed, the trustees were entitled to distribute any part or all of the Trust’s annual income and Trust capital at the trustee’s discretion to its beneficiaries (who were all the children of one of the trustees).
The Trust held dividend-paying shares in two very successful private Canadian companies. The Trust also earned business income by performing due diligence and management services for those companies and lending funds to them when necessary. From 2013 to 2016, the Trust earned substantial dividend income and business income from management fees. Further, in 2014, the Trust received payment back on a loan made to one of the companies, earning $3,000 in interest. And in 2015, the Trust sold shares in one company to an arm’s-length purchaser for substantial capital gains.
The Trust resolved (by way of a Deed of Distribution) in each tax year to allocate its income from each source fully to its beneficiaries. The Trust issued a demand promissory note to its beneficiaries totalling the income it had earned, rather than paying those amounts in cash. The Trust’s beneficiaries fully reported these amounts as personal income for their corresponding taxation years. These amounts were therefore deductible by the Trust under paragraph 104(6)(b) because they consisted of the Trust’s income “that became payable in the year to, or that was included under subsection 105(2) in computing the income of, a beneficiary.” As a result, the Trust had next to no taxable income from 2013 to 2016. In 2015, the Trust also elected to make a capital distribution of $50,000 to one beneficiary on a tax-free basis, which was made payable by way of a promissory note as well (and which was not included in any deed of distribution issued by the Trust).
Following an audit by CRA’s Audit Division, the CRA proposed and reassessed the Trust as follows:
- The auditor disallowed deductions that the Trust claimed under subsection 104(6) for: $32,234 in 2013; $19,500 in 2014; $60,000 in 2015; and $100,000 in 2016 (a total of $211,734). The auditor denied these deductions because, in his view, the demand promissory notes underlying these deductions failed to satisfy subsection 104(24), which deems an amount to not be deductible from a trust’s income unless the amount “was paid in the year to the beneficiary or the beneficiary was entitled in the year to enforce payment of it.” More specifically, the auditor compared the amounts that the Trust allocated to its beneficiaries with the Trust’s year-end bank balances. The auditor then concluded that subsection 104(24) precluded the Trust from claiming the deductions because the Trust did not maintain sufficient liquidity in its bank account to pay debts owed to its beneficiaries.
- The auditor disallowed a deduction of $41,744, which the Trust claimed for the 2014 taxation year, because the amount was paid to a non-listed beneficiary of the Trust (one of the trustee’s mother, who was not a beneficiary under the terms of the trust deed).
- The auditor assumed the $3,000 in interest income earned by the Trust was unreported dividend income, and included $4,140 in income for the Trust’s 2014 taxation year.
- The auditor disallowed a deduction for $50,000 claimed by the Trust in its 2015 tax year, on the basis the $50,000 payment to the Trust’s beneficiary could not have been a capital distribution, because the Trust’s opening and closing bank balance for 2015 were nearly identical.
By the time our office was contacted by the client, the trust’s accountant had already filed a notice of objection. Each argument presented in that objection had been flatly rejected by the CRA Appeals Division.
Approach
Our office immediately filed additional detailed submissions, and presented the following arguments to the CRA’s Appeals Division:
- The auditor had misunderstood and misapplied the terms of subsection 104(24), which does not deny a deduction under 104(6) if “the beneficiary was entitled in the year to enforce payment of [the amount deducted under 104(6)].” Rather, because the Trust had issued demand promissory notes, each recipient beneficiary “was entitled in the year to enforce payment of” the amounts that the Trust deducted, and so the amounts were fully deductible by the Trust because they consisted of the Trust’s income “that became payable in the year to a beneficiary.” The auditor had erroneously adopted a liquidity test and conflated the beneficiary’s entitlement to payment with the Trust’s ability to pay in a given year, which flew in the face of not only a plain reading of the statutes, but also case law and the CRA’s own published views on the subject.
- The $50,000 distribution made to a beneficiary of the Trust in 2015 was truly a capital distribution, and in effect the CRA intended to deny a deduction for a distribution by the Trust for which it did not otherwise claim a deduction. We demonstrated through analogy that the auditor’s assertion the Trust’s opening and closing bank balances alone were determinative of whether the Trust had made capital distributions was incorrect and a misapprehension of the law. Rather, by walking the CRA Appeals Division through the documentary evidence, we demonstrated that the capital distribution could be traced through the Trust’s bank balance. In fact, the auditor had arrived at the erroneous conclusion to disallow a deduction to the Trust because the auditor had actually mixed up two beneficiaries of the Trust, one of whom received a capital distribution (for which the Trust did not take a deduction) and the other who received an income distribution (and for which the Trust did take a deduction).
Result
The CRA Appeals Division agreed with our position and reversed the auditor’s decisions, reducing the Trust’s taxable income in 2013, 2015 and 2016 to almost nil. The Trust still recognized taxable income in 2014, in relation to distributions made to a non-beneficiary of the Trust that were erroneously deducted from its income, and for which there was no legal basis to dispute. In total, the CRA Appeals Division reduced the Trust’s taxable income by nearly $200,000 in total.
Case Issue
CRA’s Collections Division attempted to collect corporate taxes against a shareholder of a dissolved corporation. The collections officer examined bank statements of the corporation obtained directly from the bank and alleged non-arm’s length transfers and proposed to assess the client personally for the income taxes owed under section 160 of the Income Tax Act.
Approach
Our office conducted a line-by-line counter analysis and proved that the transfers were actually repayments of the shareholder’s loans to the corporation by paying legitimate business expenses using his personal credit card.
Result
CRA deemed the proposed assessment of $419,021.22 unwarranted and reduced it to $0 without doing any further evaluation.
Case Issue
A client was reassessed and denied a previously paid HST new housing rebate.
Approach
We filed an informal-procedure Tax Court appeal on behalf of the client. While waiting for the hearing date to be set, we approached Crown with our theory and evidence of the case. Crown accepted our arguments and agreed to the appeal in full.
Result
The client saved $26,482.51 without the need to proceed to trial.
Case Issue
The client came to us to represent his corporation, locked out of its premises, pending a Goods and Services Tax/Harmonized Sales Tax (GST/HST) appeal in Tax Court. The books and records of the corporation had been seized, so the Canada Revenue Agency (CRA) assessed an arbitrary amount of $79,852.83 for the corporation’s GST/HST liability for the relevant period.
Approach
After going through the records, we discovered the client had been assessed personally as director of the corporation. We filed a notice of objection with the CRA on the basis that the director had been duly diligent in fulfilling the corporation’s tax obligations. The Crown agreed to put the Tax Court appeal of the corporation on hold until the CRA decides on the objection.
Result
The CRA allowed the objection and vacated the liability assessment of $79,852.83 for GST/HST without the need to proceed to expensive litigation.
Case Issue
A client approached us to handle a denial of more than $1 million in input tax credit (ITC) refunds for the not-for-profit organization.
Approach
We sent a notice of objection to the Canada Revenue Agency, arguing that the disallowed ITCs involved legitimate businesses offering services to the public. The Appeals Division allowed the objection in part and reassessed the Goods and Services Tax/Harmonized Sales Tax (GST/HST) of the not-for-profit for the relevant period.
Result
The client received an ITC refund of $1,413,445.59 and was paid to the corporation.
Case issue
A client approached Rotfleisch & Samulovitch P.C. and sought tax-planning advice about an imminent $1 million payout from a foreign pension.
Approach
Rotfleisch & Samulovitch P.C. recommended a payout structure allowing the client and the client’s ex-spouse to divide the pension per their separation agreement and qualify for the RRSP foreign-pension rollover under paragraph 60(j) of the Income Tax Act.
Result
By following Rotfleisch & Samulovitch P.C.’s advice, they each saved $250,000 in income tax—a total tax savings of $500,000.
Case issue
A husband and wife asked that we represent them during a CRA income-tax audit. As a result of our submissions, the income-tax auditor reduced the initial proposed taxable income by $145,000.
Approach
After the audit’s conclusion, we pursued the dispute with the CRA’s Appeals Division. So far, the appeals officer has agreed to reduce the couple’s taxable income by another $386,000 and cancel all $332,000 in gross negligence penalties.
Result
The objection remains active. But, to date, we have saved the couple from over $265,000 in taxes and $332,000 in gross-negligence fines. They got a total savings of about $597,000, plus a corresponding reduction to the interest previously accrued on the $597,000.
Case issue
Alleging receipt of unpaid shareholder loans, the CRA increased our client’s taxable income by $567,000.
Approach
We filed a notice of objection, convincing the CRA appeals officer to reduce the amount by $61,500. We then filed a notice of appeal to the Tax Court of Canada. We secured an additional reduction of $373,000 during a pre-trial settlement with the Canada Revenue Agency and the Department of Justice.
Result
Our client’s taxable income was reduced by a total of $434,500.
Case issue
The CRA had incorrectly reassessed the client for an additional $330,400 in taxable income. By the time the client approached Rotfleisch & Samulovitch P.C., he had exceeded the deadline to file a notice of objection or an extension-of-time application.
Approach
Still, Rotfleisch & Samulovitch P.C. managed to convince the CRA to reassess the impugned tax year yet again, thereby refreshing the deadline to file a notice of objection. The CRA appeals officer ultimately allowed the objection in full.
Result
The firm reduced the client’s taxable income by $330,400, and the client received an $88,000 tax refund.
Case issue
Rotfleisch & Samulovitch P.C. filed an informal-procedure Tax Court appeal on behalf of a client’s corporation.
Approach
During pre-trial settlement negotiations, Rotfleisch & Samulovitch P.C. convinced the Canada Revenue Agency to allow the small-business deduction under the associated-corporation exemption.
Result
Our client’s corporation avoided $43,700 in corporate income tax.
Case issue
A client requested Rotfleisch & Samulovitch P.C.’s assistance after the CRA denied ITCs claimed by the client’s corporation.
Approach
Rotfleisch & Samulovitch P.C. filed a notice of objection and delivered additional legal submissions to the Canada Revenue Agency’s Appeals Division.
Result
The client saved $35,800 in GST/HST.
Case issue
A client asked our firm for advice after a GST/HST auditor proposed to apply $174,240 in gross-negligence penalties.
Approach
We provided the GST/HST auditor with a legal analysis showing that the auditor had misinterpreted the Excise Tax Act’s provisions on gross-negligence penalties. In response, the auditor rescinded the gross-negligence penalties.
Result
The client avoided the $174,240 and the interest that would have accrued on that amount.
Case issue
A client approached our firm for representation after a CRA tax auditor proposed to increase his taxable income by $3.2 million.
Approach
As a result of our legal submissions, the auditor reduced the initial proposed taxable income by $335,000 and cancelled all interests accrued due to the CRA’s delays.
Result
This dispute remains active.