
Published: August 21, 2026
Overview
If you have already filed a Notice of Objection and the CRA has confirmed a reassessment you disagree with, your next stop is the Tax Court of Canada, and the Informal Procedure vs. General Procedure decision is one of the first strategic choices you and your Canadian tax litigation lawyer will make. That choice, made in the Notice of Appeal itself, shapes almost everything that follows: whether you need a lawyer, whether there will be document discovery, how much a loss will cost you in legal fees, and even whether you can appeal a bad result.
Many taxpayers assume the “informal” track is simply the cheaper, friendlier option and default to it without thinking through the tradeoffs. That assumption is not always correct, and getting the election wrong can lock a taxpayer out of tools, such as full discovery or a broader right of appeal, that might have mattered.
Background: Two Tracks, One Court
The Tax Court of Canada was created in 1983 to give taxpayers a specialized forum for disputes with the CRA, separate from the general federal courts. That choice is made when you file your Notice of Appeal, generally within 90 days of the CRA’s confirmation or reassessment (see our guide to deadlines for Notices of Objection and Appeal, and available extensions, if that window has already passed or is close to expiring). Recognizing that many disputes involve modest dollar amounts and self-represented taxpayers, the Tax Court operates under two parallel sets of rules: the Tax Court of Canada Rules (General Procedure) and the Tax Court of Canada Rules (Informal Procedure). Both are made under the Tax Court of Canada Act, and both apply to income tax, GST/HST, and several other federal tax appeals.
Eligibility for the Informal Procedure is capped by dollar amount. Under the current, in-force text of the Tax Court of Canada Act, a taxpayer can elect the Informal Procedure where the federal tax and penalties in dispute, excluding interest, are $25,000 or less per taxation year, or where the loss being determined or redetermined is $50,000 or less. GST/HST appeals use a $50,000 threshold. If your dispute exceeds those limits but you would still rather use the Informal Procedure, you can generally get there by expressly agreeing, in the Notice of Appeal, to cap your claim at the applicable threshold. Anything above the threshold defaults to the General Procedure, and the General Procedure is also available to any taxpayer who simply prefers it, regardless of dollar amount.
These thresholds are set to rise. The Budget 2025 Implementation Act, which received royal assent on March 26, 2026, gives the Governor in Council authority to raise the Informal Procedure eligibility thresholds to $50,000 for income tax and penalties, and $100,000 for loss determinations and GST/HST. That increase has not yet been brought into force, so the $25,000 and $50,000 figures above remain the operative thresholds for now.
The $25,000 figure is easy to misread. It refers to the aggregate amount in issue as defined in the Tax Court’s rules, which counts only the federal portion of the income tax and penalties assessed, not the provincial tax portion and not interest. A taxpayer whose total reassessment letter shows a much larger number can still qualify for the Informal Procedure once provincial tax and interest are stripped out, so it is worth having a Canadian tax litigation lawyer calculate the aggregate amount properly before assuming a dispute is too large for the Informal track.
A Third Path: When Judicial Review Applies Instead of the Tax Court
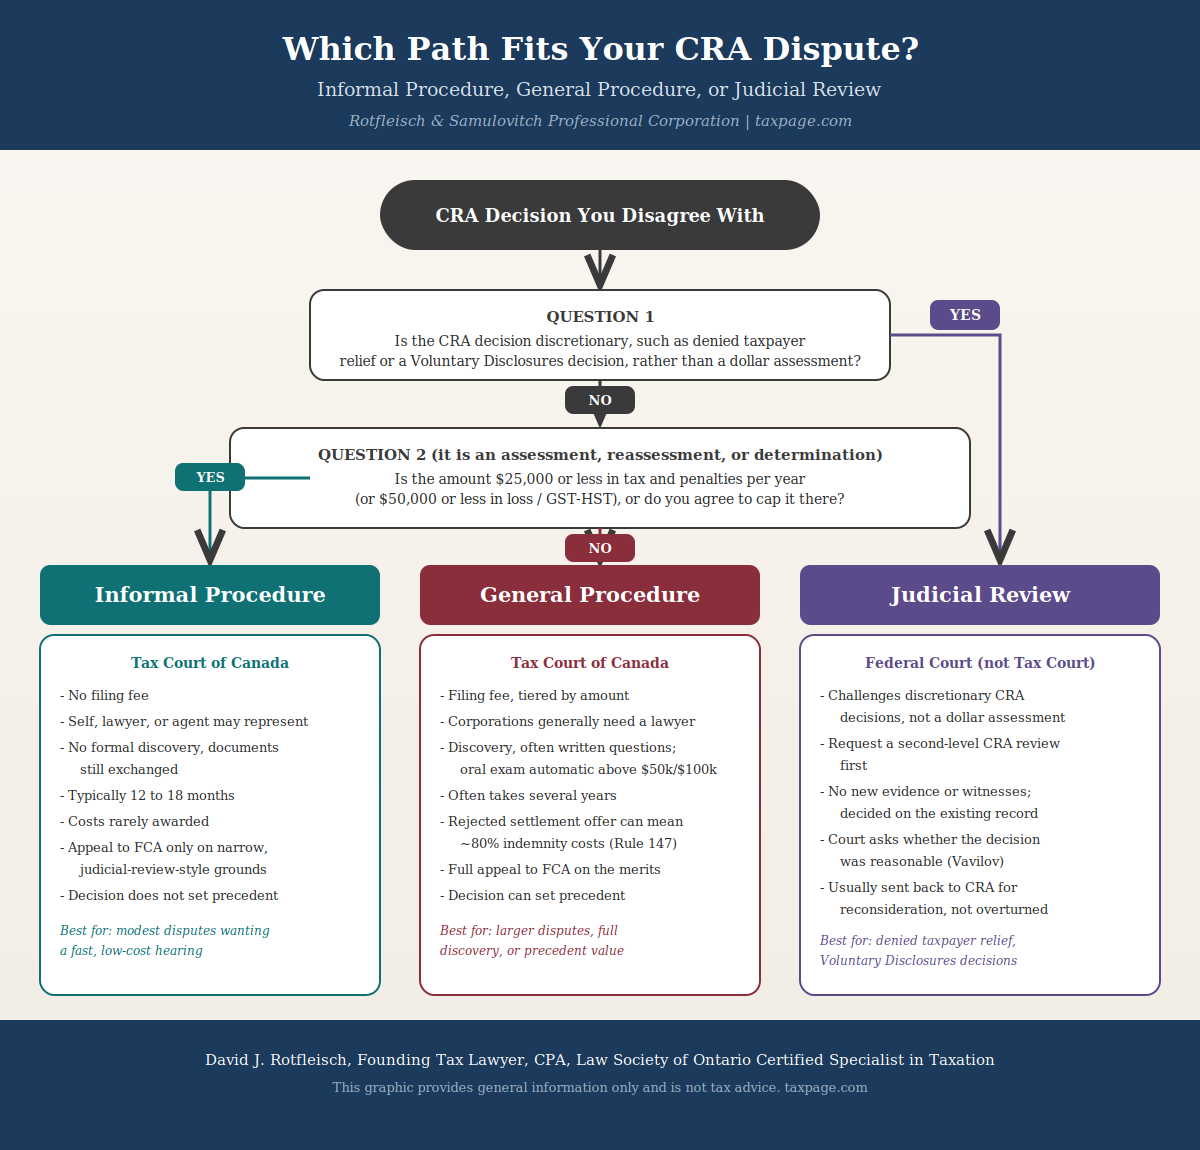
Both the Informal and General Procedures assume your dispute is over an assessment, reassessment, or determination, in other words, a fixed decision about how much tax, penalty, or interest you owe. Not every disagreement with the CRA takes that form. Some CRA decisions are discretionary rather than a determination of a specific dollar amount: a denied taxpayer relief application to cancel or waive penalties and interest under subsection 220(3.1), a Voluntary Disclosures Program decision, or a similar exercise of ministerial discretion. The Tax Court has no jurisdiction to override those decisions, however unfair they may seem, because there is no assessment being appealed.
For discretionary decisions like these, the correct route is not a Notice of Appeal to the Tax Court at all. It is an Application for Judicial Review to the Federal Court under the Federal Courts Act. Before filing, it is worth requesting a second-level administrative review from a different CRA officer, since the Federal Court generally expects that step to have been taken first, and it can sometimes resolve matters without going to court at all. For a closer look at how this plays out with denied taxpayer relief applications specifically, see our analysis of seeking judicial review after a denied taxpayer relief request.
A judicial review application is a fundamentally different exercise from a Tax Court trial. The Federal Court does not rehear the facts or take new evidence from witnesses. It reviews the existing record, largely affidavit evidence, to decide whether the CRA’s decision was reasonable: justified, transparent, and based on a coherent chain of reasoning applied to the facts and law, following the framework set out by the Supreme Court in Canada (Minister of Citizenship and Immigration) v. Vavilov. If the Federal Court finds the decision unreasonable, it typically sends the matter back to the CRA for reconsideration rather than substituting its own decision for the CRA’s.
The practical upshot is that choosing between the Informal and General Procedures only matters once you have confirmed you are actually appealing an assessment. If the CRA decision you are unhappy with was discretionary rather than a determination of tax owing, the Tax Court is the wrong forum entirely, and a Canadian tax litigation lawyer can help identify which of the three paths, Informal Procedure, General Procedure, or judicial review, actually fits your situation.
“Taxpayers sometimes come to us wanting to appeal a decision that was never appealable to the Tax Court in the first place,” said David J. Rotfleisch. “Recognizing whether you are dealing with an assessment or a discretionary decision is the first question, not an afterthought, because it determines which court can even hear your case.”
Informal vs. General Procedure: Key Differences at a Glance
| Feature | Informal Procedure | General Procedure |
|---|---|---|
| Dollar threshold | $25,000 or less in federal tax and penalties per year; $50,000 or less for loss determinations and GST/HST | No dollar limit; available for any dispute |
| Filing fee | None | Yes, in tiers based on the amount at stake |
| Representation | Self, a Canadian tax lawyer, or an agent such as an accountant | A Canadian tax lawyer, or self-representation with the Court’s permission; corporations generally need a lawyer |
| Discovery | No formal examination for discovery; documents still exchanged before the hearing | More often written questions and answers than an in-person oral examination; oral examination automatic above $50,000 tax/penalties (or $100,000 loss, or $50,000 GST/HST) |
| Rules of evidence | Court not bound by ordinary rules of evidence | Strict rules of evidence apply |
| Settlement conferences | Not available | Available under Rule 126.2 |
| Typical timeline | Roughly 12 to 18 months | Often several years |
| Costs if you lose | Rarely awarded; modest prescribed tariff | Ordinary tariff costs typically apply, rising to substantial indemnity costs (~80% of legal fees) if you rejected a settlement offer later matched or beaten at trial |
| Appeal if you lose | Federal Court of Appeal, but only on narrow, judicial-review-style grounds under s. 27(1.3) of the Federal Courts Act, heard summarily on the existing record | Federal Court of Appeal, full appeal on the merits |
| Sets precedent | No | Yes |
Key Issues and Findings: Informal vs. General Procedure
Representation. Under the Informal Procedure, a taxpayer may appear personally, retain a Canadian tax litigation lawyer, or have an agent, such as an accountant, appear in the taxpayer’s place. The General Procedure is stricter: individuals may self-represent only with the Court’s permission, and corporations must generally be represented by a lawyer called to the bar in a Canadian province. That corporate-representation rule has itself been the subject of litigation over who, precisely, may stand up for a corporate taxpayer, which is a separate wrinkle worth discussing with an experienced Canadian tax litigation lawyer before a corporation files its Notice of Appeal. For a broader look at how the appeal stage fits into the overall dispute process, see our analysis of Tax Court of Canada appeals.
Process and evidence. The Informal Procedure is deliberately loose. There are no formal pleadings requirements and no examinations for discovery, and the Court is not bound by the ordinary legal or technical rules of evidence, so the hearing can proceed quickly and informally. That said, “no discovery” does not mean “no disclosure”: both sides are still expected to exchange, in advance of the hearing, the documents they intend to rely on, and skipping that step can leave a taxpayer unable to introduce key evidence at trial. The General Procedure looks much more like a conventional civil trial: pleadings (a Notice of Appeal and a Reply, sometimes followed by an Answer) and a formal exchange of documents. Discovery itself can take two forms: an oral examination, where a representative of each side answers questions in person before a court reporter, or an examination by written questions and answers, where a list of questions is served and answered by affidavit within 30 days.
In practice, written questions are used more often than oral examinations, since they avoid the cost and scheduling of an in-person session. An oral examination becomes automatic, rather than optional, only where the amount at issue exceeds $50,000 in tax and penalties (or $100,000 in loss, or $50,000 for GST/HST); below those amounts, an oral examination is held only if both sides agree to it or the Court decides the case cannot be properly conducted without it, though written discovery remains available regardless of the amount in dispute. That extra structure adds time and cost, but it also gives both sides a fuller opportunity to test the evidence before trial, which matters in a factually complex or high-value case.
Moving between procedures. The election is not always permanent. Where the Deputy Attorney General of Canada believes a case has been misfiled under the Informal Procedure, it can bring a motion to move the appeal into the General Procedure. Less commonly, a taxpayer who started under the General Procedure can elect to move into the Informal Procedure within 90 days of the Reply being served, provided the amount in issue falls within the applicable limit.
The Tax Court of Canada Rules (Informal Procedure) set out this reverse election in sections 16 and 17, though the dollar figures printed in the current consolidated Rules ($12,000 and $24,000) appear not to have been updated to match the higher thresholds now used elsewhere for informal eligibility. Given that discrepancy, anyone considering this election should have a Canadian tax litigation lawyer confirm the currently applicable dollar limit directly with the Tax Court registry before relying on it.
Fees and costs. There is no filing fee to commence an Informal Procedure appeal, and win or lose, costs are rarely awarded against either side; where the Court does award costs, it typically follows a modest prescribed tariff. The General Procedure carries a filing fee, set in tiers by the dollar amount at stake. In the ordinary course, a successful party can recover a portion of its legal costs from the other side under the Court’s tariff, which cuts both ways: a taxpayer who wins can recoup real expense, but a taxpayer who loses can be ordered to pay the CRA’s costs as well.
Offers to settle and cost consequences. The stakes rise further once a settlement offer is on the table. Under Rule 147(3.1) and (3.2) of the General Procedure Rules, a party who serves a genuine settlement offer, one involving a real element of compromise, and who then obtains a judgment at trial as favourable as or more favourable than that offer, is generally entitled to substantial indemnity costs, on the order of 80 percent of legal fees, from the date the offer was served onward, on top of ordinary party-and-party costs up to that point.
In practice, this means a taxpayer (or the CRA) who rejects a reasonable settlement offer and then does no better, or worse, at trial can end up paying a meaningful multiple of the costs that would otherwise have applied. This mechanism is specific to the General Procedure; the Informal Procedure has no equivalent rule, though settlement offers can still influence how a judge exercises discretion over the modest costs available there.
“A rejected settlement offer does not just disappear if you lose at trial; it can come back as a much larger costs award,” said David J. Rotfleisch. “Rule 147 exists to reward the party who was reasonable enough to make a fair offer, and taxpayers do not always appreciate how sharply the costs can shift once that threshold is crossed.”
Timing. Because it skips discovery and formal pleadings, the Informal Procedure typically moves faster, often resolving within twelve to eighteen months, while a General Procedure appeal can take considerably longer, particularly if it involves motions, extensive discovery, or a lengthy trial.
Appeal rights, the most overlooked difference. This is often the most consequential distinction between the two tracks, and the one taxpayers are least likely to have considered before filing. A taxpayer who loses a General Procedure appeal has a full right of appeal to the Federal Court of Appeal on any question of law or mixed fact and law. A taxpayer who loses under the Informal Procedure can also appeal to the Federal Court of Appeal, but only on narrow, judicial-review-style grounds set out in subsection 27(1.3) of the Federal Courts Act: that the Tax Court acted without or beyond its jurisdiction, breached natural justice or procedural fairness, made an error of law, based its decision on a perverse or capricious finding of fact made without regard to the evidence, acted because of fraud or perjured evidence, or otherwise acted contrary to law.
That appeal is also heard and decided summarily, without the delay of a full appellate proceeding. In practice, this means an Informal Procedure decision that simply weighs the facts against a taxpayer, without any legal or procedural error, is very difficult to overturn. The Federal Court of Appeal’s 2025 decision in Doostyar v. Canada illustrates how unreceptive the Court is to appeals from Tax Court findings that amount to disagreement with the trial judge’s assessment of the evidence rather than an identifiable legal error.
A brief word on what “judicial-review-style” actually means in practice: it is a fundamentally different exercise from a trial. There is no new evidence and no new witnesses; the Federal Court of Appeal decides the case on the record already built at the Tax Court hearing, largely on the basis of the parties’ written materials, rather than reweighing the facts from scratch. That is a much narrower opportunity than the full appeal on the merits available after a General Procedure loss, and it is why the choice of procedure at the outset can end up mattering more than most taxpayers expect.
No binding precedent. Because Informal Procedure decisions are not intended to set precedent, the CRA is often more comfortable litigating on that track even where its position is weak, since a loss there will not bind it in any future dispute with other taxpayers. A taxpayer with a strong, precedent-worthy case may deliberately proceed under the General Procedure instead, even where the dollar amount would qualify for the Informal Procedure, precisely because the possibility of a binding loss on a recurring issue can pressure the CRA into a more favourable settlement, or into conceding the point, rather than risk a decision that other taxpayers could later cite.
Your Day in Court: Step by Step
Knowing what actually happens, and when, can make the process feel far less abstract. The two tracks share the same starting point but diverge quickly.
Informal Procedure, step by step:
1. You file your Notice of Appeal with the Tax Court, generally within 90 days of the CRA’s confirmation, reassessment, or determination.
2. The Registry verifies the Notice of Appeal and opens a court file.
3. The Registry serves a copy on the CRA by transmitting it to the office of the Deputy Attorney General of Canada.
4. The CRA files a Reply to the Notice of Appeal.
5. The Court sends a Notice of Hearing to both parties, typically giving about six weeks’ notice of the hearing date.
6. Your day in court: you, or your Canadian tax litigation lawyer or agent if you have one, present your case, introduce documents already exchanged with the CRA, and call any witnesses. A Department of Justice lawyer represents the CRA and may cross-examine you and your witnesses. Once the evidence is in, both sides make closing submissions on how the law applies, typically delivered orally given the informal nature of the hearing rather than through a written Factum.
7. The judge issues a decision, either given orally at the hearing or reserved and mailed to you later.
General Procedure, step by step:
1. You file your Notice of Appeal within 90 days, as above.
2. The Registry verifies the Notice of Appeal, and you pay the applicable filing fee within five days of receiving it back from the Registry.
3. The court file is opened, and a certificate of service is issued.
4. The Registry serves a copy on the CRA.
5. The CRA files a Reply. You may then file an optional Answer, generally within 30 days of being served with the Reply.
6. The parties exchange documents. Discovery is more often conducted by written questions and answers than by an in-person oral examination, though an oral examination becomes automatic once the amount at issue exceeds $50,000 in tax and penalties (or $100,000 in loss, or $50,000 for GST/HST).
7. The parties submit a litigation timetable, which the Court then orders, setting deadlines for the remaining steps.
8. A party applies to have the time and place of the hearing fixed, and the Court sends a Notice of Hearing.
9. Your day in court: the hearing looks much more like a conventional trial. Each side is typically represented by a lawyer, your Canadian tax litigation lawyer on one side and Department of Justice counsel on the other, who present the evidence and examine and cross-examine witnesses. Pleadings frame the issues in dispute, and both sides may submit books of documents and case law. Once the evidence has been heard, the lawyers make legal submissions on how the law applies to the facts, and will sometimes support those submissions with a written Factum setting out the argument in detail before the judge rules on both the facts and the law.
10. The judge issues a decision, either orally or reserved, and costs may be requested and awarded under the tariff or, where a settlement offer was in play, at the substantial indemnity level described above.
A few practicalities apply to both tracks on the hearing day itself. Arrive at least 30 minutes early, dress in normal business attire, and expect that food, drinks, and electronics are not permitted in the courtroom without the Court’s leave.
You will testify under oath or solemn affirmation, and any documents you want entered as evidence must be shown to the other party before being handed to the court registrar. The judge has no knowledge of your case beyond what is in the pleadings, so do not assume any background familiarity going in.
Practical Implications for Canadian Taxpayers
For most individuals and small businesses with a dispute under $25,000 (or a $50,000 GST/HST loss), the Informal Procedure remains the practical choice: no filing fee, faster resolution, less exposure to a costs award, and the flexibility to have an accountant or other trusted advisor assist. But “no filing fee” should not be confused with “no need for a lawyer.” The CRA is represented by Department of Justice counsel at every Informal Procedure hearing, and an unrepresented taxpayer is negotiating and arguing against a trained Canadian tax litigation lawyer regardless of which track applies.
For appeals above the dollar thresholds, for cases where full discovery would help develop the facts, or for disputes where a favourable ruling could be useful as precedent in later dealings with the CRA, the General Procedure is worth the added cost and time. It is also the only route to a full appeal on the merits if the case is lost, which matters more in close or legally novel cases than taxpayers often appreciate at the outset.
Takeaway: Informal Procedure vs. General Procedure
The Informal and General Procedures are not simply “cheap” and “expensive” versions of the same process. They differ in who can represent you, what evidence-gathering tools are available, what a loss will cost, and, critically, how much room you have to appeal an unfavourable result. The dollar threshold determines eligibility, but eligibility is not the same as the right choice for every case.
Pro Tax Tips: Choosing Informal or General Procedure
Before filing a Notice of Appeal, work through the practical consequences of each track with an experienced Canadian tax litigation lawyer rather than defaulting to whichever procedure sounds less intimidating. If your dispute is near the $25,000 or $50,000 threshold, consider whether agreeing to cap the claim to access the Informal Procedure actually serves your interests, since giving up part of a legitimate claim to get a faster hearing is not always a good trade.
If your case turns on a genuine question of law rather than a factual dispute, remember that the General Procedure preserves a full right of appeal while the Informal Procedure does not, so a legally uncertain position may be worth the extra cost of proceeding generally. If you are proceeding under the General Procedure, think carefully before rejecting a reasonable settlement offer, since doing so and then failing to beat it at trial can expose you to substantial indemnity costs.
And if the taxpayer is a corporation, confirm early who is entitled to represent it in court, since the General Procedure’s representation rules are stricter than many business owners expect.
“Taxpayers often treat the Informal Procedure as the default because it is cheaper and faster, but cheaper and faster is not the same as better,” said David J. Rotfleisch, founding tax lawyer and CPA at Rotfleisch & Samulovitch, and a Law Society of Ontario Certified Specialist in Taxation. “The real question is what happens if you lose. Under the General Procedure you get a genuine appeal on the merits. Under the Informal Procedure, you are largely stuck with the trial judge’s view of the facts unless something went legally or procedurally wrong. That is a factor clients need to weigh before they file, not after they lose.”
FAQs
What is the dollar threshold to qualify for the Informal Procedure?
Federal tax and penalties in dispute, excluding interest, must be $25,000 or less per taxation year, or the loss in dispute must be $50,000 or less. GST/HST appeals use a $50,000 threshold. (Legislation has been passed to allow these thresholds to rise to $50,000 and $100,000, but that increase is not yet in force as of this writing.)
Can I choose the General Procedure even if my dispute qualifies for the Informal Procedure?
Yes. The General Procedure is available to any taxpayer regardless of dollar amount; the Informal Procedure is the one with eligibility limits.
Can I use the Informal Procedure if my dispute exceeds the dollar threshold?
Often yes, if you state in your Notice of Appeal that you agree to limit your claim to $25,000 (or $50,000 for GST/HST or loss determinations).
Do I need a lawyer for the Informal Procedure?
No. You may self-represent, hire a Canadian tax litigation lawyer, or have an agent, such as an accountant, represent you, though the CRA will still be represented by Department of Justice counsel.
Do I need a lawyer for the General Procedure?
Individuals need the Court’s permission to self-represent, and corporations generally must be represented by a lawyer called to the bar in a Canadian province.
Is there a filing fee?
There is no filing fee for the Informal Procedure. The General Procedure has a filing fee set in tiers based on the amount at stake.
Will I have to go through discovery?
In the Informal Procedure, no formal examination for discovery is held, though documents are still exchanged. In the General Procedure, discovery is more commonly done by written questions and answers than by an in-person oral examination; an oral examination becomes automatic once the amount at issue exceeds $50,000 in tax and penalties (or $100,000 in loss, or $50,000 for GST/HST), and is otherwise held only if requested or ordered.
Can I appeal if I lose?
You can appeal either type of decision to the Federal Court of Appeal, but a General Procedure loss can be appealed on the merits, while an Informal Procedure loss can only be appealed on narrow, judicial-review-style grounds such as jurisdictional error, a breach of natural justice, an error of law, or a perverse finding of fact, decided on the existing record without new evidence or witnesses.
How long does each procedure take?
The Informal Procedure typically resolves in twelve to eighteen months. The General Procedure often takes considerably longer, especially where discovery or motions are involved.
Will I have to pay the CRA’s legal costs if I lose?
Costs are rarely awarded in the Informal Procedure and, when awarded, follow a modest tariff. In the General Procedure, a losing party can be ordered to pay a share of the other side’s costs under the ordinary tariff, and those costs can rise sharply to substantial indemnity levels, roughly 80 percent of legal fees, if you rejected a genuine settlement offer that the other side later matched or beat at trial.
Does an Informal Procedure decision set a precedent?
No. Informal Procedure decisions are not intended to bind future cases. Because a loss there will not bind the CRA in future disputes, the CRA is often more willing to litigate weaker positions on that track; a taxpayer who wants to establish a reusable precedent may instead choose the General Procedure.
Can the CRA force my appeal out of the Informal Procedure?
The Deputy Attorney General of Canada can bring a motion to remove an appeal from the Informal Procedure to the General Procedure, and the Court can give directions for how the appeal proceeds from there.
Does the $25,000 threshold include provincial tax and interest?
No. The threshold is based on the “aggregate amount” in issue, which counts only federal tax and penalties, so provincial tax and interest are excluded when determining whether a dispute qualifies for the Informal Procedure.
Can I switch from the General Procedure to the Informal Procedure after I have already filed?
In limited circumstances, yes, within 90 days of the Reply being served, though the applicable dollar limit should be confirmed with the Tax Court registry or a Canadian tax litigation lawyer before relying on it, since the figures in the Rules have not kept pace with other informal-eligibility thresholds.
What if I missed the 90-day deadline to file my Notice of Appeal?
You may be able to apply to the Tax Court for an extension of time, but the Court is not required to grant it and frequently does not, so missing the original deadline is a serious risk to your appeal rights regardless of which procedure you intend to use.
What happens if I reject a settlement offer and lose?
Under the General Procedure, if the CRA served a genuine settlement offer and you end up with a result at trial that is no better than that offer, the CRA may be entitled to substantial indemnity costs, roughly 80 percent of its legal fees, from the date it served the offer onward. This cost risk is a significant factor to weigh before turning down a reasonable offer.
What actually happens on my hearing day?
In both procedures, you arrive at least 30 minutes early, dress in business attire, and testify under oath or affirmation. You, or your lawyer or agent if you have one, present your evidence and call any witnesses; the CRA’s Department of Justice lawyer has an opportunity to cross-examine, and the judge then rules either the same day or in a reserved decision mailed to you later. General Procedure hearings tend to involve more formal books of documents and case law, more extensive examination of witnesses, and legal submissions from each side’s lawyer once the evidence is in, sometimes backed by a written Factum, reflecting the pleadings and discovery that came before.
What if my dispute is about a discretionary CRA decision, like denied taxpayer relief, rather than an assessment?
Neither Tax Court procedure applies. Discretionary decisions, such as a denied application to cancel penalties and interest, are challenged through an Application for Judicial Review to the Federal Court, not through a Notice of Appeal to the Tax Court. It is generally advisable to request a second-level CRA review first.
DISCLAIMER: This article provides broad information. It is only accurate as of the posting date. It has not been updated and may be out-of-date. It does not give legal advice and should not be relied on as tax advice. Every tax scenario is unique to its circumstances and will differ from the instances described in the article. If you have specific legal questions, you should seek the advice of a Canadian tax lawyer.
About the Author