Published: March 12, 2020
Last Updated: October 27, 2026
Overview: The Lifetime Capital Gains Exemption in 2026 and Why a Tax-Free Sale May Not Be Tax-Free
The lifetime capital gains exemption is the most valuable single tax benefit available to a Canadian business owner. For 2026, it shelters up to $1,275,000 of capital gains on the disposition of qualified small business corporation shares or qualified farm or fishing property, which at Ontario’s top combined marginal rate represents tax savings in the order of $340,000. For many entrepreneurs, it is the difference between a sale that funds a retirement and one that funds roughly half of one.
What has changed, and what most published commentary on the exemption still does not address, is that a gain fully sheltered by the lifetime capital gains exemption can now produce a real and immediate tax liability. Since 2024, the alternative minimum tax includes capital gains eligible for the exemption in its parallel tax base at an effective rate of 30%, because the gain is included in full while the capital gains deduction is recognized at 7/5 of the amount claimed. A founder who sells qualifying shares, claims the exemption in full, and owes nothing under the regular tax calculation can still face a combined federal and provincial minimum tax bill in the order of $50,000 in the year of sale.
This article sets out who qualifies for the exemption, what the current limit is, how the alternative minimum tax interacts with it, and the less visible rules that reduce or eliminate exemption room before a seller ever reaches the qualification tests. It is written for business owners, founders, investors and their advisors who are planning a disposition rather than reacting to one.
Background: Section 110.6, the Current Limit, and What Qualifies
The exemption is found in section 110.6 of the Income Tax Act. It is available only to individuals who are resident in Canada throughout the taxation year in which the claim is made. Corporations cannot claim it. It is claimed on line 25400 of the T1 return, supported by Form T657, Calculation of Capital Gains Deduction, and, where relevant, Form T936 for the cumulative net investment loss calculation.
Two categories of property qualify.
The first is shares of a qualified small business corporation.
The second is qualified farm or fishing property. The two categories share a single lifetime limit, so selling qualifying shares and qualifying farm property in the same lifetime does not produce two exemptions.
The Current Limit and Recent Legislative History
The limit was increased to $1,250,000 for dispositions occurring after June 24, 2024, and indexation resumed in 2026, bringing the 2026 limit to $1,275,000. Two related proposals from the same period did not survive. The proposed increase in the capital gains inclusion rate from one-half to two-thirds was cancelled in March 2025 and never became law, so the inclusion rate remains 50%. The Canadian Entrepreneurs’ Incentive, which would have applied a reduced inclusion rate to up to $2,000,000 of qualifying business gains, was cancelled in Budget 2025.
For the broader budget context, see our article “Canada’s 2025 Federal Budget: What Tax Changes Mean for Entrepreneurs and Business Owners.”
The practical consequence is that the increased exemption survived while the measures that would have sat alongside it did not. The exemption is therefore doing more work in a business sale than it was expected to do when the package was designed.
The Qualification Tests in Summary
For shares to be qualified small business corporation shares, three requirements must be satisfied.
- At the time of disposition, the corporation must be a small business corporation, meaning a Canadian-controlled private corporation with all or substantially all of the fair market value of its assets used principally in an active business carried on primarily in Canada. The CRA takes the position that “all or substantially all” means 90% or more.
- Throughout the 24 months immediately before the disposition, more than 50% of the fair market value of the corporation’s assets must have been used principally in an active business carried on primarily in Canada.
- Throughout the 24 months immediately before the disposition, the shares must not have been owned by anyone other than the individual or a person or partnership related to the individual.
These tests are summarised here because they are set out at length elsewhere. The 24-month holding period in particular carries a body of CRA interpretation that deserves its own treatment, including how the period is affected by trusts, reorganizations and newly issued shares.
Where a corporation fails the 90% test because it holds surplus cash, investments or other passive assets, the usual remedy is purification, which moves the non-active assets out of the operating corporation on a tax-deferred basis so that the operating corporation meets the test. Purification can generally be done reasonably quickly. The 24-month tests cannot. A corporation that fails either 24-month test today cannot be made to satisfy it before a sale that closes within two years, which is why the timing of the planning matters more than its sophistication.
Key Issues and Findings
The Alternative Minimum Tax Now Taxes a Fully Sheltered Gain
This is the single most important change to the practical operation of the exemption, and it has nothing to do with section 110.6 itself.
Since the 2024 taxation year, the alternative minimum tax applies a 20.5% rate to a broadened base of adjusted taxable income, with a basic exemption equal to the start of the fourth federal tax bracket, being $181,440 for 2026. Capital gains enter adjusted taxable income at 100%, while subparagraph 127.52(1)(h)(ii) recognizes 7/5 of the capital gains deduction claimed under section 110.6. Since that deduction is claimed against the taxable half of the gain, 7/5 of one half is 70% of the whole gain, and the combined effect is an effective 30% inclusion of a gain that the regular tax calculation exempts entirely.
Consider a founder who disposes of qualifying shares in 2026 and realizes a capital gain of $1,275,000, sheltered in full by the exemption, with no other income, deductions or credits. Under the regular calculation, federal tax on the gain is nil. Under the minimum tax calculation, the full $1,275,000 enters adjusted taxable income, and the $637,500 capital gains deduction is recognized at 7/5, being $892,500, which leaves adjusted taxable income of $382,500, or 30% of the gain. Subtracting the basic exemption of $181,440 leaves $201,060, which at 20.5% produces gross minimum tax of approximately $41,200.
The basic minimum tax credit, being one half of the credit for the base basic personal amount rather than the enhanced amount, which is ground down at this income level, reduces that by roughly $1,000, leaving federal minimum tax of about $40,200. Ontario’s additional tax for minimum tax purposes, at 24.63% of the federal amount, adds approximately $9,900 before surtax. That provincial amount does not ride on the federal seven-year credit: Ontario operates its own minimum tax carryover, and the two are recovered separately. The combined liability is in the order of $50,100.
The infographic below sets out that computation step by step.
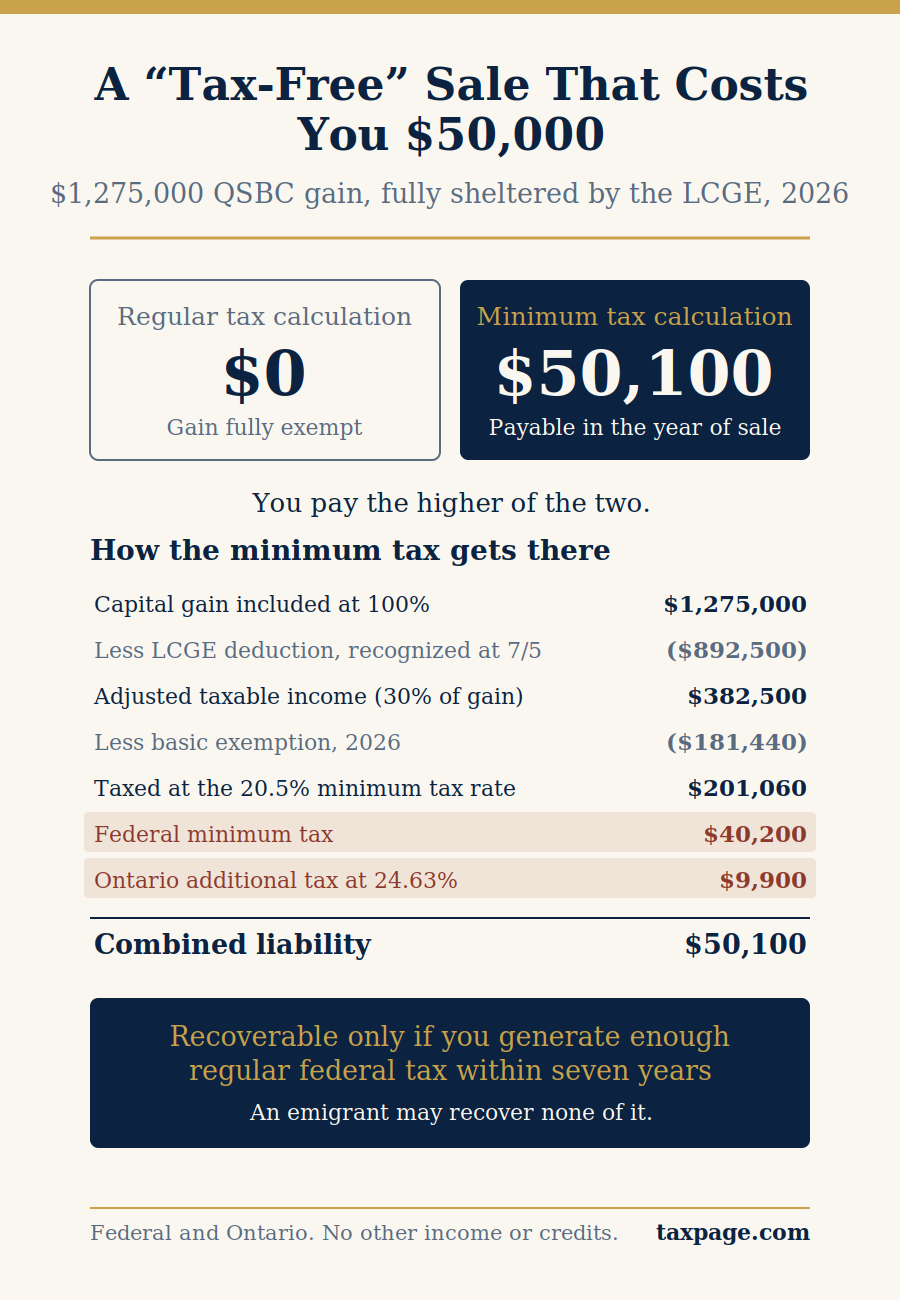
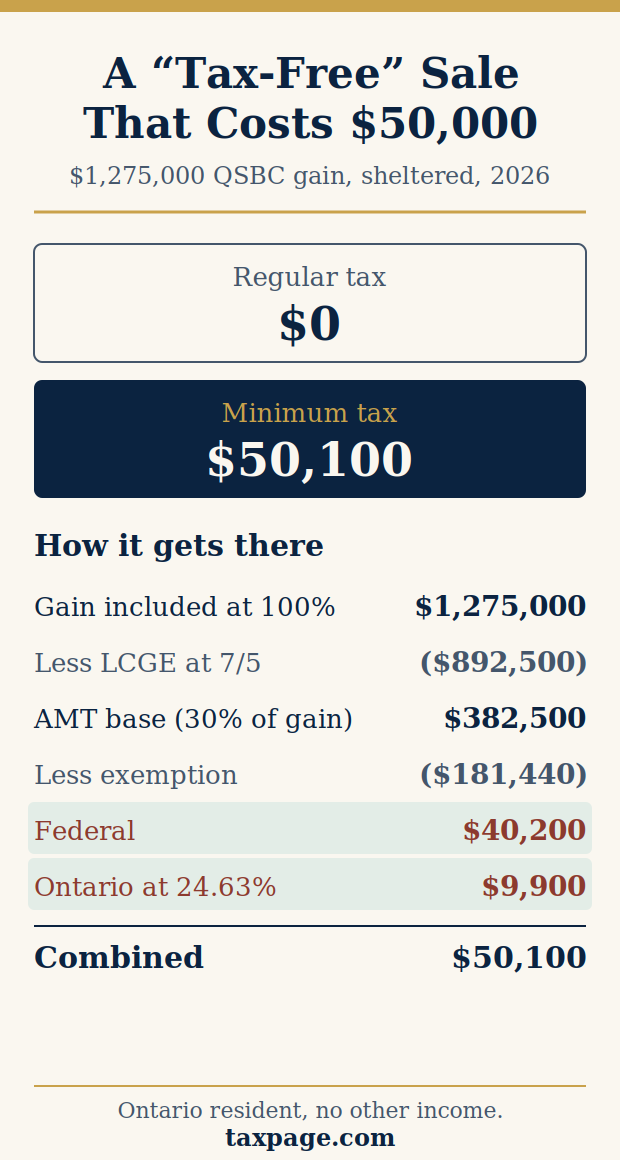
That is roughly $50,100 payable in the year of a transaction on which the regular tax calculation produces nothing at all. The amount is recoverable, in principle, as a credit against regular federal tax in the following seven taxation years, but only to the extent the founder generates enough regular federal tax in that window to absorb it. A founder who sells the business and then has modest income, or who emigrates, or who dies within the period, may never recover it.
Two further points are frequently missed. The provincial rate is not static. Ontario reduced its additional tax for minimum tax purposes from 33.67% to 24.63% effective for 2024, in order to hold the effective provincial rate at 5.05% once the federal rate rose to 20.5%, so commentary still quoting 33.67% is working from a superseded figure. And the provincial component does not form part of the federal carryforward credit, so the recoverability analysis differs between the two layers.
“I regularly see founders who have done everything right on the qualification side, satisfied every test, purified the corporation, held the shares for the full period, and who are genuinely surprised to learn that a sale producing no regular tax has produced a six-figure minimum tax bill,” says David J. Rotfleisch, founding tax lawyer and CPA at Rotfleisch & Samulovitch, and a Law Society of Ontario Certified Specialist in Taxation.
“The exemption has not been taken away. What has changed is that the exemption no longer determines the cash outcome on its own. Any projection prepared before closing has to run the regular calculation and the minimum tax calculation side by side, on a combined federal and provincial basis, and then ask the harder question of whether the credit will actually be recovered.”
Exemption Room Can Be Reduced Before the Tests Are Ever Reached
A seller who satisfies every qualification test may still find that the exemption shelters less than expected, because two balances grind the available deduction.
The cumulative net investment loss balance is the cumulative excess of investment expenses over investment income since 1988. It reduces the capital gains deduction that can be claimed, dollar for dollar. A business owner who has carried interest on investment loans, or who has held investment property producing deductions in excess of income, may have accumulated a significant balance without ever being aware of it. The balance is tracked on Form T936 and can often be reduced in advance by paying a grossed-up taxable dividend to generate offsetting investment income, but only if the balance is identified before closing.
An allowable business investment loss claimed in a prior year also reduces access to the exemption. A seller who claimed such a loss on a failed venture years earlier may have materially less room than the headline limit suggests.
Neither balance is visible on the face of a share purchase agreement, and neither can be fixed after closing.
Multiplying the Exemption Across a Family Now Carries Tax on Split Income Risk
Because the exemption is a per-individual entitlement, spreading share ownership across family members multiplies it. Two spouses can shelter $2,550,000 on a single sale. A family trust holding shares for several beneficiaries can multiply it further, and, unlike direct transfers, allows the principal owner to retain control of the corporation while deferring the decision on how value is allocated until the sale actually occurs.
This planning remains available and remains effective, but it is no longer as simple as it was when it was first popularised. The tax on split income rules apply to capital gains in some circumstances, and a family member who is not sufficiently involved in the business may face a top-rate inclusion under section 120.4 rather than the exemption. Share transfers must be made well in advance of a sale, because transferring shares immediately before closing achieves nothing: the transferor realizes the full gain on the transfer and the transferee has no accrued gain to shelter. The transfer has to precede the growth in value, not follow it.
The 24-month ownership test interacts with this directly, since shares issued to a family member or a trust within the 24 months before disposition will generally fail it.
Incorporated Professionals Face Three Additional Obstacles
Physicians, dentists, lawyers, accountants, engineers and other incorporated professionals are among the most frequent enquirers about the exemption and among the least likely to be able to use it without advance restructuring. Three obstacles recur.
The first is the asset test. A professional corporation that has been retaining after-tax earnings and investing them, which is the ordinary and sensible use of a professional corporation, accumulates exactly the passive assets that break the 90% test at the time of disposition and the 50% test across the preceding 24 months. The corporation is doing nothing wrong. It is simply failing a test it was never structured to pass.
The second is the nature of the transaction. A professional practice is frequently sold as assets, being the patient or client list, the equipment and the goodwill, rather than as shares, because a purchaser wants the practice without the corporate history. The exemption applies only to a disposition of shares. A vendor who accepts an asset sale without modelling the alternative has given up the exemption entirely, and the difference is frequently larger than the price concession that a share sale would have required.
The third is multiplication. Provincial professional regulation restricts who may hold shares of a professional corporation, and the permitted class of shareholder varies by province and by profession. Family multiplication of the exemption, which is straightforward for an ordinary operating company, may be constrained or unavailable, and where non-voting shares can be held by family members the tax on split income reasonableness test applies with particular force to a service business.
None of these is fatal. All three require lead time, and a professional who begins the analysis when a purchaser approaches has usually left it too late.
Employee Stock Options Interact With the Exemption in Three Ways, All of Them Adverse
Founders and early employees of a corporation frequently hold both shares and options, and assume the exemption will shelter the whole of what they receive on an exit. It will not.
The first point is the most basic and the most often misunderstood. A benefit arising on the exercise of an employee stock option is employment income under section 7 of the Income Tax Act, not a capital gain. The lifetime capital gains exemption has no application to it at all. The deduction available under paragraph 110(1)(d) or (d.1) reduces the benefit to an effective one-half inclusion in many cases, which superficially resembles capital gains treatment, but the character of the income is different and the exemption cannot touch it. Only the subsequent gain on the shares acquired, measured from the value at exercise, is a capital gain capable of qualifying.
The second point concerns timing. Shares acquired on the exercise of an option are newly acquired shares, and the 24-month ownership requirement runs from acquisition. An option holder who exercises shortly before a sale in order to participate in it will hold shares that fail the holding test, even where the corporation itself satisfies every asset test. The exercise has to precede the disposition by at least 24 months for those particular shares to qualify. The same analysis applies to founder shares subject to reverse vesting or repurchase rights, where arrangements that delay beneficial ownership until milestones are met can postpone the start of the 24-month clock on each tranche.
The third point is the minimum tax. For alternative minimum tax purposes, 100% of the employee stock option benefit is included in adjusted taxable income, without the deduction that applies under the regular calculation. A founder who exercises options and disposes of qualifying shares in the same taxation year therefore stacks two preference items in the same minimum tax base: the full option benefit, and the sheltered capital gain at its effective 30% inclusion. The resulting liability is materially larger than either event would have produced on its own, and separating the exercise year from the sale year is frequently the single most valuable adjustment available. For the underlying treatment of options, see Employee Stock Options: Tax Implications for Canadian Employees.
Crystallization, Going Public, and the Risk of Qualification Lapsing
Qualification is tested at the moment of disposition, not at the moment the owner decides to sell. A corporation that qualifies today may not qualify in three years if it accumulates passive assets, and a corporation that goes public ceases to be a Canadian-controlled private corporation entirely.
Where qualification is uncertain or the business is on a path that will end qualification, the exemption can be crystallized in advance by deliberately triggering a capital gain on the shares while the tests are still met, typically through an internal share exchange or a sale to a holding company. The exemption is claimed against that triggered gain and the adjusted cost base is stepped up, so later appreciation is taxed but the sheltered amount is locked in. Crystallization has drawbacks, including the alternative minimum tax consequences described above, which now make the decision materially more expensive than it was before 2024.
Resources:
- For the mechanics and the trade-offs, see Crystallizing the Lifetime Capital Gains Exemption.
The Employee Ownership Trust Exemption Stacks on Top, and Escapes the Minimum Tax Where the LCGE Does Not
A business owner weighing an exit should know that the lifetime capital gains exemption is no longer the largest exemption available on a business sale. A qualifying business transfer of shares to an employee ownership trust carries a separate capital gains exemption of up to $10,000,000, introduced in the 2023 fall economic statement and enacted through Bill C-69.
Two features make it worth real attention. The first is that it stacks. The employee ownership trust deduction, found in section 110.61 of the Income Tax Act rather than in section 110.6, is in addition to the lifetime capital gains exemption, so a single vendor on a qualifying transfer can potentially realize something over $11,000,000 of gain free of regular tax.
The second feature is the minimum tax treatment, and it is the point on which published commentary is most often wrong in both directions. The treatment operates at two levels and the enacted text settles both.
At the level of the trust, an employee ownership trust is among the entities listed in section 127.55 to which the minimum tax in section 127.5 does not apply, so the trust itself sits outside the regime entirely. At the level of the vendor, the answer turns on paragraph 127.52(1)(h), which lists exhaustively the deductions under sections 110 to 110.7 that survive into the minimum tax calculation, and on the multiplier attached to each. Subparagraph 127.52(1)(h)(ii) allows 7/5 of the amount deducted under subsections 110.6(2) and (2.1), being the lifetime capital gains exemption. Subparagraph 127.52(1)(h)(vi) allows twice the amount deducted under subsection 110.61(2), being the employee ownership trust deduction, and under subsection 110.62(2) for a qualifying cooperative conversion.
The arithmetic follows directly. A capital gain enters adjusted taxable income at 100%, while the corresponding deduction is claimed against the taxable half. For the lifetime capital gains exemption, 7/5 of one half is 70% of the gain, leaving 30% in the minimum tax base, which is the 30% effective inclusion described earlier in this article. For the employee ownership trust deduction, twice one half is 100% of the gain, leaving nothing. The Department of Finance explanatory notes accompanying the provision put it in terms: subparagraph 127.52(1)(h)(vi) provides for a deduction, for alternative minimum tax purposes, of all gains that were subject to a deduction under subsection 110.61(2).
The practical consequence for a vendor is stark and is the most useful thing in this article for an owner choosing between exit routes. A $1,275,000 gain sheltered by the lifetime capital gains exemption produces roughly $50,100 of combined federal and Ontario minimum tax on the assumptions set out earlier, and a larger sheltered gain produces proportionately more. A $10,000,000 gain sheltered on a qualifying business transfer to an employee ownership trust produces none. The comparison should be stated carefully rather than overstated. Federal minimum tax is recoverable as a credit against regular federal tax over the following seven taxation years, so for a vendor with sufficient regular tax in that window the lifetime capital gains exemption figure is a cash-flow and timing cost rather than a permanent one, and Ontario operates its own carryover for the provincial component. The difficulty is that a one-off business sale is precisely the circumstance in which the regular tax needed to absorb the credit may never arise. The honest formulation is therefore no minimum tax at all on the employee ownership trust route, against minimum tax on the ordinary route that is usually recoverable but may not be. The difference is not a matter of degree. It turns on which paragraph of section 127.52 the deduction falls into, and therefore on who the purchaser is.
Two cautions on the commentary. Some published material asserts that the exempted gain carries a 30% minimum tax inclusion, the same as the lifetime capital gains exemption. That reflects the supplementary information published with Budget 2024, which described a 30% inclusion; the legislation as enacted went further and allowed the full deduction, and the enacted text governs. Other material attributes the employee ownership trust deduction to subsection 110.6(2.1). That is the lifetime capital gains deduction for qualified small business corporation shares. The employee ownership trust deduction is in section 110.61, and the worker cooperative equivalent in section 110.62.
The exemption was originally time-limited to qualifying dispositions occurring between January 1, 2024 and December 31, 2026. That sunset is gone. The Spring Economic Update tabled on April 28, 2026 proposed making the exemption permanent, and Bill C-30, the Spring Economic Update 2026 Implementation Act, received royal assent on June 18, 2026. Advice given before that date, and a good deal of commentary still online, urges owners to complete a transfer before the end of 2026. That urgency no longer applies, and an owner who rushes a succession transaction on the strength of it is reacting to a deadline that Parliament has removed.
The conditions are demanding. The transfer must be a qualifying business transfer in which the trust acquires control, the vendor must have owned the business for the 24 months before the sale, at least 75% of the beneficiaries must be resident in Canada, the $10,000,000 is shared among all vendors on the same transfer rather than available to each, and a clawback applies if the qualifying conditions fail within ten years. An employee ownership trust is also expensive to establish relative to an ordinary share sale. It is not a better answer for every owner. It is, however, an answer that should be modelled alongside a third-party sale rather than discovered afterwards.
Family Business Transfers, Death, and Departure
Three events outside an ordinary third-party sale bring the exemption into play.
A sale of the business to a child or grandchild engages section 84.1, which can convert what looks like a capital gain into a deemed dividend and deny the exemption entirely unless the conditions for a qualifying intergenerational business transfer are satisfied. Those conditions are demanding and require a specific election.
Resources:
- How to Sell Your Family Business to Your Children Using Bill C-59 Intergenerational Business Transfer Tax Rules
- Tax Planning for Intergenerational Business Transfers and Alternative Minimum Tax After Bill C-59
On death, the deceased is deemed to dispose of capital property at fair market value, and the exemption can be claimed on the terminal return against a deemed gain on qualifying shares, which is often the largest single use it ever receives. A relieving rule allows shares to qualify if the corporation met the test at any time in the 12 months before death.
Resource: Deemed Disposition of All Your Assets at Death: Tax Planning for Canadian Business Owners.
On emigration, an individual is deemed to dispose of most property at fair market value, and the exemption may be claimed against a deemed gain on qualifying shares. The minimum tax problem is at its worst here, because an emigrant with no continuing Canadian source income has nothing to recover the credit against.
Resource: A Canadian Tax Lawyer’s Perspective on Emigration Tax Issues.
Practical Implications for Canadian Taxpayers
The planning horizon for the exemption is measured in years, not weeks. The 24-month tests, the timing of family share transfers, purification of passive assets, and reduction of a cumulative net investment loss balance all require lead time, and none can be achieved between signing and closing. A business owner who first raises the exemption with an advisor when a letter of intent arrives has already lost most of the available planning.
Every projection prepared before a sale should model both tax calculations. The regular calculation answers whether the gain is sheltered. The minimum tax calculation answers what is actually payable in the year of sale, and the seven-year credit analysis answers whether that amount comes back. For a seller whose post-sale income will be modest, who intends to leave Canada, or who is advanced in years, the realistic answer to the third question may be that it does not.
“The mistake I see most often is not a technical one, it is a calendar one,” says David J. Rotfleisch. “By the time a letter of intent lands on the desk, the twenty-four month tests have either been met or they have not, the cumulative net investment loss balance is whatever it is, and the shares are held by whoever holds them. Almost nothing that determines the outcome can be changed in the weeks before closing. The owners who capture the full value of this exemption are the ones who started structuring for it two or three years before they had a buyer.”
The CRA audits claims under section 110.6. A claim is supported by valuation evidence, asset listings demonstrating the active business tests throughout the relevant periods, and corporate records establishing ownership for the full 24 months. Contemporaneous documentation prepared at the time of the transaction is considerably more persuasive than a reconstruction prepared two years later in response to a query.
Where the CRA reassesses a claim, the taxpayer’s rights are the ordinary ones: a notice of objection under section 165 of the Income Tax Act, followed, if necessary, by an appeal to the Tax Court of Canada. Learn more about the tax objections process and what an appeal actually costs and what can be recovered.
Takeaway: Plan the Exemption Years Before the Sale, and Model the Minimum Tax
The lifetime capital gains exemption is worth more in 2026 than it has ever been, at $1,275,000 per individual and considerably more across a family. It is also less self-contained than it used to be. Qualification is necessary but no longer sufficient to produce a tax-free outcome, because the alternative minimum tax reaches a sheltered gain at an effective 30% inclusion and can produce a six-figure liability in the year of a sale that the regular calculation treats as exempt.
The exemption rewards owners who treat it as a multi-year structuring exercise and penalises those who treat it as a filing position. The tests are satisfied or failed years before the sale; the grinds accumulate quietly; and the minimum tax consequence is determined by the shape of the transaction rather than by anything that can be adjusted on the return.
Pro Tax Tips
A business owner contemplating a sale within the next three years should commission a qualification review now rather than at the letter of intent stage. That review should test the corporation against the 90% asset test at the current date, test it against the 50% asset test for the trailing 24 months, confirm ownership of the shares for the full 24-month period including any shares issued to family members or a trust, and identify any purification required. It should also retrieve the cumulative net investment loss balance and any allowable business investment loss claimed in a prior year, because both reduce the available deduction and both can sometimes be addressed in advance.
Alongside that review, an alternative minimum tax projection should be prepared on Form T691 on a combined federal and provincial basis, and the recoverability of the resulting credit should be assessed honestly against the seller’s expected income in the following seven taxation years. Where recovery looks doubtful, spreading a disposition across more than one taxation year, aligning it with other income, or reconsidering whether to crystallize at all may preserve more value than any refinement of the qualification analysis.
Where a sale to a child or grandchild is contemplated, or where emigration or estate planning is in view, the exemption analysis should be run together with the section 84.1 conditions, the departure tax rules, or the terminal return as the case requires, because those interactions determine the outcome more often than the exemption rules themselves do.
FAQs
What is the lifetime capital gains exemption limit for 2026?
The limit is $1,275,000 for 2026. That figure is the 2026 indexed amount, increased from the $1,250,000 base that applies to dispositions occurring after June 24, 2024. The limit is cumulative over an individual’s lifetime and is shared between qualified small business corporation shares and qualified farm or fishing property, so claims across both categories cannot exceed the single lifetime figure.
Can a gain that is fully sheltered by the exemption still attract tax?
Yes. Since 2024, the alternative minimum tax includes capital gains eligible for the exemption in adjusted taxable income at an effective rate of 30%, because the full gain is included while the capital gains deduction is recognized at 7/5 of the amount claimed, which offsets 70% of the gain. A gain sheltered in full under the regular calculation can therefore produce a substantial minimum tax liability in the year of sale. On a $1,275,000 sheltered gain in 2026, the combined federal and Ontario amount is in the order of $50,100.
Is the alternative minimum tax recoverable?
In principle, yes. Federal minimum tax paid in excess of regular federal tax becomes a credit that can be applied against regular federal tax in the following seven taxation years. In practice, recovery depends on generating enough regular federal tax within that window. A seller whose income drops after the sale, who emigrates, or who dies during the period may recover little or none of it. The provincial component does not form part of the federal carryforward credit.
What are the three tests for qualified small business corporation shares?
At the time of disposition the corporation must be a small business corporation, with 90% or more of the fair market value of its assets used principally in an active business carried on primarily in Canada. Throughout the preceding 24 months, more than 50% of asset value must have been so used. And throughout the preceding 24 months the shares must not have been owned by anyone other than the individual or a related person or partnership.
Can a corporation be fixed if it fails the asset test?
Often, yes, through purification, which transfers surplus cash, investments and other passive assets out of the operating corporation on a tax-deferred basis so that the operating corporation meets the 90% test. Purification addresses the test applied at the time of disposition. It does not retroactively satisfy the 50% test for the preceding 24 months, which is why a corporation that has been holding significant passive assets for years cannot be made to qualify quickly.
How long does the planning take?
Two years is the practical minimum where either 24-month test is not already satisfied, because neither can be accelerated. Family share transfers need longer still, since the shares must be held for 24 months and must also have time to appreciate before the sale in order for there to be a gain in the transferee’s hands worth sheltering.
What is a cumulative net investment loss and why does it matter?
It is the cumulative excess of investment expenses over investment income since 1988, tracked on Form T936. It reduces the capital gains deduction that can be claimed, dollar for dollar. A business owner who has deducted interest on investment borrowing, or carried investment property producing deductions in excess of income, may have a balance that materially reduces the exemption without ever having been aware of it. It can sometimes be reduced in advance by paying a grossed-up taxable dividend, but only if identified before closing.
Can my spouse and children also claim the exemption?
Yes, because the exemption is a per-individual entitlement. Two spouses can shelter $2,550,000 on a single sale, and a family trust can extend it further while allowing the principal owner to retain control and defer the allocation decision. The planning must be done well in advance, the 24-month ownership test applies to each holder, and the tax on split income rules can apply to family members who are not sufficiently involved in the business.
Is the employee ownership trust exemption still available, and does it stack with the LCGE?
Yes to both. A qualifying business transfer of shares to an employee ownership trust carries a separate exemption of up to $10,000,000, which is in addition to the lifetime capital gains exemption, so a vendor on a qualifying transfer can potentially shelter over $11,000,000 in total. The $10,000,000 exemption was originally limited to dispositions before 2027, but Bill C-30 received royal assent on June 18, 2026 and removed that sunset, so it is now permanent. On the minimum tax, the exempted gain escapes it. Subparagraph 127.52(1)(h)(vi) allows twice the amount deducted under subsection 110.61(2) in computing adjusted taxable income, which fully offsets a gain included at 100%, and the trust itself is separately listed in section 127.55 among the entities to which the minimum tax does not apply. That is a material difference from the lifetime capital gains exemption, where subparagraph 127.52(1)(h)(ii) allows only 7/5 of the deduction and leaves a 30% effective inclusion. The qualifying conditions are strict: the $10,000,000 is shared among all vendors on a single transfer, and a ten-year clawback applies.
Does the exemption apply to my employee stock options?
No. A stock option benefit is employment income under section 7, not a capital gain, so the exemption cannot shelter it. Only the gain on the shares after exercise can qualify, and those shares must still satisfy the 24-month ownership test running from the date of exercise. Exercising options in the same year as a share sale also stacks two preference items in the alternative minimum tax base, because 100% of the option benefit is included for minimum tax purposes. Separating the exercise year from the sale year is often worth more than any other single adjustment.
Can an incorporated professional claim the exemption?
Often yes, but rarely without restructuring. A professional corporation that has retained and invested after-tax earnings will usually fail the active business asset tests, and purification takes time. Many practices are also sold as assets rather than shares, which puts the sale outside the exemption altogether. Provincial rules on who may hold shares of a professional corporation can further restrict multiplying the exemption across a family. Each of these can be addressed, but only in advance.
Does the exemption apply if I sell the assets of my business rather than the shares?
No. The exemption applies to dispositions of qualifying shares and of qualified farm or fishing property. An asset sale by the corporation does not qualify, which is one of the principal tax reasons a vendor prefers a share sale while a purchaser often prefers an asset purchase.
Can the exemption be claimed on death or on leaving Canada?
Yes in both cases. On death, the deceased is deemed to dispose of capital property at fair market value and the exemption may be claimed on the terminal return, assisted by a relieving rule that allows shares to qualify if the corporation met the test at any time in the 12 months before death. On emigration, there is a deemed disposition and the exemption may likewise be claimed, although the minimum tax exposure is at its most severe for an emigrant with no continuing Canadian source income.
What happens if the CRA denies my claim?
The ordinary dispute route applies. A notice of objection may be served under section 165 of the Income Tax Act, and if the objection does not resolve the matter, an appeal may be brought to the Tax Court of Canada. Claims under section 110.6 are an audit focus, so the quality of the contemporaneous documentation supporting the qualification tests usually determines the outcome.
When should I involve a Canadian tax lawyer?
Before the transaction is structured, not after it closes. Almost every element that determines whether the exemption is available, and what it actually produces after minimum tax, is fixed by decisions made months or years before a sale. A seasoned Canadian tax lawyer can run the qualification review, structure purification and family holdings, model the minimum tax consequence, and preserve the position in the event of a later CRA tax audit or tax reassessment.
DISCLAIMER: This article provides broad information. It is only accurate as of the posting date. It has not been updated and may be out-of-date. It does not give legal advice and should not be relied on as tax advice. Every tax scenario is unique to its circumstances and will differ from the instances described in the article. If you have specific legal questions, you should seek the advice of a Canadian tax lawyer.
About the Author